Going on vacation? Looking for peace of mind and a better way to protect your home?
Check out the link below to view a recently released short video from Chubb with great suggestions:
There’s an app for that!
Agency contact information and Chubb advice at your fingertips when you need it. Click here.
Determining coverage for mudslide claims
Policyholders need to know the difference between mudslides and mudflows and if coverage applies. Read more.
Upcoming travel?
This tip sheet from Chubb provides great suggestions for anyone with vacation plans in the next few months:
Protecting High-Net-Worth Assets in an Evolving Risk Landscape: 2025 Trends
The risk and insurance landscape for high-net-worth individuals (HNWIs) is rapidly evolving due to legal, economic, and environmental changes. From the rise of nuclear verdicts driving liability exposures to increasing material costs affecting home valuations, strategic insurance planning has never been more critical to protecting high-net-worth assets. Additionally, catastrophic weather events, shifting real estate dynamics, and the ripple effects of disasters like last year’s hurricanes and the Palisade and Eaton wildfires demand a reassessment of coverage strategies.
This overview outlines key areas of concern and solutions to ensure that HNWIs maintain robust financial protection against emerging risks:
- The Growing Need for Umbrella Liability Coverage Amid Nuclear Verdicts
- Adjusting Home Valuations to Address Underinsurance Risks and Insuring High End Vehicles with Appropriate Replacement Cost Coverage
- Investing in Home Resiliency to Mitigate Catastrophic Weather Risks
- Flood Insurance Trends & Rising Exposure Risks
- Shifts in the Real Estate Market & Their Insurance Implications
- Insurance Market Adjustments Post-Palisades and Eaton Wildfires
Deep Dive: The Risks in Detail and Solutions
1. The Growing Need for Umbrella Liability Coverage Amid Nuclear Verdicts 
Understanding the Risk
Nuclear verdicts—jury awards exceeding $10 million—are on the rise, particularly in cases involving personal liability, auto accidents, and premises liability. Plaintiffs’ attorneys increasingly target individuals with substantial assets, leveraging social inflation and jury sympathy to secure massive settlements.
Why Standard Liability Coverage Is Insufficient for Protecting High-Net-Worth Assets
Most primary home and auto insurance policies offer liability limits between $300,000 and $500,000, an amount that is often inadequate in the face of today’s legal climate. One severe accident or lawsuit could result in financial devastation if assets are not properly protected.
Solution: High-Limit Umbrella Policies
An umbrella liability policy provides excess coverage beyond home and auto policies, ensuring financial security against high-stakes litigation that can threaten high-net-worth assets. For HNWIs, policies with limits of $5 million to $100 million are available, depending on asset exposure and risk profile. If limits have not been reviewed in the last few years, now is the time.
2. Adjusting Home Valuations to Address Underinsurance Risks and Insuring High End Vehicles with Appropriate Replacement Cost Coverage
Homes:
The Rising Cost of Rebuilding
Within the last five years, we have seen a surge in construction costs post pandemic and, most recently, with tariff uncertainty causing overall construction costs to increase roughly 40%. Many factors driving this include:
- Supply chain disruptions impacting building material delivery timelines and costs.
- Labor shortages inflating contractor expenses.
- Increased demand following natural disasters driving up rebuilding costs.
The Underinsurance Problem
Many HNWIs fail to regularly adjust their home insurance coverage to reflect these market shifts, especially after renovations and additions, leaving properties significantly underinsured. This discrepancy becomes painfully clear when claims settlements fall short of actual reconstruction costs.
Solution: Appraisals & Guaranteed Replacement Cost Coverage
- Appraisals post issuance for new policies and updating your insurance advisor of home improvements ensure that insured values reflect current rebuilding expenses. It is important to note that replacement costs are calculated differently than market value costs.
Guaranteed replacement cost policies cover full reconstruction costs, even if they exceed policy limits.
Cars:

New Technology Impacts
Newer, high-end vehicles have similarly seen pain points on the insurance front making it important to insure appropriately. The conveniences of high-tech smart car features and the evolution of electric vehicle technology has significantly impacted the repair costs and components that go into your new vehicles – and how insurance companies need to respond.
Solution: Premium Insurance Coverage and Flexibility to Choose the Right Body Shop
- Choose an insurance carrier that matches the sophistication of your car. Policies that offer Agreed value and robust temporary rental vehicle limits for your vehicles and collector cars help you avoid out of pocket expenses when a claim happens.
- Having the flexibility to use an auto body shop that has the appropriate equipment, licensed staff, and original equipment manufacturer parts for the repairs are important not only for the vehicle safety features but also, so you don’t void out any vehicle warranties.
3. Investing in Home Resiliency to Mitigate Catastrophic Weather Risks
The Growing Threat of Extreme Weather
Hurricanes, wildfires, and other climate-driven disasters are occurring with greater frequency and severity. HNWIs must proactively fortify their properties to reduce risk exposure and secure better insurance terms.
Home Resiliency Investments That Matter
- Fire-resistant materials & ember-resistant vents (critical in wildfire-prone regions).
- Hurricane-rated windows, reinforced roofs, and flood engineering considerations (for coastal and storm-exposed properties).
- Backup power solutions (such as whole-home generators) to maintain security and prevent losses.
Insurance Benefits of Proactive Resiliency
Carriers are increasingly offering premium discounts and favorable terms for policyholders who invest in risk mitigation strategies, making these upgrades financially strategic.
4. Flood Insurance Trends & Rising Exposure Risks Related to Protecting Your High-Net-Worth Assets
Expanding Flood Risk Beyond FEMA Flood Zones
It’s important to remember that low risk does not mean no risk. Climate change is driving unexpected flooding in areas previously considered low-risk which is driving this as a needed component of a family’s insurance portfolio. According to recent studies, over 25% of flood insurance claims now come from properties outside FEMA’s designated high-risk zones.
Challenges with National Flood Insurance Program (NFIP) Coverage
- NFIP policies cap coverage at $250,000 for dwellings and $100,000 for contents, which is far below the needs of HNWI’s homes.
- FEMA’s Risk Rating 2.0 has led to significant premium increases, making private flood insurance a more attractive option.
Solution: Private Flood Insurance & Excess Flood Coverage
- Private flood carriers offer higher limits and more flexible terms.
Excess flood policies provide coverage beyond NFIP caps, ensuring full protection.
5. Shifts in the Real Estate Market & Their Insurance Implications

Market Trends Affecting HNWIs
- HNWIs continue to purchase homes in high-risk areas.
- Coastal and wildfire-prone areas face increasing insurance challenges, leading some homeowners to relocate.
- Carriers are reevaluating underwriting criteria, with some withdrawing from high-risk regions altogether.
Impact on Insurance Strategies
Properties in high-risk zones may require specialty insurance markets.
Multi-property owners should consolidate policies with high-net-worth specialty agents and insurers to optimize coverage and costs. By leveraging the entire insurance program, terms become more favorable and create consistency with holistic coverage and risk management philosophies.
The earlier you can discuss a potential new property purchase with your insurance agent, the better so they can provide important home risk characteristics to consider and contemplate the best possible insurance and risk management options available.
6. Insurance Market Adjustments Post-Palisades and Eaton Wildfires

The Fallout of the Wildfires
The Palisades and Eaton wildfires were a stark reminder of the increasing wildfire risk for affluent homeowners, particularly in California and other fire-prone states. In the aftermath:
- Insurers tightened underwriting standards, with some carriers ceasing to write new policies in high-risk zones.
- Premiums are increasing for existing policyholders.
- Non-renewals increased, forcing homeowners to seek coverage through surplus lines carriers.
Solutions for HNWIs in High-Risk Fire Zones
- Work with specialized high-net-worth insurance carriers that understand the unique needs of affluent homeowners.
- Implement fire mitigation strategies (e.g., defensible space, home hardening) to maintain insurability.
Conclusion: A Proactive Approach to Insurance for Protecting High-Net-Worth Assets
As risks evolve, high-net-worth individuals must take a proactive approach to insurance planning to protect their wealth, properties, tangible assets, and personal liability exposures. Key takeaways include:
- Umbrella liability coverage is essential to shield against nuclear verdicts.
- Insuring your home to value and reassessing when renovating are necessary to prevent underinsurance.
- Investing in home resiliency mitigates catastrophic weather risks.
- Flood insurance must be evaluated beyond FEMA guidelines.
- Shifts in real estate markets require tailored insurance solutions.
- Post-wildfire insurance challenges necessitate specialized underwriting and risk mitigation strategies.
By partnering with an experienced high-net-worth insurance advisor, clients can secure comprehensive, customized coverage that adapts to an increasingly complex risk environment.
Would you like further insights into any of these topics or assistance in reviewing your current coverage? Reach out to our office to discuss!
Interested in learning more? Check out our Insights page for other relevant education topics.
2026 Personal Insurance and Risk Management Trends in Private Client Services
A Comprehensive Analysis of Emerging Risks, Market Dynamics, and Strategic Solutions for High-Net-Worth Individuals
The private client insurance landscape is experiencing unprecedented transformation driven by converging forces: escalating climate-related catastrophes, explosive cyber threats, nuclear verdict litigation trends, and the largest intergenerational wealth transfer in history. As we enter 2026, high-net-worth (HNW) individuals and families face a fundamentally different risk environment than existed even five years ago.
Key findings include:
- Climate-driven property insurance costs rose 10.4% nationally in 2024, with catastrophe losses reaching $176 billion
- Personal cyber risk exposure exploded 3,000% for deepfake fraud, with average U.S. breach costs exceeding $10.22 million
- Nuclear verdicts ($10M+) median awards reached $23.8M in 2023, creating liability insurance crises
- Baby boomers control $19.7 trillion in real estate (41% of U.S. total), creating complex transfer challenges
- Protection gaps widened significantly, with only 47% of catastrophe losses insured in 2024
For private clients, their advisors, and family offices, 2026 demands proactive risk management strategies addressing these interconnected exposures while navigating an increasingly complex insurance marketplace.
The Evolving High-Net-Worth Risk Landscape
Baby boomers control $19.7 trillion in U.S. real estate—41% of total value despite representing only 20% of the population[1]. This concentration, combined with aging properties and intensifying climate risks, creates unprecedented insurance challenges.
High-net-worth individuals face converging exposures: multiple properties across catastrophe-prone regions, valuable collections requiring specialized coverage, elevated liability risks from social inflation, complex estate structures demanding policy coordination, and growing cyber vulnerability as digital wealth management expands.
The insurance protection gap has widened dramatically. In 2024, U.S. catastrophe economic losses reached $176 billion while insured losses totaled only $99 billion—a $77 billion protection gap[2]. For private clients, this reflects underinsurance from rapid property appreciation, coverage exclusions for flood and earth movement, policy sub-limits, increasing carrier restrictions in high-risk areas, and, in some cases, the choice to self-insure.
1. Climate Change and Property Insurance Crisis
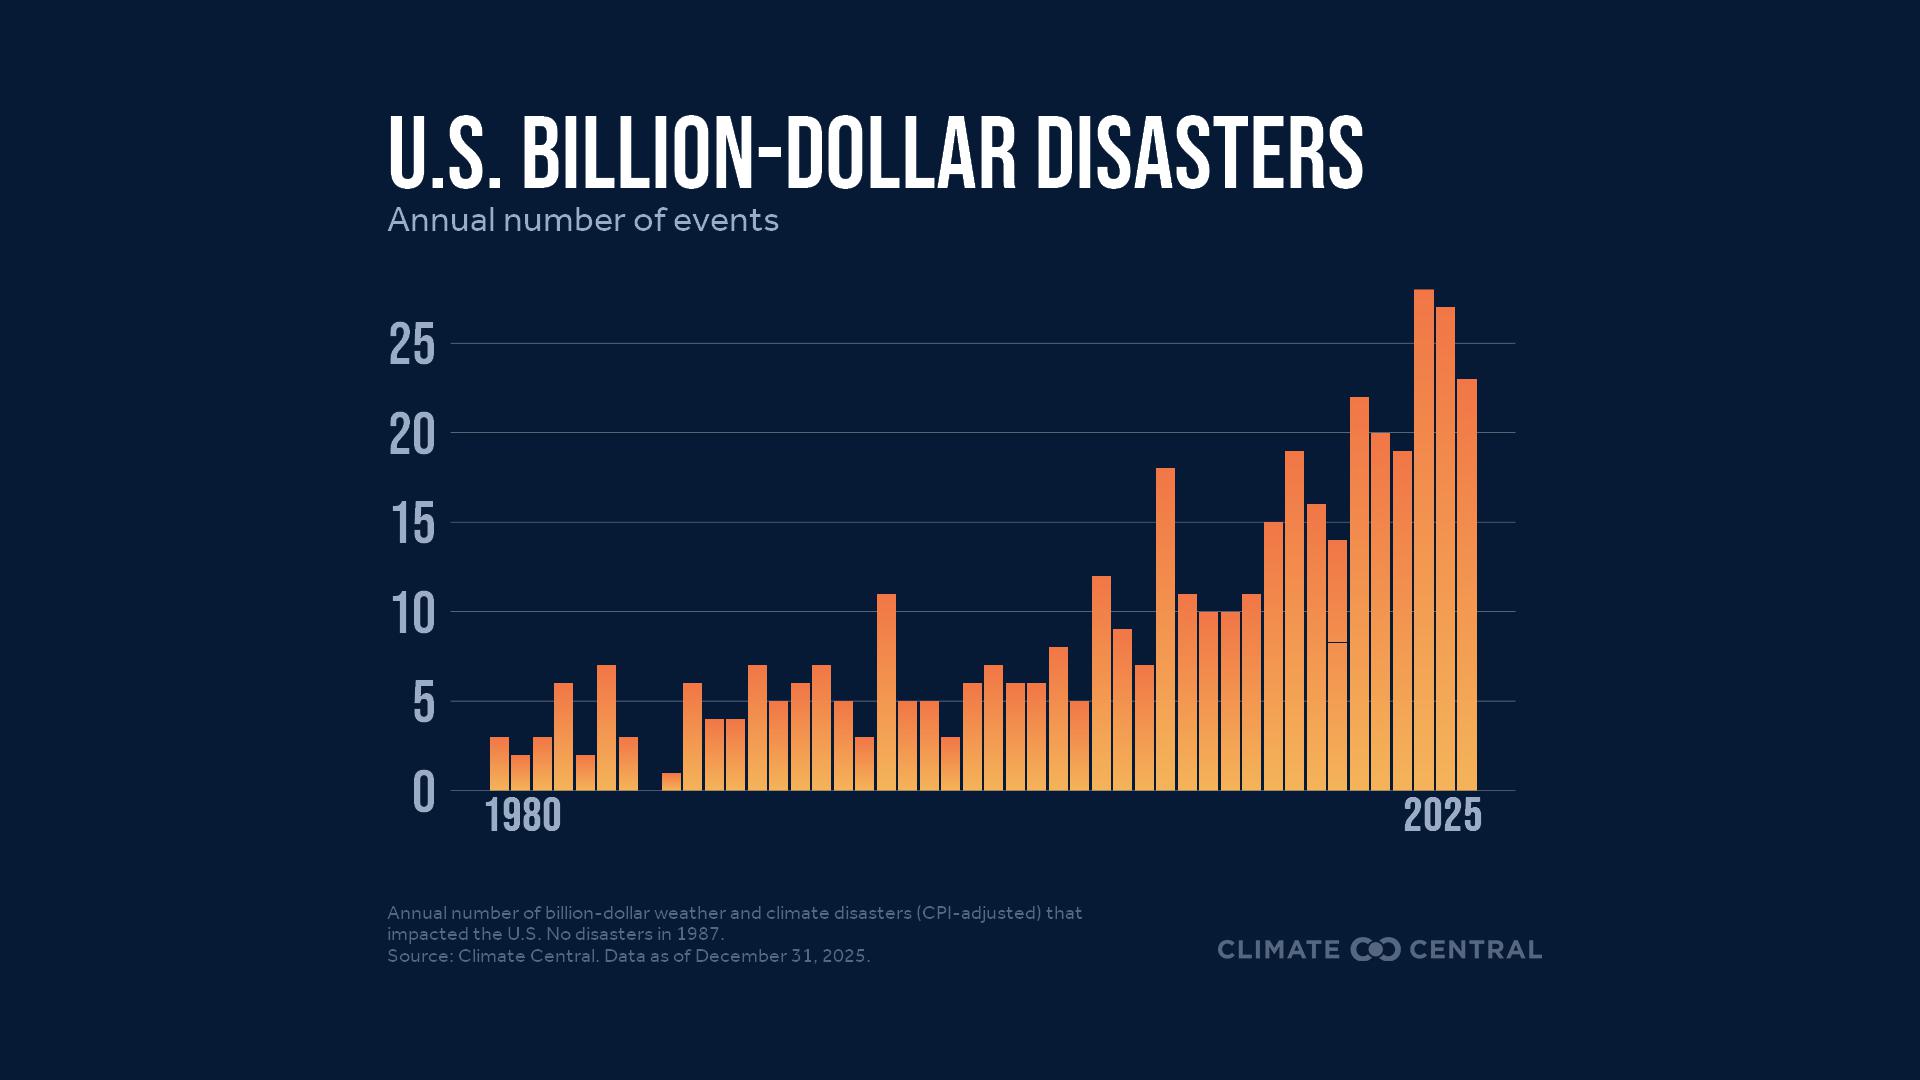
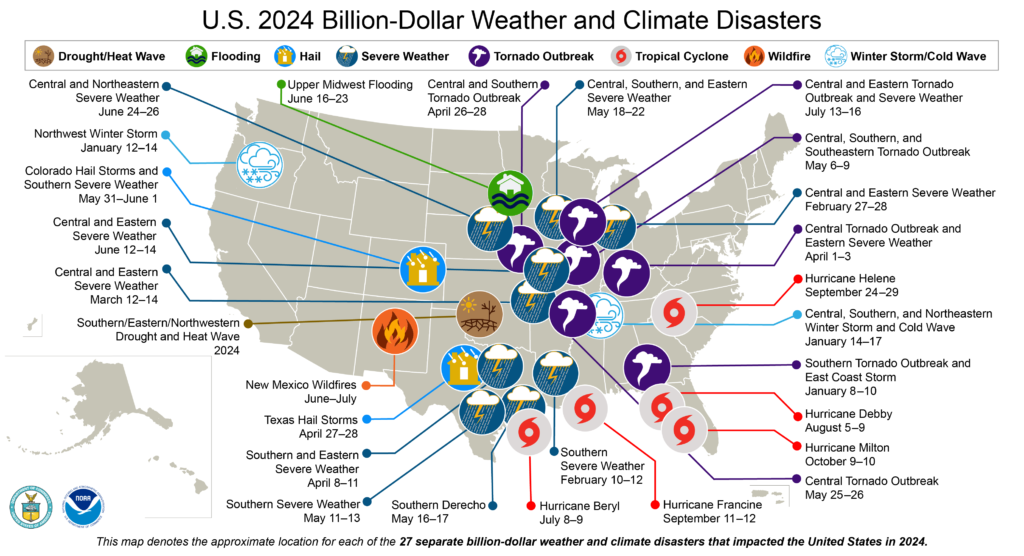
The year 2025 marked the fourth-warmest on record for the United States, with 27 weather disasters exceeding $1 billion in losses each[3]. Notable events included the Eaton and Palisades Fires destroying 18,000+ structures in Southern California, Texas Hill Country’s 1-in-1,000 year flood killing 135 people, and 1,559 tornado reports—fifth-highest on record[3].
Sea level rise has doubled from .06 inches to .14 inches annually, creating 3-9 times more frequent coastal flooding than 50 years ago[4]. Combined with accelerating drought (42.8% of U.S. affected per US Drought Monitor), these trends fundamentally reshape property insurability.[4]
Insurance Market Response:
Homeowners insurance rates increased 10.4% nationally in 2024, with six states exceeding 20%[5]. Major carriers withdrew from California, Florida, and Louisiana, forcing reliance on surplus lines (up 31.2% to $5 billion) and residual markets (up 6% to $10 billion)[5]. Carriers implemented percentage-based wind/hail deductibles, roof age restrictions, and tightened underwriting standards.
For HNW clients with multiple high-value properties, this creates acute challenges: limited carrier options, higher premiums, broader exclusions, and potential uninsurability in catastrophe-prone coastal and wildfire zones where many retirement properties are concentrated.
How to address:
Home Resiliency
- Prioritize loss‑prevention tools as these steps can improve insurance options and potentially reduce premiums:
- Water leak detection and automatic shutoff systems
Whole home backup generators
Annual or seasonal maintenance checklists to address minor issues before they become major
Coverage Options
Review your policy for exposures such as flood, earthquake, and sinkhole to determine whether adding these coverages makes sense based on where your home is located.
Acquisitions
- Consult your advisor before making an offer—especially for out of town or out of state home purchases. This helps you ask your realtor the right questions, improve insurability, manage long term costs and make educated buying decisions.
- Consolidating coverage with one carrier can enhance program efficiency, improve eligibility for better coverage, and ensure consistency across policies to prevent gaps or overlaps in coverage.
2. The Cyber Threat to Personal Wealth
Escalating Personal Cyber Threats
Ransomware Evolution
Ransomware was involved in 44% of all data breaches in 2024, with attacks shifting to “double extortion”—stealing personal financial records, tax returns, estate documents, and smart home data before encrypting systems and threatening public release[7].
The Deepfake Epidemic
AI-generated deepfakes exploded 3,000% in 2025, enabling unprecedented fraud targeting wealthy individuals[9]:
- Voice cloning of family members requesting urgent wire transfers
- Video impersonations of financial advisors authorizing transactions
- Synthetic identity creation for account takeovers
- AI-enhanced phishing with 54% success rates—quadruple traditional methods[10]
Shadow AI Risks
Household staff and family members using unauthorized AI tools (ChatGPT, Claude) for convenience create data leakage risks as personal information may be retained and exposed.
Cyber Risk Management Best Practices
Private clients should implement layered cyber defenses:
Technical Controls
- Multi-Factor Authentication (MFA): Strongly recommended for all financial accounts, email, cloud storage.
- Endpoint Detection & Response (EDR): Advanced antivirus/anti-malware on all devices
- Network Segmentation: Separate IoT/smart home devices from financial/personal computing
- VPN Usage: Virtual private networks for all remote/travel internet connections
Interactive Best Practices
- Wire Transfer Protocols: Verbal confirmation of all wire instructions via known phone numbers
- Email Authentication: Training to identify phishing, suspicious links, urgency-based manipulation
- Social Media Privacy: Limit disclosure of travel, property locations, purchases, family information
Coverage Coordination
- Review homeowners for any cyber coverage endorsements and what limits are available.
- Coordinate with any business cyber policies if working from home.
- Understand what is and isn’t covered.
3. Nuclear Verdicts and Liability Crisis
Nuclear verdicts—jury awards exceeding $10 million—have escalated dramatically. Analysis of 1,288 verdicts from 2013-2022 reveals median awards reaching $23.8 million in 2023 (up from $21.1 million), with mega verdicts ($100M+) increasing 400% since 2013[14].
Florida leads with 0.939 verdicts per 100,000 people—50% higher than New York. California, Florida, New York, and Texas produce half of all national nuclear verdicts[15]. State courts host 90% of verdicts versus only 10% in federal courts.
Critically, noneconomic damages (pain and suffering) drive verdict severity. In seven of ten years, noneconomic damages exceeded punitive damages, demonstrating susceptibility to psychological manipulation including “reptile theory” tactics, anchoring (suggesting arbitrary amounts that double to quadruple awards), and $1 billion in annual lawsuit advertising normalizing extreme awards[16][17][18].
Impacts on Private Clients
A 2025 Georgia jury awarded $4.2 million for a dog attack—far exceeding typical homeowners policy sub-limits of $100,000-500,000[19].
Making sure you have an appropriate umbrella limit is paramount. This limit of coverage is meant to be a moving target that is adjusted as your lifestyle evolves. Have a conversation with your advisor to discuss any significant changes in your net worth and/or public profile. Higher limits are available and we’re here to help.
4. Intergenerational Wealth Transfer Challenges
Baby boomers control $19.7 trillion in real estate, with the boomer population projected to decline 23% by 2035 and another 47% by 2045—transferring enormous holdings to millennial and Gen X heirs[21][22]. However, nearly 40% have lived in current homes 20+ years, with 68% in homes at least 30 years old[23]. Deferred maintenance—aging roofs, HVAC systems, electrical, and plumbing—often requires $50,000-$200,000+ in immediate upgrades inheritors lack funds to complete.
Insurance Complications
When aging parents move to assisted living, standard homeowners policies limit vacant property coverage to 30-60 days, requiring vacant home endorsements (30-50% higher premiums), regular inspections, winterization, and security monitoring. Failure to maintain proper coverage results in claim denials for theft, vandalism, or weather damage.
Post-inheritance, carriers increasingly restrict coverage on older homes through roof age limitations (declining roofs over 15-20 years), four-point inspections, wind mitigation requirements, and wiring restrictions. Inheritors may discover properties uninsurable without significant investment.
Multiple heirs create additional complications: disagreement on disposition, unequal contribution ability, mortgage difficulties, and liability exposure when one heir is judgment-proof while another has assets.
Many boomers retired to Sunbelt locations—Florida, California, Texas, Louisiana, Arizona—now facing acute climate risks. Millennial inheritors discover properties in locations they don’t want with deteriorating insurance availability. [26].
Avoiding Underinsurance (and Overinsurance)
- Choose carriers that use in home appraisals, apply annual inflation guards, and offer guaranteed or extended replacement cost. These protections help maintain proper insurance to value.
- If you haven’t appraised your fine art, jewelry, or collectibles in 3–5 years, schedule an updated review. Rising precious metal values mean some items may now be underinsured, while others may not require as much coverage and should be reduced which would provide a premium savings.
Asset Transfer Guidance
- Speak with your advisor before transferring assets to ensure proper risk management and insurance planning.
- Advisors can help prepare the next generation with education, loss prevention strategies, and insurance guidance.
- Homes: Discuss improvements that enhance home resiliency and insurability.
- Jewelry, fine art, wine/spirits: Review loss likelihood and proper insurance and risk management approaches.
- Middle market carriers often won’t insure high value items, or, in some cases, charge more for inadequate coverage.
- Asset transfers often indicate that the next generation needs a more sophisticated, high net worth insurance program.
- Working with a private client insurance advisor ensures proper coverage, carrier selection, and expert guidance.
2026 Market Outlook
The private client insurance landscape of 2026 is characterized by converging mega-trends which interact and compound and the need to adjust accordingly is evident.
Property insurance faces continued volatility with national average increases projected 8-12% for homeowners, and 15-25% on average in catastrophe-prone states (FL, CA, TX, LA).
Percentage-based wind/hail deductibles expand beyond coastal zones, roof age limitations tighten to 15-year maximums, and carriers reduce willingness to write vacant or secondary homes. However, reinsurance rates declined 6.6% at January 2025 renewals, bringing modest relief.
Personal cyber policies are becoming a standard need for all clients, with limits increasing in response to the increasing risk.
Umbrella/excess liability premium increases moderate to 5-10% in 2026 after prior 15-30% spikes. There is additional underwriting scrutiny on driver records, property maintenance, dog breeds, and water features.
Conclusion
As the private client insurance environment undergoes rapid and profound change, high net worth individuals face a level of complexity and exposure unlike any previous era.
Climate driven property volatility, surging cyber threats, escalating liability awards, and the massive transfer of aging assets across generations are reshaping both risk and insurability.
In this landscape, protection gaps widen quickly, traditional carriers offer fewer solutions, and the costs of inaction grow exponentially. The path forward requires proactive planning—strengthening property resiliency, modernizing cyber defenses, securing adequate liability protection, and preparing heirs with the right education and insurance structures.
By partnering with skilled private client advisors and adopting a coordinated risk management strategy, families can safeguard wealth, maintain insurability, and navigate the evolving challenges of 2026 and beyond with confidence.
We invite you to reach out with any questions as we’re here to provide recommendations, information and guidance.
Interested in learning more? Check out our Insights page for other relevant education topics.
References
[1] Redfin analysis (2025). Baby boomer real estate holdings. Business Insider.
[2] National Association of Insurance Commissioners. (2025). Natural Catastrophe Risk Dashboard Report, December 31, 2024.
[3] National Centers for Environmental Information (NCEI). (2025). Assessing the U.S. Temperature and Precipitation Analysis in 2025. NOAA.
[4] NOAA Climate.gov. (2025). Sea level change data. National Oceanic and Atmospheric Administration.
Climate Change: Global Sea Level | NOAA Climate.gov
Monthly Climate Reports | Drought Report | December 2025 | National Centers for Environmental Information (NCEI)
[5] National Association of Insurance Commissioners. (2025). Homeowners loss ratio and P&C combined ratio data. Natural Catastrophe Risk Dashboard Report. Natural Catastrophe Risk Dashboard Report.pdf
[6] Khalil, M. (2025, December 3). Cyber Insurance Statistics 2025: Key Trends & Data. DeepStrike. https://deepstrike.io/blog/cyber-insurance-statistics-2025
[7] Khalil, M. (2025). Ransomware involvement in data breaches. Cyber Insurance Statistics 2025. DeepStrike.
[8] Khalil, M. (2025). Ransom demand and payment dynamics. Cyber Insurance Statistics 2025. DeepStrike.
[9] Khalil, M. (2025). Deepfake fraud statistics. Cyber Insurance Statistics 2025. DeepStrike.
[10] Khalil, M. (2025). AI-enhanced phishing success rates. Cyber Insurance Statistics 2025. DeepStrike.
[11] Khalil, M. (2025). Business email compromise claim statistics. Cyber Insurance Statistics 2025. DeepStrike.
[12] IBM Security. (2025). Cost of a Data Breach Report 2025. Cited in DeepStrike Cyber Insurance Statistics 2025.
[13] IBM Security. (2025). AI and automation impact on breach costs. Cost of a Data Breach Report 2025.
[14] Silverman, C., & Appel, C. E. (2024, May). Nuclear Verdicts: An Update on Trends, Causes, and Solutions. U.S. Chamber of Commerce Institute for Legal Reform.
[15] Silverman, C., & Appel, C. E. (2024). Top states for nuclear verdicts analysis. Nuclear Verdicts Report. Institute for Legal Reform.
[16] Silverman, C., & Appel, C. E. (2024). Economic vs. noneconomic damage composition. Nuclear Verdicts Report. Institute for Legal Reform.
[17] Silverman, C., & Appel, C. E. (2024). Anchoring tactics driving nuclear verdicts. Nuclear Verdicts Report. Institute for Legal Reform.
[18] Silverman, C., & Appel, C. E. (2024). Lawsuit advertising impact on verdicts. Nuclear Verdicts Report. Institute for Legal Reform.
[19] PropertyCasualty360. (2025, April 16). Georgia jury awards elderly woman $4.2M for dog attack. https://www.propertycasualty360.com/2025/04/16/georgia-jury-awards-elderly-woman-42m-for-dog-attack/
[20] TransRe. (2024). Medical malpractice verdict analysis. Cited in Institute for Legal Reform Nuclear Verdicts Report.
[21] National Association of Realtors. (2024). Baby boomer real estate ownership analysis. Business Insider.
[22] Harvard Joint Center for Housing Studies. (2024). Baby boomer population decline projections 2025-2045. Business Insider.
[23] Leaf Home & Morning Consult. (2024). Survey of 1,000 baby boomers on home age and maintenance. Business Insider.
[24] Metz, J. (2025). California property tax implications of inheritance. Senior Homeowner Solutions. Business Insider.
[25] Yahoo Finance. (2025). State Farm refused to cover Florida man’s repairs on his Porsche—why the courts are now involved. https://finance.yahoo.com/news/state-farm-refused-cover-florida-095800478.html
[26] Fairweather, D. (2025). Chief Economist commentary on inherited property challenges. Redfin. Business Insider. Boomers are leaving their millennial Children with a huge headache — James Morris Homes
[27] S&P Global Ratings. (2024). Cyber insurance market outlook: Premiums projected to reach US$23 billion by 2026 amid stable industry conditions. Industrial Cyber.
Artificial Intelligence Has Changed the Cyber Threat Landscape. Here Is How You Should Be Thinking About Risk, Coverage, and Governance.
Source: Google Threat Intelligence Group (GTIG), “Adversaries Leverage AI for Vulnerability Exploitation, Augmented Operations, and Initial Access” — May 11, 2026. This memo summarizes key findings and their implications for your organization’s risk profile.
The Big Picture: What Google’s Intelligence Team Found
Google’s threat intelligence team published a landmark report documenting a fundamental shift in how cyberattacks are being carried out: artificial intelligence has become a standard weapon in attackers’ arsenals. The following is what the report found actively occurring:
-
-
• AI is discovering security flaws automatically: For the first time, Google confirmed that a zero-day exploit (a previously unknown vulnerability) was developed using AI. Attackers used it to plan a mass exploitation campaign targeting thousands of organizations simultaneously.
• Malware is now designed to fool your defenses: Russia-linked and other state-sponsored hackers are using AI to write malware that camouflages itself with decoy code, making it harder for traditional security tools to detect. One malware family included 32 repetitive, benign-looking code queries just to appear harmless.
• Attacks are becoming autonomous: A new Android malware called PROMPTSPY operates without human supervision: it navigates your phone’s interface, blocks uninstallation by placing an invisible overlay over the uninstall button, and can be updated remotely even if its infrastructure is identified and blocked.
• Phishing has become surgical: Attackers are using AI to research company org charts, vendor relationships, and individual employee roles before crafting personalized emails. The days of easily spotted mass-spam phishing are giving way to targeted messages that reference real people, real vendors, and real projects.
• Your AI tools are now a target: A criminal group compromised widely-used AI software packages including a popular AI gateway tool, stealing cloud credentials that were then sold to ransomware groups. If your organization uses AI software, those integrations expand your attack surface.
-
Why This Matters for Your Business
-
• The barrier to entry for sophisticated attacks has collapsed: AI has made expert-level hacking accessible to a far broader pool of adversaries. You do not need to be a Fortune 500 company to be in the crosshairs.
• Time-to-impact is compressing: AI automates the steps between initial compromise and ransomware deployment. Incident response windows that used to be measured in days are shrinking.
• No organization is too small to be a supply chain target: Attackers do not always come at you directly. They compromise a software tool you and thousands of others use, gaining access to all of you at once.
• Deepfake impersonation is operational, not hypothetical: AI voice cloning is actively being used to impersonate journalists, executives, and public figures. Business email compromise and wire fraud schemes now have an audio and video dimension.
• Your risk profile has changed even if your operations haven’t: AI has materially increased the frequency and sophistication of attacks against organizations of every size. Coverage and controls that were adequate two years ago may not reflect today’s environment.
-
-
How Insurance Responds: Key Coverage Areas to Review:
-
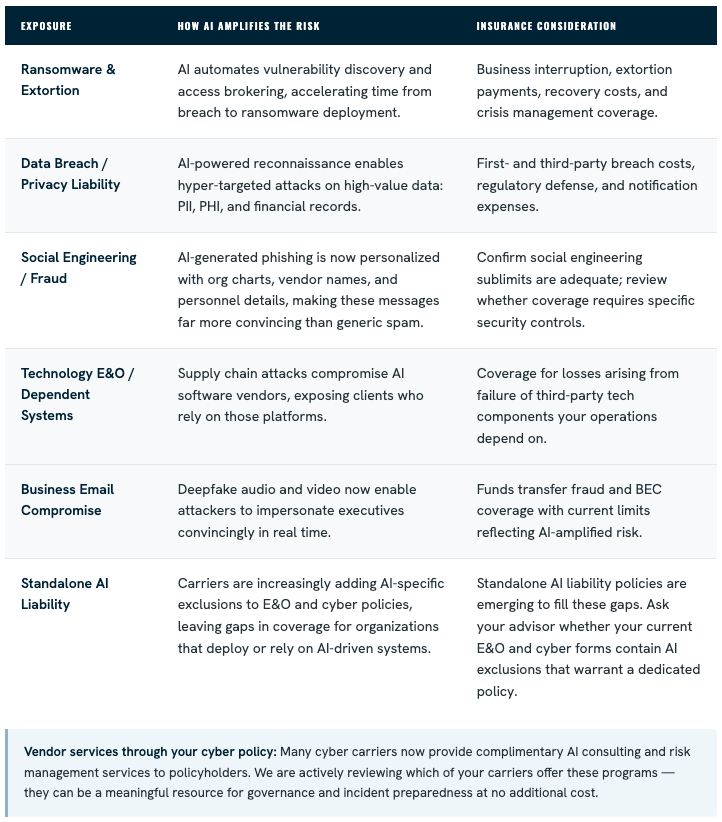
The Regulatory Landscape: What’s Coming and When
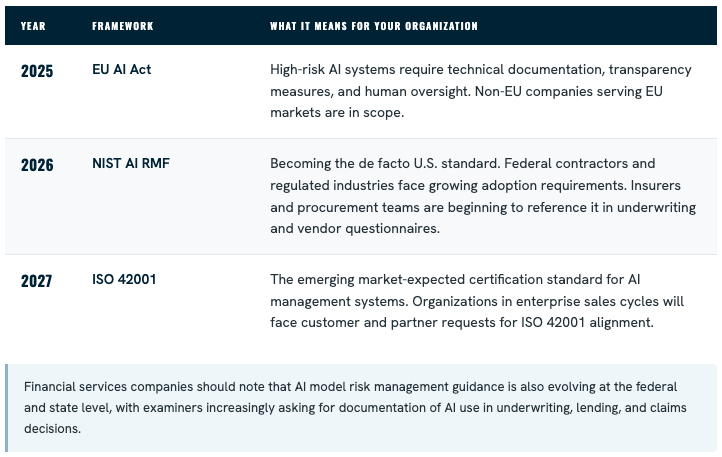
AI governance is shifting from best practice to legal obligation. The regulatory timeline is compressed, and organizations that wait for binding enforcement to arrive will face a harder and more expensive path to compliance. Cyber insurance carriers and enterprise procurement teams are increasingly referencing these frameworks in applications and vendor reviews.
-
-
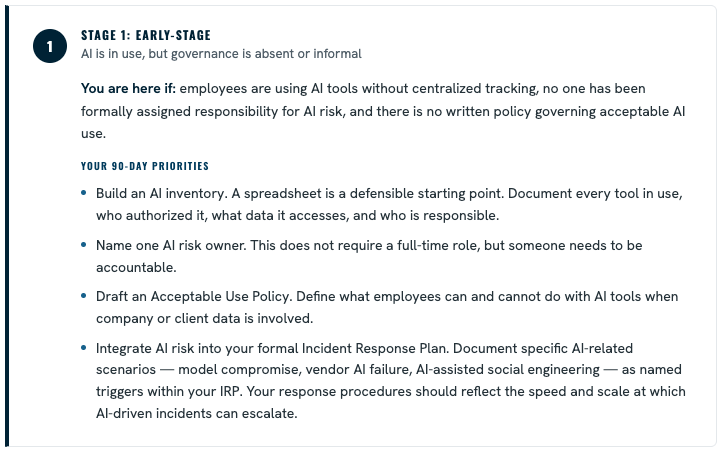
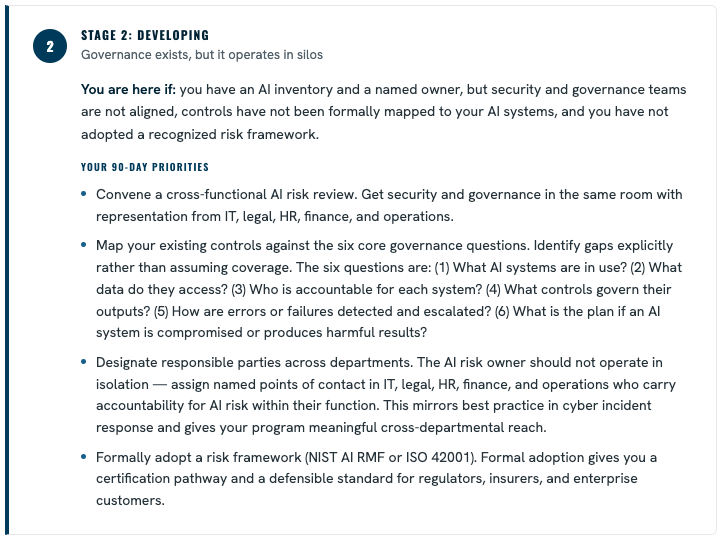
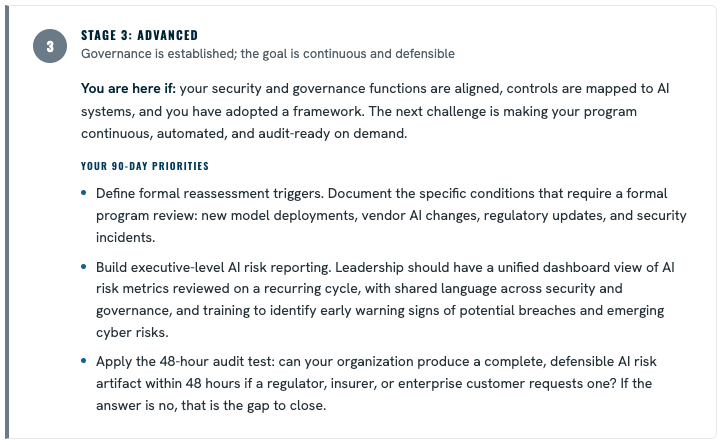
Where Does Your Organization Stand? A 90-Day Roadmap by Maturity
-
-
Not every organization is starting from the same place on AI governance. Identify your current stage below, then focus your next 90 days on the actions listed for that tier.
What We Recommend Discussing with Your Advisor
-
• Audit your AI software footprint: Identify every AI tool, plugin, or third-party integration in use across your organization. Each one is a potential supply chain entry point.
-
• Review ransomware sublimits: Many policies introduced ransomware sublimits in recent years. Confirm those limits still reflect your actual exposure given AI-accelerated attack timelines.
-
• Evaluate social engineering coverage: Verify your policy covers AI-generated phishing and impersonation scenarios, and confirm that coverage does not depend on security controls you may not currently have in place.
-
• Confirm your incident response plan is current: Autonomous malware and faster attack timelines demand a response plan that has been tested within the past year. One written before AI-powered threats became standard is no longer adequate.
-
• Discuss re-underwriting if your AI usage has grown: If your organization has adopted new AI tools since your last renewal, disclose that proactively. It positions you as a more credible risk and prevents coverage disputes after a claim.
Additional Resources
The following resources are recommended by practitioners and referenced by regulators and insurers:
• NIST AI Risk Management Framework (AI RMF) — The primary U.S. federal standard for AI risk governance. Free, framework-based, and increasingly referenced in procurement and insurance. airc.nist.gov • NIST AI RMF Playbook — Practical implementation guidance with mapped actions for each function of the RMF. airc.nist.gov/Docs/2 • ISO 42001 Overview — The international certification standard for AI management systems. Relevant for organizations with enterprise customers or international operations. iso.org • EU AI Act Summary — Plain-language summary of the EU regulatory framework. Relevant for any organization that operates in or sells into European markets. artificialintelligenceact.eu • CISA AI Security Guidance — Cybersecurity and Infrastructure Security Agency guidance on AI security. Practical and security-focused. cisa.gov/ai • Cranium AI Governance Platform — A purpose-built tool for AI inventory management and continuous AI risk monitoring. cranium.ai
-
-
-
News You Can Use: Trends 2021
We’ve seen quite a few things trending in 2021 from the pandemic and we’re here to help you through those transitions. Whether you’re moving, buying a secondary home, undergoing home renovations, have children moving across the country, or thinking of planning that family vacation (finally!), we’re here to help.
Service Line Coverage
Service line coverage is available through some of our homeowner carriers and this is a valuable coverage to help in the event of utility line failure outside of the home’s foundation that leads to the street. If it’s not available on your homeowners policy, your service providers also offer this coverage at a nominal cost per month. If you have any questions, please reach out to discuss.
New purchases
Have there been any new jewelry, regular use vehicles, collector vehicles, fine art or other high valued collectibles purchased over the past year? It may be time to revisit your valuable articles coverage limits and/or auto and collector vehicle policies.
Making Moves
If you’re thinking about moving to or in the process of purchasing a coastal home, there are many things to consider. The risk variables significantly differ when comparing a home that is located on a more inland and/or northern state versus one that is further south and/or along the coast line.
Florida, for example, has its own set of challenges with increased insurance costs due to wind and hurricane exposures, an increased need for flood coverage, increased costs to protect your home against these risks and how investing in home upgrades can greatly benefit you in the long run. The more time that we have to help you prepare for a home closing, move or renovation, the better.
Flood Insurance
Whether you’re home or taking some much-needed time away with family, it’s important to protect what your home and belongings. Flooding can happen anywhere at any time. You do not need to live by a body of water to have this be a threat to your home. A microburst storm that causes rapid surface water accumulation can cause just as much damage as a coastal tidal surge. Flooding concerns are on the rise and now would be a good time to discuss. We can help to provide recommendations on things to consider to protect you home from flooding and hurricanes and to make sure that you have proper coverage if something does happen.

Cyber Protection
Cyber security issues continue to be a challenge. It’s hard to ignore the news headlines listing major cyber breaches and identity theft issues on a regular basis. Whether you’d like to discuss what coverage options are available or what you can do to prevent cyber security breaches from happening in the first place, we’re here to help.
Liability Limits
A lot of our clients are taking steps to update their homes and enhance their living space. Whether you’re thinking of enhancing your backyard patio for entertaining or installing a pool or hot tub, another important factor that you should be considering is your current excess liability limit. There are a lot of reasons to readdress your liability limits and we’re here to help you through that process.
Your Private Client Service team is here to help. If you have any questions, please don’t hesitate to reach out.
2022 Trends in the Insurance and Risk Management Space for Private Client Group
2021 was one for the books for many reasons and we see these trends continuing into 2022. We’re here as a resource to help you navigate through these. We encourage you to read through and reach out with any questions that you may have and to discuss these in more detail specific to your family.
Supply Chain Issues and Labor Shortages
Both are affecting how you should be insuring to value on your policies.
- Are you planning or have you completed a recent renovation or addition? Many are thinking of making updates to their current living space if they haven’t done so already. Let’s discuss to make sure your homeowner policy limits are appropriate so you have adequate protection in the event of a claim. A recent Wall Street Journal article highlights shortfalls that many homeowners faced in the recent Colorado wildfire.
- The labor and material shortages and supply chain issues have caused increased home replacement costs. Asphalt roofing prices are up 9.9%, lumber and wood prices are up 34.2%. They shortages have forced many to make changes in renovation plans and caused delays in estimated project completion dates for construction. We can help to keep tabs on things throughout the renovation or construction process and provide guidance on loss prevention during this increased risk exposure.
Risks are Changing, No Matter Where You Live
Let’s prevent things from happening in the first place with risk management:
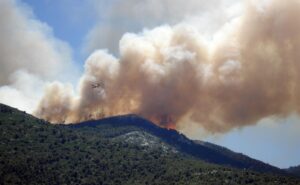
- Wildfire prone area? Let’s discuss fire resistive home components and fuel load mitigation. Markets have been tightening out west because of the historic number of wildfire events and insurance carriers need for adequate rate.
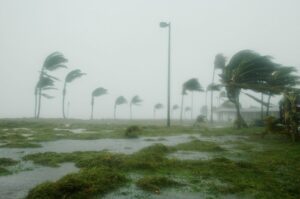
- Hurricane prone area? Let’s discuss your roof construction characteristics, opening protection, and flooding concerns. Florida, in particular, has been experiencing a hardening insurance market. Knowing what your options are and selecting quality coverage is important.
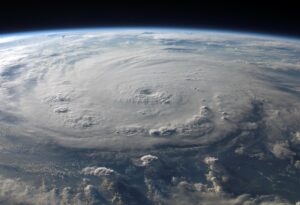
- Severe weather? These weather patterns are becoming the new norm. Hurricane Ida made landfall in Louisiana but didn’t stop there. It caused severe flooding damage to homes all the way up through the Northeast. Make sure you’re taking flood insurance into consideration and how a home was built. We can help you with this early in the house hunt discussion. Making sure that your home is properly elevated can make a big difference in how much you pay in the long run and how ready your home would be in the event of a significant hurricane or flooding event. Texas experienced a historic winter storm with temperatures 40 degrees below average. Whether we’re discussing extreme temperatures, hurricanes or flooding, there are preventative steps that you can take to prepare for events like this and make sure your policies are up to date with robust terms and limits. Let’s make an emergency preparedness plan. Let’s discuss a water leak detection device, a low temperature monitoring system, and flood insurance.
- Water leaks – they can happen to anyone. Whether you’re at home or you’re traveling, this is a trend that we do not see going away anytime soon. However, they can be avoided! As you’re thinking of home improvements over the next year, consider installing a water leak detection shutoff device. This can save you the headache of having to live elsewhere or the inconvenience of repairs being made after a frozen pipe burst or pipe leak. Many carriers offer a credit on their homeowner’s policies once installed and potentially a discount on the product itself to reward you for your risk avoidance efforts.
- Renovations? That means more foot traffic through your home, potentially the use of flammable materials or working with electrical components. Let’s talk about risk prevention and easy steps you can take to safeguard your home while work is underway.
- Cybersecurity concerns have grown exponentially during the pandemic. With individuals working from home and children learning remotely, there is a lot more activity on an individual’s personal network. There are personal cyber protection policy options and also risk management items to consider.
- We are living in a forever litigious society. Let’s discuss your personal risk profile and make adjustments to your umbrella limits, if needed. A recent verdict from a homeowner’s pool is enough reason to consider. If there has been a liquidity event, make sure you update your liability limits.
- Relocations or secondary home purchases. Thinking of moving? So is a large portion of the US population if they haven’t already. Let’s discuss risk and rating factors when looking at new homes as they can vary state to state. There can also be significant credits at play depending on when and how a home was updated and we can help you weigh out some of the pros and cons of making that move from an insurance and risk management perspective.
- Claims: Labor and material shortages and supply chain issues have impacted automobile policy and homeowner claims both from a paid claim amount and delays in the process causing claims to remain open while clients remain out of their homes or without their regular use vehicle. We are here as a resource if something happens. We want to make sure a claim is handled as smoothly as possible and to help you understand the process up front before we submit a claim. The microchip shortage has caused a ripple effect in the auto industry causing shortages in new and used vehicles for purchase, availability of rental vehicles and also automobile parts when repairs are needed after an accident.
- Collectors, diversified. The pandemic has proven to be an opportunistic time for some individuals. Deferred or cancelled vacations left some with funds to focus elsewhere. Have you recently purchased any jewelry? Watches? Wine and Spirits? Collector vehicles? It may be time to readdress.
Please reach out if any of these have struck a chord and we can discuss what changes or action plans we may recommend.
Updated 6/21/22
Cybersecurity Risk Prevention
It seems like every organization in the world has designated a month each year to raise awareness around a common issue, hobby, or interest. October happens to be Bat Appreciation Month, National Popcorn Poppin’ Month, and National Toilet Tank Repair Month to name a few. It is also National Cybersecurity Awareness Month.
For this reason (and also because many of us are spending more time working remotely), we thought it would be a good time to share what we are seeing in the commercial and personal cyber insurance space these days. We also wanted to share some cybersecurity best practices.
Trends We are Seeing:
There has been a sharp rise in cyber-attacks and cyber claims over the past few months as companies have transitioned to work from home environments. Remote work has unfortunately made businesses and non-profit organizations easier targets for hackers as employees are using home internet networks instead of corporate networks that might have stronger security.
Small businesses and non-profits are often easier targets compared to Fortune 500 companies as they do not have the same level of resources for cybersecurity or full time IT staff.
The most common type of claim recently is a ransomware attack, where malicious software infects your network and the hacker demands a ransom payment (usually bitcoin) in exchange for getting the system working again. We have had multiple clients this summer and fall experience ransomware attacks where large ransom payments were demanded and ultimately paid.
Commercial Cyber Insurance:
We understand cybersecurity and cyber insurance can be stressful and confusing topics. Many of our clients regularly ask us what is included in a cyber policy and what is the cost of a policy.
A commercial cyber policy typically starts with a $1 million limit and can cover:
- Liability and defense costs resulting from a data breach
- Cost of notifying customers or employees of a data breach
- Cost of the extortion payment in a ransomware attack
- Cost of working with IT and legal firms to recover from a cyber-attack
- Cost of restoring data and systems wiped in a cyber-attack
- Reimbursement of lost income resulting from cyber related business interruption
- Reimbursement of money stolen through a social engineering attack
- Regulatory fines and penalties
The premium for these policies varies and is based on the type of organization, annual revenues, and sometimes employee count.
Each insurance company partners with various cybersecurity, legal, and PR firms who can assist policyholders in the event of a claim. We have found it is incredibly important to partner with the right insurance company to have the best vendors available to help you respond to an incident.
Personal Cyber Insurance:
On the personal side, companies such as Chubb and PURE offer personal cyber insurance as an enhancement to homeowners policies.
A personal cyber policy typically includes limits of $25,000 to $250,000 and can cover:
- Costs related to extortion attempts and threats to release personal information
- Reimbursement of money stolen out of a bank account without client’s knowledge
- Cost of identity theft restoration
- Cost of cyberbullying services for children
- Cost of working with cybersecurity, legal, and PR firms to respond to cyber or extortion attack
The typical premium runs from $150 to $600 depending on the limits chosen.
Best Practices for Commercial Clients:
Clients also often ask us what steps should they take to protect themselves and their organizations from a cyber-attack.
Here are some best practices we would recommend for businesses and non-profits:
- Regularly meet with your IT firm or IT staff to discuss vulnerabilities and areas in need of improvement
- Keep a running asset inventory of all computers, mobile devices, etc. connected to your network
- Regularly review access rights given to employees for various internal systems and applications
- Remove old employees from applications, systems, and network on a regular basis
- Provide regular cybersecurity training to employees including phishing exercises
- Create formal information security policies and procedures for the organization
- Create incident response and business continuity plans to prepare in the event of a future incident
- Mock test the response and continuity plans so you know how you will respond to an incident
- Utilize Simpson & McCrady and other third party firms (IT, legal, etc.) as part of these exercises
- Back up critical data and systems on a regular basis
- Consider cyber insurance as a way to protect your organization from a future incident
Best Practices for Personal Clients:
Here are some best practices we would recommend for individuals:
- Do not click on links in suspicious emails or on suspicious websites
- Use multiple passwords for different websites, applications, etc.
- Use complex passwords with multiple characters, numbers, and symbols
- Do not use the same password for social media sites and personal financial sites
- Ask banks, financial advisors, etc. to authenticate funds transfer requests by phone
- Store passwords in a secure password manager application
- Regularly change passwords for critical websites and applications such as bank accounts
- Avoid sending sensitive information such as social security or drivers license numbers or dates of birth through email
- Avoid logging on to critical websites and applications in public places through public Wi-Fi
- Utilize two factor authentication for logging on to critical websites and applications
- Freeze your credit with Transunion, Experian, and Equifax to limit identity theft attempts
- Check your credit at least quarterly to monitor fraudulent accounts set up in your name
- Consider personal cyber insurance as a way to protect you and your family from a future incident
This can be a lot to digest if this is the first time addressing these risks. The important thing to remember is taking it one step at a time and consulting with a risk advisor to help you along this journey will help. Please do not hesitate to reach out to us at Simpson & McCrady if you’re interested in discussing the various risk prevention tactics and cyber insurance options available to you as a commercial or personal client.
About the author:
Will Simpson is an Account Executive at Simpson & McCrady. Will works with both personal and commercial clients and has personal expertise in cyber insurance. Prior to joining Simpson & McCrady in 2016, Will was a cyber underwriter handling Fortune 500 accounts for both Swiss Re Insurance and Zurich Insurance in New York City.
Last updated: 10/5/22
Water, water everywhere…
With Pittsburgh being hit with significant rainfall within the last few months, multiple flash flooding events within days of each other, and Washington Boulevard’s repeated closures, it is more evident than ever that flood coverage is an important topic for discussion — no matter where you live.
We want to reach out to our valued Chubb clients to reiterate the importance of contemplating flood coverage and to provide you with some additional resources and information.
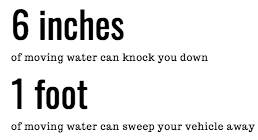
Flood waters do not have to come from a rising river, stream, or lake to be considered a flood event. Surface water can accumulate quickly and it doesn’t take much of a grade change to give that body of water momentum. While it may seem unlikely that flooding would happen in non-coastal areas, statistics indicate otherwise.
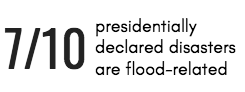
According to Federal Emergency Management Agency, 20% of flood claims happen to properties that are outside high-risk flood zones and floods and flash floods happen in all 50 states. (floodsmart.gov) Pennsylvania, in particular, is one of the top five worst states for flood.
Water can enter a home in many ways. Understanding how it is entering the home helps to determine how your home policy will and will not respond and how adding a flood policy could help to avoid out of pocket expenses.
With Chubb, if the water is backing up through the sewers and drains within your home, your homeowners policy would cover the damage expenses. If the water entering your home is caused by surface water, a flood policy would be needed to cover the loss.* If your home has water seeping through the seams of the floor and wall, your homeowner policy would not cover this and it would be a good time to discuss alternative risk management tactics and waterproofing your basement.
Every scenario is unique and your dedicated Private Client Services Account Manager can be a valuable first call in the event of water damage to figure out what needs to be done both from a claims handling perspective and initiating the remediation process with one of our trusted restoration companies.
Until recently, flood insurance was only available through the federal government via the NFIP. Chubb provides broader coverage than what you could get through the NFIP as a benefit for having your home and wind coverage through Chubb. They provide a brief overview of some of the benefits in this video and some of the highlights are also listed here.
With Chubb Flood, you would have these valuable benefits:
- Admitted paper, Chubb claims, & one adjuster
- Broader coverage including Replacement Cost versus Actual Cash Value
- Capacity – up to $15 million (building & contents)
- Definition of Flood: Chubb defines a flood to include loss confined to insured property
- Broader basement coverage than the NFIP:
- Contents up to $15,000 i.e. furniture, rugs, home theater systems, pool tables, and other contents typically found in a finished basement. This limit can be increased for an additional premium. (NFIP restricts coverage to specific items including washing machines, dryers, freezers, etc.)
- Real Property up to $30,000 for built in finished basement characteristics such as cabinetry, wet bars, saunas, etc. This limit can be increased for an additional premium. (NFIP restricts coverage to specific real property such as central a/c, furnaces, stairs, water softeners, etc.)
- Additional Living Expense includes $7,500 with limits up to 50% of the flood building limit available. (NFIP provides zero Additional Living Expense coverage)
- Rebuilding to code can be bought up to 25% of the flood building limit
If you are interested in learning more about a flood policy or determining if you are eligible for the Chubb flood product, please reach out to your dedicated Account Manager to discuss your flood concerns and see if the Chubb Flood product makes sense for your home.
Aside from insurance coverage, there are risk mitigation and risk avoidance tactics to consider that can lessen the severity of a loss before, during, or after damage is done. Chubb provides great tips and recommendations to keep you and your possessions safe. In addition to these recommendations, we collaborated with Kevin Young from Restoration Management Services to provide the following additional preventative measures that can be taken to avoid or reduce the risk of a water loss:
- Make sure downspouts drain away from the house and that the downspout drains are not clogged, which can allow for backups.
- Ensure that gutters are clean and free of debris and flowing properly. If not, this can allow for the gutters to overflow and deposit additional water to the foundation.
- Make sure that landscaping and soil is sloped away from the foundation. This will allow for water to drain away from the home.
- Installation of a sump pump will move water out of the system to the exterior of the house.
*Note that this is a general coverage overview and whether or not coverage would apply will depend on the specifics of the claim submitted and the terms and conditions of your in force policy at the time of loss.
About the Author:
Jessica Stoecklein DeFelice is the Director of Private Client Services at Simpson | McCrady and has been assisting high net worth clientele and providing education on their personal insurance and risk management needs since 2006.
Statistic Sources:
https://www2.chubb.com/us-en/individuals-families/water
https://www.ready.gov/floods
Hurricane Preparedness – Storm Florence and Storm Olivia
To our valued clients,
In preparation for Storm Florence and Storm Olivia, please check out the following helpful tips on hurricane preparedness and how to minimize damage:
10 Steps to Prepare for a Hurricane
10 Steps to Prepare Your Boat for a Hurricane
8 Ways to Minimize Damage After a Hurricane
Not finding what you’re looking for? Please reach out to our Private Client Services team and we would be happy to address your risk management and claims handling concerns as we are always here as your first call in the event that something happens.
Chubb has additional claims resources in case there is a need.
2023 Personal Insurance and Risk Management Trends in Private Client Services
Following last year’s trends, there are a lot of factors that continue to affect the insurance market volatility. Markets have tightened and rates have remained elevated across the board early in 2023 and many consider this the hardest market in a generation. The good news is that as an independent agent, we are here to keep you informed and to help make adjustments, where needed. Know that we’re keeping an eye on things for you.
Home Inflation
It’s important to make sure that we stay up to date with the value of your home. Home construction materials have climbed 33.9% since the start of the pandemic and trade services are up 27%. Inflation has affected claim payouts due to increased cost in goods and labor and, in turn, has affected home and auto insurance rates.
Have you completed renovations or are you planning on starting renovations in the next few months? Let’s discuss to make sure you have full coverage and we can provide loss prevention recommendations to make sure you’re home is safe during this increased risk exposure period.
Water Damage
Water damage stemming from plumbing leaks continues to be on the rise displacing homeowners while renovations are being completed. Once you suffer a water loss, you are 2x as likely to suffer a second one. Consider a water leak detection shutoff device to prevent a significant loss. Let’s discuss your options and the premium benefits that come with this proactive step in loss prevention.
Weather and Climate Impacts
Weather and climate disasters are not just happening in FL and CA. It’s affecting everyone. 2022 experienced the 3rd highest number of billion-dollar disasters and it’s not on track to slow down any time soon.
- Flood insurance is never automatically in a homeowners policy and a flooding event can happen anywhere. Let’s discuss if you have concerns.
- Tornado season is off to an unfortunate strong start this year.
- High-impact snowstorms have hit record highs in many areas.
Reinsurance
It’s important to remember that many insurance companies operate using reinsurance. Simply put, reinsurance is insurance for insurance companies. Without it, insurance companies would be forced to be far more conservative in the policies they write. An uptick in the number and severity of natural disasters causes reinsurers to charge insurance companies higher rates. These costs, over time, are passed along to residents in the form of higher yearly premiums. Some estimate that property-catastrophe reinsurance prices rose 30.1% in 2023 following a 14.8% increase in 2022.
Florida
Hurricane Ian took a major blow to Florida at the end of last year. It not only caused a significant amount of damage but also put further strain on the already tough insurance market.
If you’re thinking of purchasing a home in Florida, it is so important to discuss with your insurance agent ahead of putting an offer on the table. We can help to arm you with the right questions to ask your realtor and the seller to make sure you’re making financially sound decisions. There are many components that can impact the amount you will have to pay for insurance premium. Some things to consider:
- Is the home new or was it built prior to the current FL building codes? This can make a large impact on the premium. A wind mitigation form will give all of this information in detail for us to help you review.
- Is the home located in a high flood hazard area? This will determine if your lender will require you to carry flood insurance and also what we may make as far as recommendations and also how much it would cost to cover this type of loss from a microburst, storm surge or other surface water event. An elevation certificate will give you the information needed to review and we can help to explain in more detail.
Ian was a tell tale story about the importance of flood insurance and the need for more homeowners to have this coverage in place. It doesn’t take a hurricane to flood parts of Florida as some of the recent storms have shown us. It is a type of loss that is never automatically covered by a homeowners policy. You always have to purchase this separately and, depending on the location, the flood zone that it is in, and if it’s positively elevated or not or even how elevated it is, these can all make a difference in the annual cost to protect your home.
California
California continues to be a tough state from an insurance perspective. Given some of the issues plaguing the California insurance market right now, this will be helpful context as you review your policies come renewal. If you’re buying a home in California, please make sure to include your insurance agent in the discussion before making an offer. It can save you time, energy and money in the long run if your agent can help to arm you with the right questions to ask the real estate agent and seller before making an offer.
There are two main areas that are impacting the California insurance market:
- The frequency and extent of natural disasters in California
It’s no surprise that natural disasters make insurance in the Golden State difficult for residents, agents, and carriers alike. In fact, California experiences more natural disasters—wildfires, atmospheric river flooding, earthquakes, drought, and mudslides—than any other state.
Analysts estimate the winter storms of December 2022 and January 2023 alone account for $5 billion to $7 billion in economic losses and another $500 million to $1.5 billion in insured losses.
Making sure your home is ready to weather the storm is important. Work on an annual home maintenance plan to keep everything in tip top shape and your home will be more resilient for it.
- The strict regulations of California and the challenging economic climate
In addition to natural disasters, California insurers must receive approval from the state insurance department before adjusting their prices. While this is positive for consumers, some insurers are paying more in claims than they’re taking in — and have been for years.
Although regulators are easing up a little now that the pandemic is in the rearview mirror, the approved increases are hardly enough to keep up with the challenging economic climate.
In response, insurers are reducing their operating expenses (i.e., closing offices) and implementing stricter underwriting requirements. Some well-known carriers are halting their advertising efforts in the state or choosing to exit the California market altogether.
With these topics in mind, let’s talk about how to prevent losses from happening in the first place. This will help you in the long run both from a loss prevention standpoint but also for insurability.
Emerging Trends
Are you concerned about cybercriminal activity or do you own an e-bike? Let’s discuss. Many insurance companies are working to find solutions for these emerging exposures and we want to make sure they’re listed so you have coverage.
Collectors continue to diversify their portfolios and many are expecting these emerging markets to grow exponentially.
- Pre-owned luxury watch segment is expected to grow 75% by 2030. Make sure they are added to a valuable articles policy so you are not subject to sublimits or a deductible on your home policy.
- Luxury handbag collections are on the rise over the past two years.
- Sports memorabilia
- Fine wine and spirits collecting is on the rise as a result of the pandemic.
Auto Insurance
Inflation has also impacted the auto industry. The average price of a new car is up 17% from 2020. The cost of labor and materials has impacted claim payouts and the amount of time that a vehicle is in the shop. Make sure that you have agreed value, original equipment manufacturer parts, and adequate temporary rental vehicle coverage and limits, where possible.
Supply challenges have made it difficult for repairs and also for replacement vehicles making it a longer process than pre-pandemic.
Hyundai and Kia vehicle owners are going to find it harder to place coverage due to the rise in vehicle thefts over the last year that have caused some insurance companies to no longer offer coverage for certain models. Here are some helpful tips on safeguarding these vehicles.
Purchasing a vehicle? Please call us! We need to make sure we add the vehicle to your policy and can get a temporary ID card over to you until the insurance policy paperwork prints. Not all dealerships call us and we want to make sure you are covered!
Liability concerns
Every year, the losses that we see continue to grow in size and frequency where they pierce the excess liability layer. There are multiple factors that we see at play such as the litigious society that we live in, distracted driving, and dog bite claims, to name a few. Making sure you have the appropriate liability limit is so important to protect your net worth, your lifestyle and your reputation.
If you have personal employees such as a nanny, chef, chauffeur, etc., it is important to understand what your increased exposures are and what you can do to help protect you and your employees with Employment Practices Liability and Workers Compensation coverage.
Please don’t hesitate to reach out if you have any questions or would like to discuss these topics in more detail.
Heat Wave – Heat Illness Prevention
Whether your a personal or business client, we’re here to provide risk management tools to help keep you, your family, and colleagues safe.
Heat-related illnesses can be severe, but they are preventable with the right strategies. Ensure that all individuals stay hydrated by drinking plenty of water throughout the day and taking regular breaks in shaded or air-conditioned areas. Encourage the use of lightweight, light-colored, and loose-fitting clothing to help maintain a cooler body temperature.
Additionally, be vigilant for signs of heat exhaustion and heat stroke, such as dizziness, nausea, excessive sweating, and confusion. Implement a buddy system to monitor each other’s well-being, and never leave children or pets in parked vehicles. Reference the attached resources and posters for a more in depth review of heat illness preparedness and prevention strategies.
By taking these proactive measures, we can significantly reduce the risk of heat-related illnesses and ensure a safe and enjoyable summer for everyone.
We’ve pulled together resources for you with helpful tips and resources:
- Tips to beat the heat
- Heat Illness prevention at work
- OSHA Heat Hazard Alerts
- Who, what, when, where and why behind heat alerts
Any questions, please reach out!
Navigating the High-Net-Worth Landscape in 2024: A Comprehensive Approach to Personal Insurance and Risk Management in a Dynamic Environment
Last year posed many challenges in our market and many of those factors continue to flow into 2024. While there are signs of light at the end of the tunnel for this hard market, we still see challenges ahead before we make our way out.
This review outlines what we’re seeing in our market space, so you have a more comprehensive understanding of each trend. We’ll also equip you with actionable steps to take to optimize your insurance programs and mitigate potential risks. We will make sure to cover the following market impact topics:
• Social inflation and nuclear jury verdicts
• Climate change and catastrophic weather events across the US and the rise in reinsurance costs
• Non-weather water-related plumbing losses
• The increasing cost of labor and building materials and continued supply chain issues
• A shift in how our clients are spending their money including increased investments in home renovations and additions and diversifying collectible assets such as jewelry, fine art, collectibles, and wine and spirits
• Check washing and what to do about it.
Out of all of this, it is important to highlight the growing value of comprehensive risk management strategies for high-net-worth individuals. With increasing wealth comes a greater need for protection against potential risks and liabilities. We are here to offer professional advice to identify and mitigate potential risks and offer tailored insurance policies to address these concerns.
Exposure: Nuclear Jury Verdicts
In a recent wealth report conducted by Chubb, 92% of those surveyed are concerned about the size of a verdict against them if they were a defendant in a liability case which can have profound implications for high-net-worth individuals yet only 36% have umbrella or excess liability coverage. Tailoring liability coverage to address potential legal ramifications is crucial in mitigating this risk.
What to do:
An excess liability or umbrella policy limit is meant to adjust as your lifestyle changes. Liability limits should be reviewed frequently to make sure that an adequate limit is in place. This is a crucial risk transfer tool that can help to protect your net worth and future earnings. The cost is generally nominal for what you get in return. Given the increase in nuclear jury verdicts, now is the time to review.
If you serve on any not-for-profit boards or host events at your property, let’s discuss to make sure proper insurance is in place and we can discuss best risk management practices in these scenarios.
Exposure: Climate Change and the Rise of Reinsurance Costs
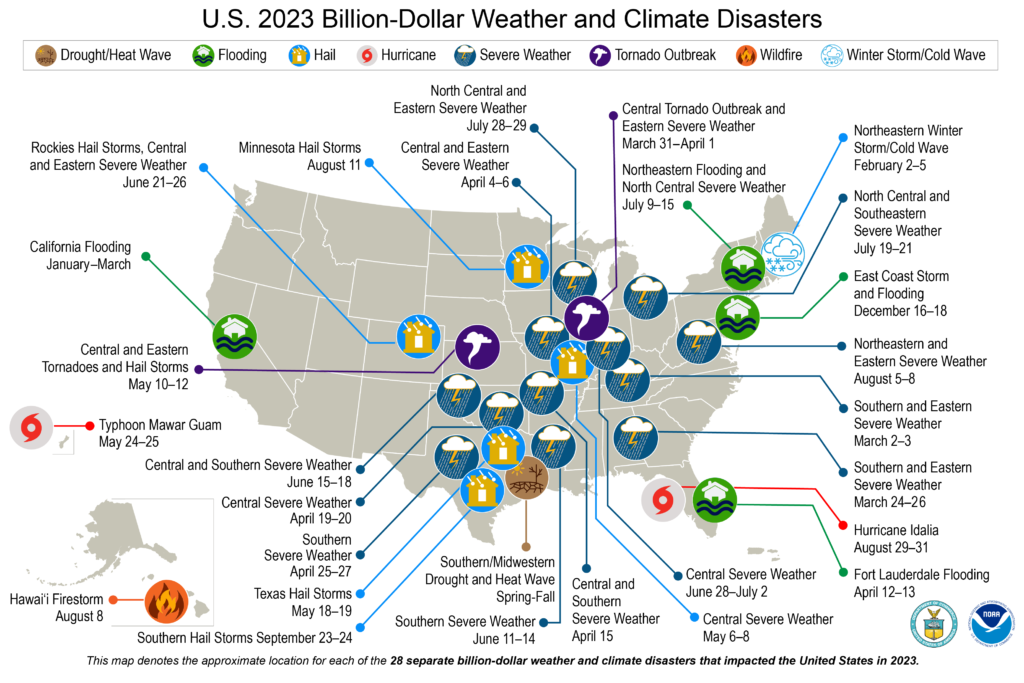
High-net-worth individuals are not immune to the increasing frequency and severity of catastrophic weather events. From wildfires to severe weather, these events pose a significant threat to property and assets. Understanding regional risks and tailoring insurance coverage accordingly is vital. It’s not just about hurricanes along the coast or wildfires in California. Tornadoes are touching down in areas that they historically have not, where it rains, it can flood, and wildfires are happening across the country.
These catastrophic events are impacting the reinsurance market causing higher premiums which, in turn, impact the need for rate for the insurers.
What to do:
Make sure you’re leveraging the rest of your personal insurance policies with one carrier to see if you can obtain more advantageous terms and take proactive measures to make your homes more resilient:
For wildfire:
Have an annual contract with landscapers and arborists to make sure that trees are trimmed back from your home and that your property is well groomed from dry native brush. Keep combustible materials away from the structures. For those in extreme high brush areas, there are many additional proactive measures that we can address so please give us a call to have a more in-depth discussion.
For hurricane prone areas:
If you don’t have hurricane shutters or hurricane impact rated windows, doors, and garage doors, consider these updates as they can make your home more hurricane resilient but also provide credits on your home policy with wind coverage or open additional coverage opportunities. If it’s time for a roof replacement, talk to your advisor and contractor about what it would take to bring the roof up to code and what new features are available.
If you have a lender on your home and you have homes elsewhere in lesser catastrophic prone areas, discuss what your lending options are. If it fits within your financial plan, paying off the loan on your coastal property can have its advantages if it makes sense to self-insure the wind and/or flood exposures. These should be discussed in detail as not having coverage for these exposures should there be a hurricane and significant damage to your property could result in significant out of pocket expenses but can provide premium savings on your insurance portfolio.
Severe convective storms:
These are happening across the country and causing wind and water damage. Flooding can happen anywhere, and you do not need to be in a high flood zone to experience severe water damage to your home. If construction and/or developments have been built around your home recently or there is a lot of concrete near your home, water can accumulate quickly with nowhere to go.
What to do:
Review your flood insurance options. This is not automatically covered by your homeowners policy. It can either be added as an endorsement or written as a separate policy.
Exposure: Non-Weather Water-Related Home Losses
Water damage from non-weather-related incidents, such as a leaking pipe, a frozen burst pipe or appliance malfunctions, has become a prevalent trend for homeowners, including high-net-worth individuals. This type of water damage ranks as the second most prevalent cause of insurance claims. These incidents can result in substantial financial losses pushing clients out of their homes for extended periods of time while repairs and renovations are completed.
What to do:
We strongly recommend installation of a water leak detection shutoff device. This device is installed at the main plumbing valve in your home and/or guest house and monitors the flow of water coming into the building. If it notices an abnormal flow of water that would suggest a slow leak or a burst pipe, it shuts off the main plumbing supply line and sends an alert to your phone so you can locate the cause of the issue and alert a plumber that a repair or review is needed. By shutting off the water, it can give you peace of mind while you are on vacation or out for dinner and prevent severe water damage where you would have to move out of your home while repairs are being made. Unplanned renovations can seem like a whole other full-time job and can be very disruptive to your regular day-to-day and preventing this is priceless.
If you think you have a loss, please call us so we can discuss it. Accidents happen and we can help to expedite the claims handling process if it needs to be turned in and talk to you about next steps on immediate action items and what vendors to consider if you’re unsure who to call first.
Exposure: Underinsurance Caused by Inflation, Cost of Labor, and Supply Chain Issues for Building Materials
Inflation, coupled with escalating costs of labor and building materials, directly impacts property replacement values and can leave clients underinsured, in some cases, in the cost of repairs if a claim occurs, and the time needed to make those repairs. In addition, a home under construction faces increased risks that should be addressed including increased liability exposures with more foot traffic on your property and a higher likelihood of loss while contractors are updating plumbing or using flammable materials.
What to do:
If you are thinking about or recently completed renovations or an addition to your home, it is important to ensure your coverage adequately reflects the current replacement cost to avoid underinsurance. Open communication with your advisor can aid in maintaining accurate coverage. Talking with your advisor about renovations before they happen can also better prepare you for the increase in exposures and ensure that you’re fully covered while the work is being completed. Insurance contracts have varying language addressing undisclosed renovations and how that may impact a payout should there be a loss.
If you’re seeing an increase in premium from increased coverage limits and rate increases, consider higher deductibles if you have a higher tolerance for self-insurance on the smaller losses. Let the insurance policies help to protect you from more severe, large losses that could be a financial burden.
Exposure: Diversification of collectible assets without updates to valuable article policies
We are seeing a shift in how our clients, including those with a high net worth, are spending their money and we are seeing many diversifying their collectible assets such as jewelry, fine art, collectibles, and wine and spirits. All homeowner policies have a cap and limitation on higher valued items such as jewelry, firearms, and other valuable articles and they are also subject to the homeowners deductible.
What to do:
If you’ve made sales and/or purchases, please discuss with your advisor to make sure your policy is up to date. Adding or adjusting a valuable articles policy to your specific needs is a relatively quick adjustment and can be done at any time during the policy period on a prorated basis.
Make sure your appraisals are up to date. If your jewelry, fine art, or other collectibles haven’t been reviewed in the last five years, it may be overdue. If increased values are warranted, we can send the appraisals over to the company to increase.
Exposure: Check washing
We are seeing an increased number of check washing incidents. What do we mean by check washing? It’s when a thief steals your written check from the mail, washes the payee and, also, possibly, the dollar amount on the completed check and changes it to be written out to someone else aside from who it was intended for. You find out because you checked your bank account and find that it was deposited but went to the wrong person.
What to do:
Here are a few tips on how to avoid this:
• Pay your bills online.
• Check washing and what we need to do about it.
• Don’t leave mail in your mailbox; drop it off directly at the post office or place it in your mailbox right before your mail person comes.
• Use a blue or black non-erasable gel pen as these may have ink that makes it harder for the thief to wash out and replace.
• Check your bank account frequently for suspicious or fraudulent withdrawals.
• Contact your bank immediately.
Summary:
All of these exposures have impacted the insurance industry by constricting capacity, causing rate inadequacy for the insurance carriers and stricter guidelines on when, where, and how they are offering terms. As a high-net-worth individual, It is paramount now more than ever to have a knowledgeable advisor helping you navigate through all of this and to adjust where necessary. If you have questions on any of these and want to talk about anything in more detail, let’s chat! We love hearing from our clients and can make necessary adjustments, where needed.
News You Can Use: Liability Limit Review
Where will the money come from?
If you are sued, where will the money come from to pay for your defense and indemnify another party if you are found to be legally responsible? Most would say, “This is what I buy insurance for.” However, when was the last time you reviewed your liability coverage? Have your liability limits kept up with your net worth? If a lawsuit award exceeded your liability limits, which assets would you liquidate first?
The number of multi-million dollar lawsuits has risen dramatically over the past decade. Listed below are just a few potential scenarios to consider.
Automobile Liability:
Insured vehicle slides on ice and crashes into another car. Driver of other vehicle, single father, suffers head trauma and permanent impairment of his cognitive functions. He will require lifelong assistance for himself and to raise his young daughter.
Homeowners/Personal Liability:
You invite your friends over for dinner. While playing in the yard, your dog bites their daughter in the face. The bite creates the need for multiple surgeries and results in permanent damage to the child’s eye.
Watercraft Liability:
Insured’s son is operating a ski boat and accidentally strikes a young man in the water. As a result of the accident, the claimant loses his arm and requires significant rehabilitation.
Homeowners Liability:
Insured is a member of the homeowner’s association board of directors in a prominent community. Late one night several teens decide to go for a late night swim. One of the kids unknowingly dives head first into the shallow end of the pool, causing permanent damage to their spinal cord. The board is sued for failure to properly supervise and secure the community property. Initial demands are more than the limit on the board’s insurance policy. Board members are sued individually.
Recreational Vehicle Liability:
Your kids invite friends over to try out your new recreational vehicle (ATV, Golf Cart, Dirt Bike…). While driving a little too fast down a hill and around a bend, the vehicle flips and lands on one of the guests. The accident results in multiple bone fractures and potential brain damage.
These are just a few examples of scenarios where individuals are thankful to have adequate liability protection to shift the financial burden from themselves to the insurance carrier. Making sure that you have an adequate liability limit is something that should be reviewed on a regular basis to make sure you have sufficient protection. In a recent study, 10% of high net worth individuals surveyed lacked expanded liability coverage entirely and 74% of the respondents did have liability insurance but may not carry high enough.1
In a separate study among households with $5,000,000 or more in investable assets, half believe the highest amount of damages they could be liable for is less than $5,000,000. However, awards for lawsuits involving serious injury can equal many times that amount.
How much liability protection do you need? To help determine an adequate limit for your personal liability, consider the following questions:
What is your net worth?
What is your future earnings potential?
How many residences do you own?
Do you rent out a residence you own?
How often do you entertain others at your residence?
Does your residence have a pool?
Do you own any pets?
Do you have any teenage drivers in your household?
Do you or your children use social media on a regular basis?
What is your reputation worth?
Do you own a watercraft or recreational vehicles?
Do you sit on any boards (not for profit or for profit)?
Do you participate in any other volunteer activities?
Do you utilize LLCs or Trusts with respect to ownership of property, vehicles…?
Ultimately, the amount of liability coverage you choose depends on your individual risk profile and risk tolerance. The limit you select should adequately reflect your overall financial situation. It is human nature to feel like certain events will never happen to you but why risk all you have worked for when you have the ability to protect your personal assets and family with additional liability protection. Please contact our office if you have any questions or would like to review your personal situation and current liability coverage.
Take care and be well,
Your Private Client Services Team
1. Chubb.com
What to Know About Cybersecurity
It seems like every organization in the world has designated a month each year to raise awareness around a common issue, hobby, or interest. October happens to be Bat Appreciation Month, National Popcorn Poppin’ Month, and National Toilet Tank Repair Month to name a few. It is also National Cybersecurity Awareness Month.
For this reason (and also because many of us are spending more time working remotely), we thought it would be a good time to share what we are seeing in the commercial and personal cyber insurance space these days. We also wanted to share some cybersecurity best practices.
Trends We are Seeing:
There has been a sharp rise in cyber-attacks and cyber claims over the past few months as companies have transitioned to work from home environments. Remote work has unfortunately made businesses and non-profit organizations easier targets for hackers as employees are using home internet networks instead of corporate networks that might have stronger security.
Small businesses and non-profits are often easier targets compared to Fortune 500 companies as they do not have the same level of resources for cybersecurity or full time IT staff.
The most common type of claim recently is a ransomware attack, where malicious software infects your network and the hacker demands a ransom payment (usually bitcoin) in exchange for getting the system working again. We have had multiple clients this summer and fall experience ransomware attacks where large ransom payments were demanded and ultimately paid.
Commercial Cyber Insurance:
We understand cybersecurity and cyber insurance can be stressful and confusing topics. Many of our clients regularly ask us what is included in a cyber policy and what is the cost of a policy.
A commercial cyber policy typically starts with a $1 million limit and can cover:
- Liability and defense costs resulting from a data breach
- Cost of notifying customers or employees of a data breach
- Cost of the extortion payment in a ransomware attack
- Cost of working with IT and legal firms to recover from a cyber-attack
- Cost of restoring data and systems wiped in a cyber-attack
- Reimbursement of lost income resulting from cyber related business interruption
- Reimbursement of money stolen through a social engineering attack
- Regulatory fines and penalties
The premium for these policies varies and is based on the type of organization, annual revenues, and sometimes employee count.
Each insurance company partners with various cybersecurity, legal, and PR firms who can assist policyholders in the event of a claim. We have found it is incredibly important to partner with the right insurance company to have the best vendors available to help you respond to an incident.
Personal Cyber Insurance:
On the personal side, companies such as Chubb and PURE offer personal cyber insurance as an enhancement to homeowners policies.
A personal cyber policy typically includes limits of $25,000 to $250,000 and can cover:
- Costs related to extortion attempts and threats to release personal information
- Reimbursement of money stolen out of a bank account without client’s knowledge
- Cost of identity theft restoration
- Cost of cyberbullying services for children
- Cost of working with cybersecurity, legal, and PR firms to respond to cyber or extortion attack
The typical premium runs from $150 to $600 depending on the limits chosen.
Best Practices for Commercial Clients:
Clients also often ask us what steps should they take to protect themselves and their organizations from a cyber-attack.
Here are some best practices we would recommend for businesses and non-profits:
- Regularly meet with your IT firm or IT staff to discuss vulnerabilities and areas in need of improvement
- Keep a running asset inventory of all computers, mobile devices, etc. connected to your network
- Regularly review access rights given to employees for various internal systems and applications
- Remove old employees from applications, systems, and network on a regular basis
- Provide regular cybersecurity training to employees including phishing exercises
- Create formal information security policies and procedures for the organization
- Create incident response and business continuity plans to prepare in the event of a future incident
- Mock test the response and continuity plans so you know how you will respond to an incident
- Utilize Simpson & McCrady and other third party firms (IT, legal, etc.) as part of these exercises
- Back up critical data and systems on a regular basis
- Consider cyber insurance as a way to protect your organization from a future incident
Best Practices for Personal Clients:
Here are some best practices we would recommend for individuals:
- Do not click on links in suspicious emails or on suspicious websites
- Use multiple passwords for different websites, applications, etc.
- Use complex passwords with multiple characters, numbers, and symbols
- Do not use the same password for social media sites and personal financial sites
- Store passwords in a secure password manager application
- Regularly change passwords for critical websites and applications such as bank accounts
- Avoid logging on to critical websites and applications in public places through public Wi-Fi
- Utilize two factor authentication for logging on to critical websites and applications
- Avoid sending sensitive information such as social security numbers through email
- Freeze your credit with Transunion, Experian, and Equifax to limit identity theft attempts
- Check your credit at least quarterly to monitor fraudulent accounts set up in your name
- Ask banks, financial advisors, etc. to authenticate funds transfer requests by phone
- Consider personal cyber insurance as a way to protect you and your family from a future incident
This can be a lot for one to digest if this is the first time addressing these risks. The important thing to remember is taking it one step at a time and consulting with a risk advisor to help you along this journey will help. Please do not hesitate to reach out to us at Simpson & McCrady if you’re interested in discussing the various cyber insurance options available to you as a commercial or personal client.
About the author:
Will Simpson is an Account Executive at Simpson & McCrady. Will works with both personal and commercial clients and has personal expertise in cyber insurance. Prior to joining Simpson & McCrady in 2016, Will was a cyber underwriter handling Fortune 500 accounts for both Swiss Re Insurance and Zurich Insurance in New York City.
Buying Art?
Great article on what to consider when purchasing fine art. #protectingtomorrowtoday#fineart#riskmanagement
Your Guide to The Costs of Flood Damage
Are you concerned about heavy rainfall or hurricanes in your town? No matter what size of home you live in the damage from an unexpected flood can be overwhelming. Below are three scenarios that can help you see the benefits of a Flood Coverage policy.
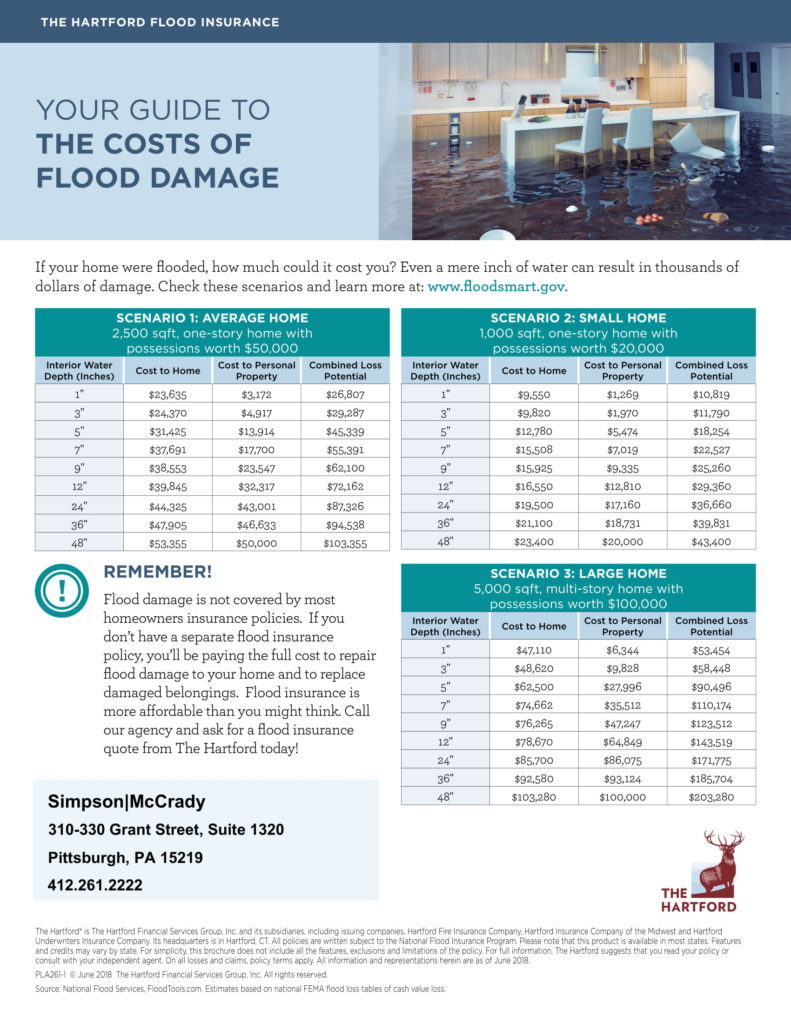
Having flood insurance can get you back on track after a disaster, and back to doing the things you love. Contact us to speak with a trusted advisor.
A Generation at Risk? | Chubb
A comprehensive white paper on navigating the risks of being a young professional in the 21st century.
Your Public Life | Chubb
In a digital world of social media and online transactions, how do you protect your private information?
Art During Hurricanes- Securing Your Possesions
When hurricanes occur in cities and towns, the damage of high winds, flooding and salt-water waves, can wreak havoc on your art.
The Ultimate Backyard BBQ Wine Paring Cheat Sheet
Summertime is perfect for grilling and a nice glass of wine. This cheat sheet will help you create the perfect pair!
Heating and cooling your home for less
Are you looking to save on energy costs with your home? Here are some great recommendations from the FTC…
Flood Coverage, Food Deliveries, Identity Theft, and Cyber Protection
We are helping clients on a daily basis address risks…
At Home:
Your homeowners’ policy, although valuable protection against the majority of situations, does not automatically cover flood damage to your home. Part of our responsibility to you is to help you select the proper protection for your homes and a flood policy or a flood endorsement may be the answer for you.

Just one inch of water in an average-sized home can cause more than $25,000 in damage

Flooding can happen anywhere, not just in designated “high-risk” flood zones. More than 25% of flood insurance claims come from outside the high-risk flood area.

Federal disaster assistance is not available for most flood events and is typically given in the form of an interest-bearing loan
We are here to weather the storms together. Please reach out to your dedicated Account Manager to discuss flood coverage in further detail. In the interim, check out these tips on how to be better prepared for a flood in your area.
In Your Car:
Are you or your kids delivering food or medical supplies for local restaurants and businesses? Are you using your personal vehicles for a fee with ride sharing, a ride sharing program, or personal vehicle sharing? Did you know that most personal auto policies do not cover your vehicle while it’s being used for these purposes?
Some of our carriers have loosened these guidelines during the pandemic but are on a case by case basis and the changes are not indefinite.
If this is something that is taking place in your household, please reach out to your dedicated Account Manager to discuss so we can check your auto policy and make any necessary changes, if needed, so you and your family are properly protected.
Virtually:
With so many of us working from home and children online for school work, we are all at a higher risk of identity theft or a cyber-attack. There are proactive things that you can do to protect your identity and financial assets but also coverage options to help to protect yourself from events like these. Please reach out to discuss if you’re not sure what you have in place or what your options are. We can provide coverage options and additional risk mitigation tips to protect your assets and your home network.
We may not be meeting with you in person but we’re all here for you! We’re all feeling the pains of missing vacations and not celebrating momentous occasions but we’re finding creative ways to smile and make the most of things. Keep up to date with our team and what we’re up to by following us on Facebook or see what trends we’re seeing in the marketplace on LinkedIn. Stay connected. We’d love to hear from you!
Take care, stay safe, and be well,
Your Private Client Services Team
Teen Driver Safety
Getting teenage drivers through the first 100 days after receiving their drivers license…
Night Driving – DriveItHOME
Almost 16% of teen driving fatalities happen between 9PM and midnight – here are ways to protect your teen.
Midcentury Décor: Midcentury Furniture and Artwork
Looking to refresh your space? Midcentury decor is making a resurgence, check out how you can get started…
Coping With Art’s ‘Oops!’ Factor
What if your new, $500,000 piece of contemporary art is made of candy, and your dog eats part of it?
Read more…
Traveling with Jewelry? Four Safety and Security Tips.
Protecting Your Personal Information
Easy steps to help protect your identity and personal information in your day to day activities. Read more.