
Commercial Insurance ·
Restaurants
Restaurant Industry Insurance Built for the Complexity of What You Produce
Specialized coverage for food manufacturers, processors, distributors, restaurants, and specialty food producers across Pittsburgh, Western PA, and the Mid-Atlantic.
Your risk profile isn't standard. Neither is our approach.
From product recall liability to temperature-controlled cargo loss, food businesses carry risk profiles that generalist brokers rarely understand. Simpson | McCrady does.
Why This Requires Expertise
Why Food Industry Insurance Requires a Specialist
Body copy loads from the CMS.
Food businesses carry a risk profile unlike nearly any other industry. A single contamination event, whether a supplier adulterates an ingredient or a pathogen enters your production line, can simultaneously trigger product liability claims, a voluntary or mandatory recall, FDA or USDA regulatory action, and reputational damage that outlasts the incident itself. Standard commercial policies are not built to absorb that chain reaction, and a generalist broker who treats food coverage as one line item in a 30-industry dropdown will not have the carrier relationships to respond when it happens.
For food manufacturers, processors, distributors, and restaurant operators, the exposures compound quickly: equipment breakdown that halts production and spoils perishable inventory; workers' compensation claims in environments with elevated slip, cut, and repetitive-motion injury rates; commercial auto liability for temperature-sensitive delivery fleets; and liquor liability for food-and-beverage operators serving alcohol on or off premise. Each of these requires carrier markets that specialize in food-sector risk: markets that admitted carriers rarely offer on competitive terms for mid-market operations, and that many regional brokers simply do not access.
Food industry risk management demands a broker who speaks your language, understands the regulatory environment governing your specific segment (whether you're a Pennsylvania-licensed processor, a regional distributor operating across Mid-Atlantic state lines, or a restaurant group navigating local health codes) and can place coverage across admitted and surplus-lines markets without leaving gaps between policies. That is work Simpson | McCrady has been doing for food businesses across Western PA and the Mid-Atlantic for generations.
What We Cover
Food Business Insurance Coverage: What We Place
Get an Expert Review of Your Current Program.
Our Approach
How We Work With Food Businesses
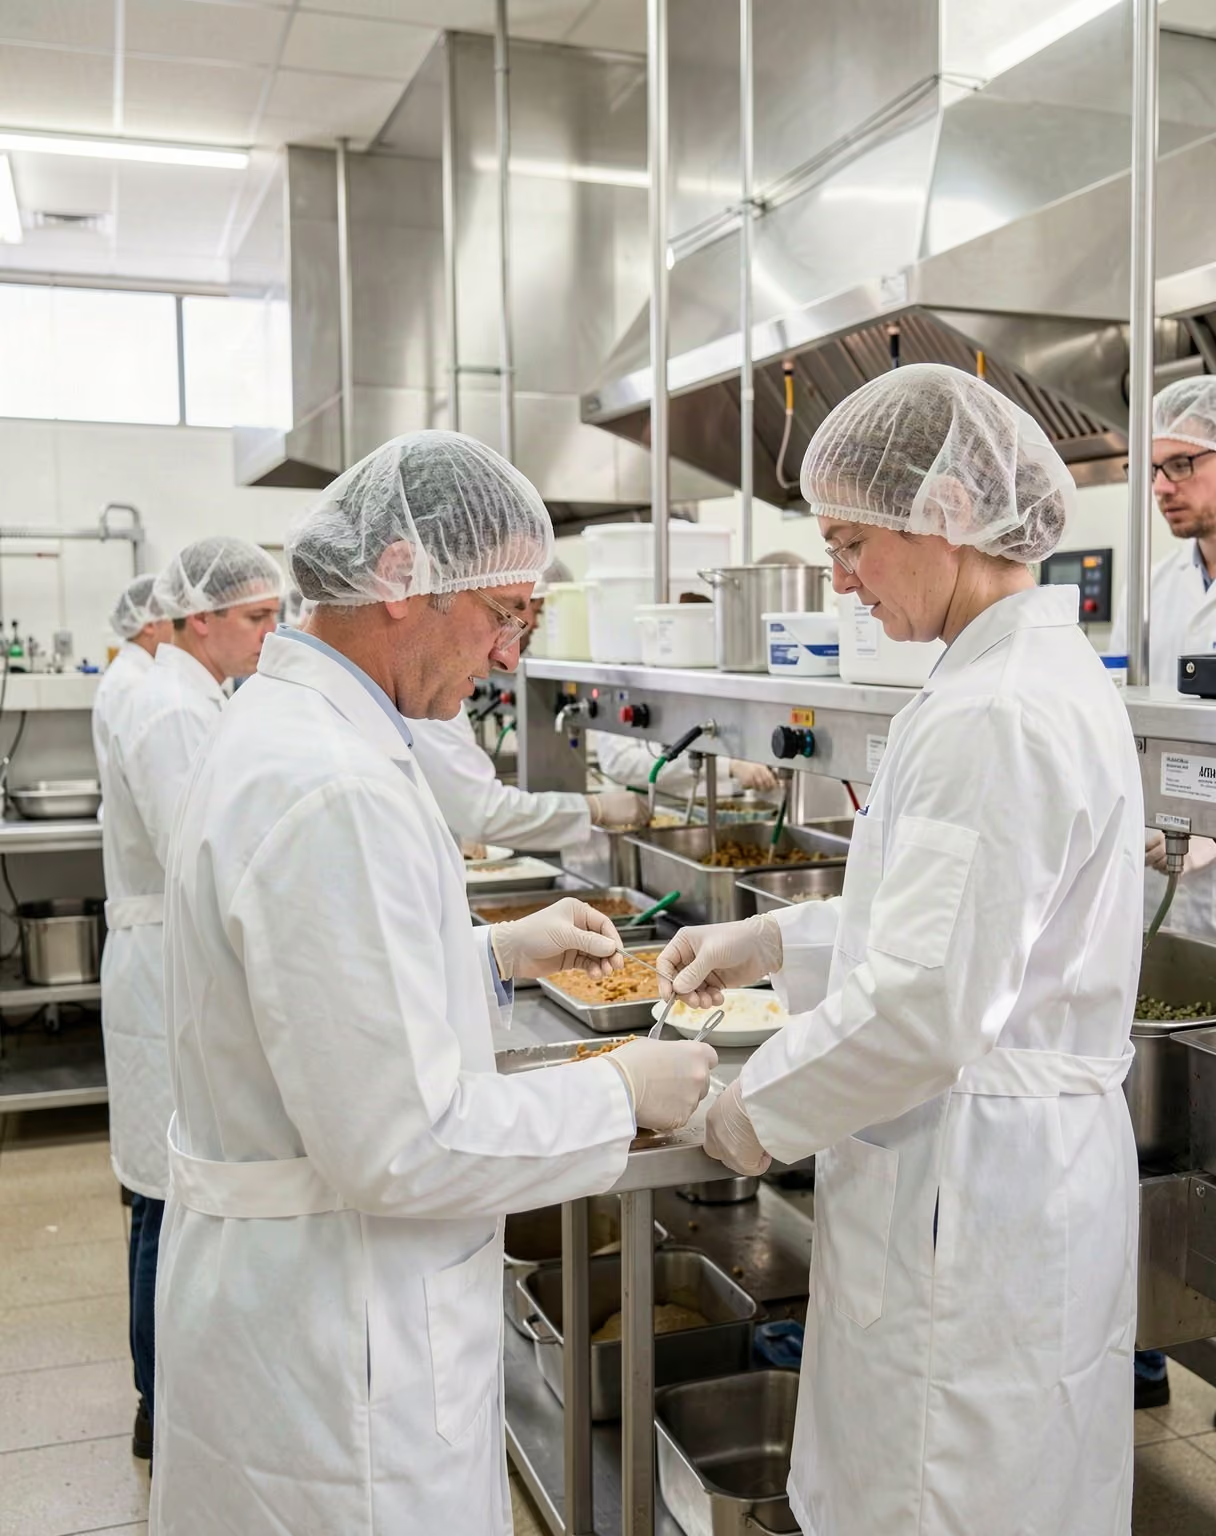
Most food business owners come to us having outgrown their current broker: either their coverage hasn't kept pace with their operation, they've experienced a loss that revealed a gap, or they've simply never had a broker who understood the difference between a food manufacturer's risk profile and a general contractor's. Our first step is always a thorough exposure analysis: understanding your production processes, distribution channels, supplier relationships, and the specific regulatory environment governing your segment across Pennsylvania, the Mid-Atlantic, and beyond.
As an independent broker, we are not captive to any single carrier. That independence matters in food-sector insurance, where admitted markets often decline or impose restrictive exclusions on contamination and recall coverage, and where the right placement may involve specialty or surplus-lines carriers alongside standard commercial lines. We maintain active relationships with the carriers who have demonstrated willingness to respond fairly when a food-sector loss occurs. Our job is to know which markets are right for your specific operation (a regional Pennsylvania processor, a Pittsburgh-based restaurant group, a Mid-Atlantic distributor) and to negotiate terms that reflect your actual loss history and risk controls, not a generic food industry rate table built for Fortune 500 food conglomerates.
Once coverage is placed, our relationship with your business does not end at binding. We conduct structured annual reviews to ensure your program reflects changes in your operation: new product lines, expanded distribution territory, facility additions, regulatory changes affecting your segment. When a loss event occurs, our team advocates directly on your behalf through the claims process, ensuring your carrier responds according to the coverage you purchased. That advocacy, built on more than 100 years of Pittsburgh presence and carrier relationships that run deep, is what separates Simpson | McCrady from a large-account servicing team that has never heard your name.
Firm Credentials
The Depth Behind Your Coverage
One straightforward conversation is all it takes to understand where your coverage stands, and where it should be. Protecting Tomorrow Today.
Prefer to call? 412-261-2222 · info@simpson-mccrady.com