Insights & News
Perspectives on Risk, Wealth & What Matters Most
Advisor guidance for private clients and business owners, alongside news from the firm.
Everything we publish now lives in one library: articles, market commentaries, firm news, and community stories. Filter by Insights or News, then browse what matters to you.
Featured Content Spotlight
Selected by Our Advisors
Every piece in this row was hand-picked, not auto-populated, because it addresses something our advisors are actively discussing with clients right now. Whether that's a timely market commentary, a new case study, or a deep-dive into a risk category affecting your family or your business, these are the perspectives worth your attention today.
Five Nonprofit D&O Insurance Questions Every Board Should Ask Before Year-End
Can nonprofit board members be sued personally? That was the question that got the biggest reaction when Derek Gallagher spoke on a nonprofit insurance panel last month. The short answer is yes. Board members, officers and volunteers can be named in a lawsuit alongside the organization, and even a claim without merit has to be defended.
I've spent more than six years at Simpson | McCrady as an Account Executive, working with nonprofits of every size since day one. I'm a member of the Special Needs Consortium, where I serve on the board and the education committee. In those roles I've seen firsthand why nonprofit D&O insurance (Directors and Officers coverage) matters.
Recently I sat on a panel with respected peers, speaking with executive directors, staff, board members and donors. The question that got the biggest reaction was a simple one: can board members be sued personally?
Can nonprofit board members be personally sued?
Yes. Board members, officers, staff and volunteers can be named in a lawsuit alongside the organization, by employees, donors, regulators, creditors and even the people you serve. Even a claim without merit has to be defended, and legal bills hit small budgets hardest. D&O insurance is designed to pay defense costs, settlements and judgments when leaders are accused of a wrongful act, such as an error, a misleading statement or a breach of duty. That's why the details of your policy matter. As boards gather for year-end reviews and 2027 planning (in between fundraising campaigns and holiday functions), here are five questions I'd want every board to bring to the table.
1. Who counts as an insured?
A policy only protects the people it names. Many include current and former board members, officers, employees with certain managerial responsibilities, volunteers, committee members and the organization itself. Check whether yours does.
Two myths come up here. Volunteer protection laws limit some personal liability, but they don't stop a lawsuit, pay legal fees or protect the organization. And bylaws that promise to indemnify (reimburse) the board are only as strong as your bank account.
2. Is employment practices liability included, and at what limit?
Employees are the most common source of nonprofit D&O claims, from wrongful termination to discrimination, harassment and retaliation. Employment practices liability (EPL) coverage is built for these claims.
Some nonprofit management liability policies include EPL. Others sell it separately, and some programs lack it entirely. Ask whether you have it, what the limit is, and whether it's shared with the rest of the policy. Some policies also extend this coverage to claims brought by volunteers, so check whether yours does. A small staff doesn't mean small exposure.
3. Does everyone share one limit, and do legal fees come out of it?
This one surprises boards most. Most D&O policies have an aggregate limit, the most they'll pay for all claims combined in a policy year. In many policies, the organization, its leaders and any EPL claims all draw from that single limit, and defense costs usually reduce it rather than sitting on top of it.
In practice, a $1 million policy that spends $400,000 on defense has $600,000 left for a settlement, a judgment or the next claim. When leaders' interests differ and each needs their own attorney, that limit shrinks even faster. For illustration, picture an animal shelter whose donors sued the board over how it represented its finances. Three lawsuits followed, with defense costs over $530,000. On a $1 million shared limit, that alone would use more than half.
Ask your broker whether your limit fits your size, the number of people insured and your budget. Options can include separate limits for D&O and EPL, or an added limit just for individual leaders. Also ask about your retention, the amount the organization pays before the policy kicks in, much like a deductible. Make sure it's one your budget can handle.
4. Who handles the defense, and when are legal bills paid?
Some policies give the insurer a “duty to defend,” meaning it appoints and manages the attorneys. Others let you choose counsel and reimburse covered costs. Ask how much say your board has.
Timing matters too. Ask whether defense costs are advanced as bills come in or only reimbursed later, which can take months. For a nonprofit with tight cash flow, fronting those fees pulls money from programs and payroll. One catch: if a claim turns out not to be covered, advanced costs may have to be repaid.
Finally, know the settlement rules. Most policies require the insurer's consent before you settle or take on legal costs, and some include a “hammer clause” that can cap the insurer's payment if your board turns down a settlement it recommends.
5. What's excluded, and what happens if we merge?
Every policy has exclusions worth reading before you need them. Three to watch for:
- Insured vs. insured: excludes or limits claims one insured brings against another, like one board member suing another. Some policies carve back certain claims, such as those by employees.
- Prior or pending litigation: claims tied to lawsuits that existed before a set date are usually excluded.
- Wage and hour: pay and overtime disputes are often excluded or capped.
If a merger or affiliation is on the horizon, talk with your broker before it closes. Many policies then cover only acts that happened before the deal.
Put nonprofit D&O insurance on your next board agenda
Bring these five questions to your next board meeting or year-end planning session. We're happy to review your policy and walk your board through it, no cost, no pressure. Reach me at 724-650-5145 or DGallagher@Simpson-McCrady.com, or visit our management liability page.
This article is a general guide, not legal advice. Every policy and claim is different.
Lithium-Ion Battery Handling & Storage
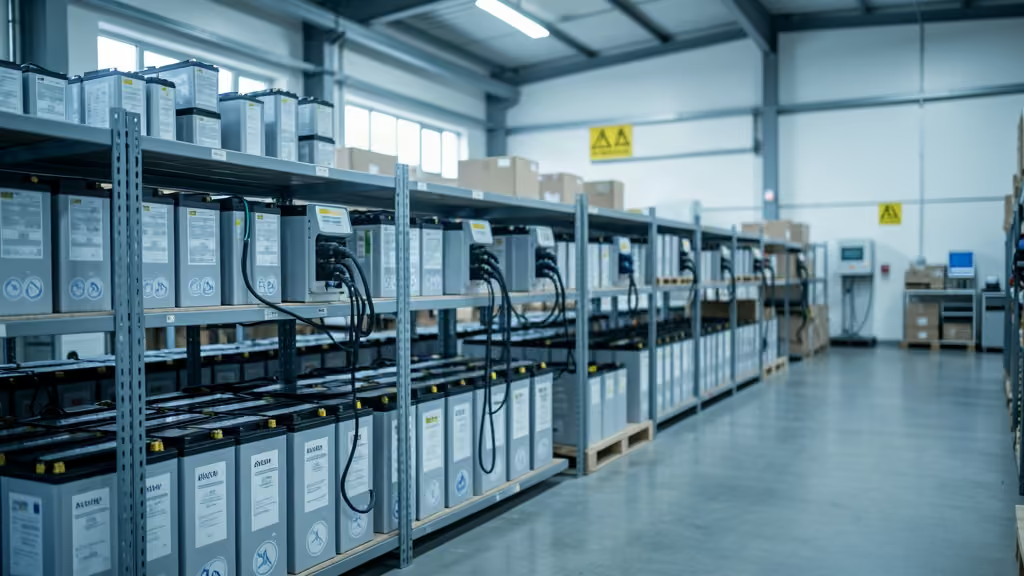
A best-practice guideline for preparing your facility or home for the safe use and storage of lithium-ion batteries and energy storage systems: how and why cells fail, the fast-shifting regulatory and liability landscape, and configuration-specific controls from a charging bench to a container-scale system.
A best-practice guideline for preparing your facility or home for the safe use and storage of batteries and energy storage systems.
The Growing Risk
Lithium-ion (Li-ion) and lithium-polymer (Li-Po) batteries now power nearly every corner of modern operations: cordless tools and equipment, material-handling fleets, electric vehicles, micro-mobility devices, and the large stationary energy storage systems (ESS) that stabilize power supply and support renewable generation. Their high energy density, long service life, and fast recharging have made them the default choice. Those same qualities, however, concentrate a great deal of energy into a small, chemically reactive package. When a Li-ion battery is defective, damaged, poorly stored, or improperly charged, it can fail violently, releasing intense heat, toxic gas, and a self-sustaining fire that conventional extinguishers struggle to control.
The scale of the exposure is growing with adoption. Since the start of 2025 alone, the U.S. Consumer Product Safety Commission has issued 46 recalls and safety warnings for consumer products powered by lithium-ion batteries, and several high-profile facility fires have reshaped how regulators, fire officials, and insurers view the hazard. For any organization that uses, charges, or stores these batteries in more than trivial quantities, the question is no longer whether to manage the risk, but how thoroughly.
This guideline is a practical roadmap for our clients. It explains how and why these batteries fail, summarizes the emerging legal and regulatory landscape, and lays out configuration-specific best practices for preparing your facility, from a handful of tool batteries on a charging bench to a container-scale energy storage system.
Understanding the Risk
How lithium-ion batteries fail: thermal runaway
Nearly every serious Li-ion incident traces back to a single phenomenon: thermal runaway. It begins when one cell generates more heat than it can dissipate, often because of an internal short from a manufacturing defect, physical damage such as a puncture or crush, overcharging, deep discharge, or exposure to excessive heat. As the cell heats, it ignites its own flammable electrolyte; that heat spreads to adjacent cells, which fail in turn, producing a self-reinforcing chain reaction. Because the reaction generates its own oxygen, these fires are difficult to extinguish, can reignite hours later, and react violently with water where lithium metal is present.
Critically, failure does not happen all at once. It escalates through recognizable stages, and the earlier the failure is detected, the more options remain to intervene.

Beyond fire: toxic and environmental exposure
Li-ion fires are not only a combustion hazard. Burning cells release highly toxic gases, including hydrogen fluoride (HF) and per- and polyfluoroalkyl substances (PFAS, the persistent “forever chemicals”), that can injure the eyes, skin, and respiratory system and require evacuation. Water used to fight a battery fire can become contaminated with heavy metals such as cobalt, nickel, copper, and manganese, creating a risk of soil and groundwater pollution if it is not contained. After the January 2025 Moss Landing energy storage fire in California, which destroyed roughly 55,000 battery modules, EPA soil sampling detected several of these heavy metals at levels exceeding screening standards in the surrounding area.
The emerging legal and regulatory landscape
The regulatory picture is shifting quickly, and it increasingly reaches organizations that merely handle batteries rather than manufacture them. In May 2023, the EPA advised that most lithium-ion batteries on the market today are likely to qualify as hazardous waste under the Resource Conservation and Recovery Act (RCRA) based on their ignitability and reactivity. The agency is now developing a dedicated “universal waste” category for lithium batteries, with a proposed rule anticipated in 2026 and a final rule expected in 2027. At the state level, Extended Producer Responsibility (EPR) programs are expanding. Illinois requirements took effect January 1, 2026, and California has enacted both stewardship-plan obligations (AB 2440) and a point-of-sale recycling fee (SB 1215). Meanwhile, some states impose stricter hazardous-waste thresholds than the federal baseline.
The liability exposure is equally significant. Under the federal Superfund statute (CERCLA), cleanup liability is strict, joint-and-several, and retroactive: facility owners and operators, parties that arrange for disposal or recycling, and transporters can all be named, and even sending a small volume of defective cells to a contaminated site can expose a company to a share of the full cleanup cost. Following Moss Landing, the operator entered a CERCLA settlement in July 2025 to fund a cleanup expected to take two or more years. Organizations once considered removed from battery operations, such as auto dealerships handling EV batteries or retailers managing consumer returns, can now trigger hazardous-waste obligations, and California penalties can reach tens of thousands of dollars per day, with criminal exposure for knowing violations.
Foundations: Selection, Inspection, and Built-In Safeguards
Buy quality; avoid counterfeits
The single most effective way to reduce battery risk is to keep defective cells out of your facility in the first place. Purchase tools, equipment, and batteries from reputable manufacturers whose products are certified to the applicable Underwriters Laboratories (UL) standards, and buy replacement batteries and chargers only from the original equipment manufacturer (OEM) or its authorized vendors. Counterfeit and aftermarket batteries frequently omit the internal safeguards that protect genuine cells and are a leading contributor to failures. Where your application allows, consider lithium iron phosphate (LFP / LiFePO₄) cells, a Li-ion chemistry known for greater thermal stability and lower susceptibility to thermal runaway.
Inspect on arrival and before every use
Establish a quality-control step so a designated employee inspects new batteries on delivery, and personnel check batteries before each use. Remove from service, and dispose of properly, any battery showing bulging or swelling; cracked, broken, or discolored casings; excessive heat during charging or use; hissing; leaking; or smoke or unusual odors. Multimeters and digital or infrared thermometers support periodic, documented health checks. Keep a Safety Data Sheet (SDS) on file for every battery on site; these drive correct storage, handling, and emergency response.
Rely on built-in protections, but not on them alone
Quality Li-ion batteries include layered safeguards: a separator that shuts down ion flow as temperature rises, a pressure-relief vent, thermal interrupts and fuses, overcharge and short-circuit protection, temperature sensors, cell balancing, and a Battery Management System (BMS) that monitors state of charge, temperature, and cell health and can disconnect the pack when it detects an anomaly. These features reduce risk but do not eliminate it; facility controls remain essential.
Preparing Your Facility by Configuration
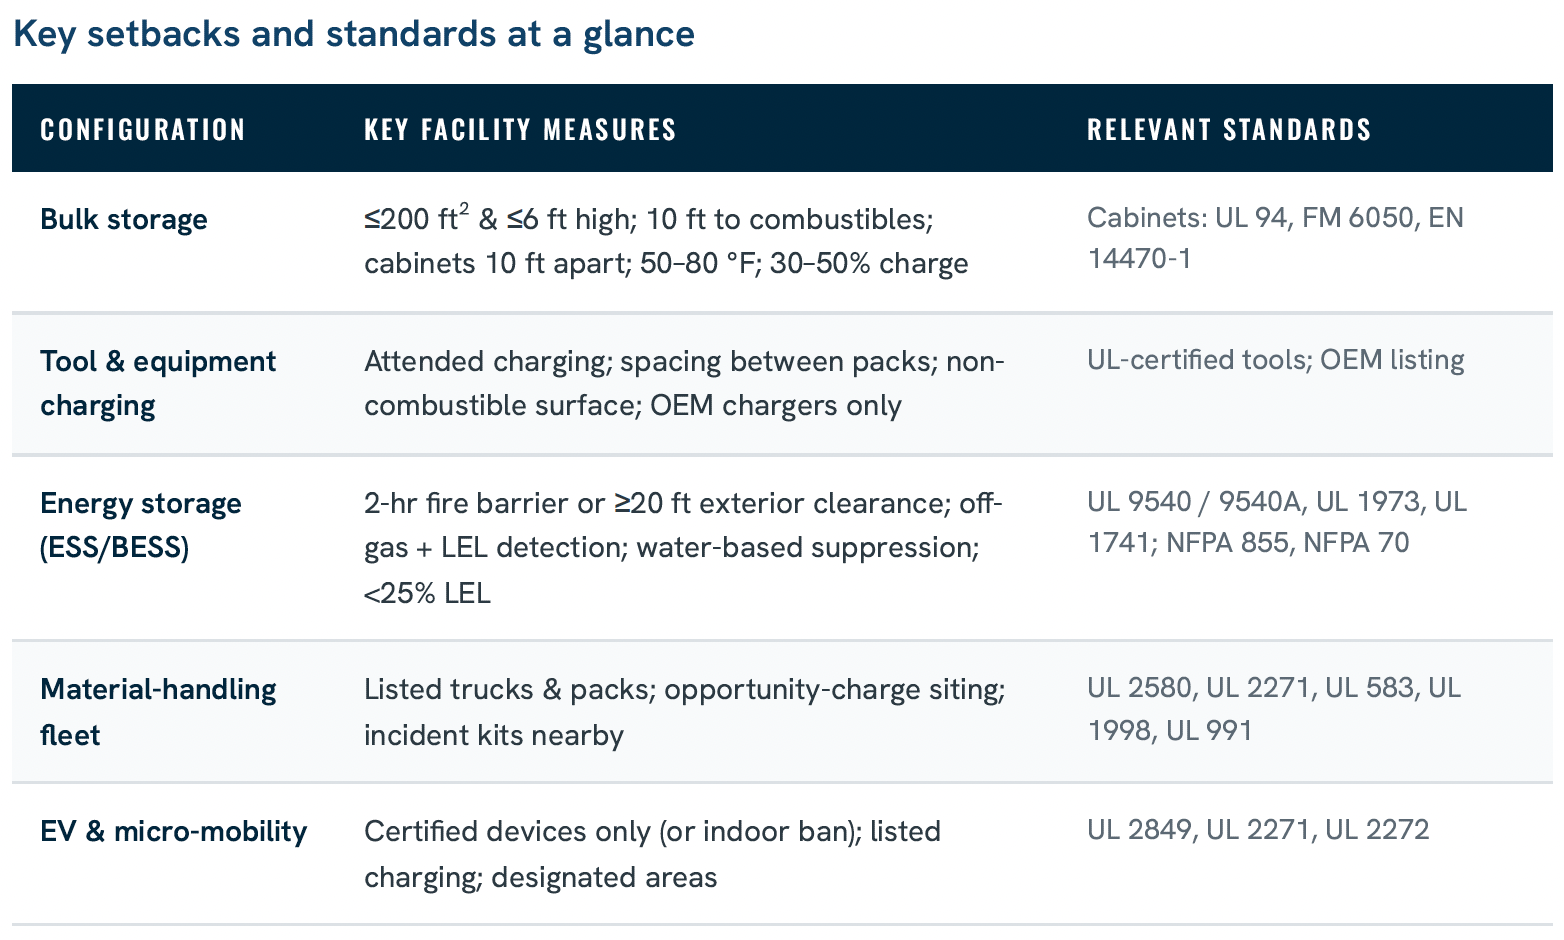
The right controls depend on how batteries are used and stored. The practices below address the configurations our clients most commonly operate; a summary of key setbacks and standards appears in the table at the end of this section.
General and bulk storage
Charging stations for tools and equipment
Most tool-battery incidents occur during charging. To avoid this:
Energy storage systems (ESS / BESS)
Stationary energy storage introduces the largest concentration of stored energy on many sites and warrants a design-led approach. New systems should be certified to UL 9540 (Energy Storage Systems and Equipment) and evaluated using the UL 9540A test method, which characterizes thermal-runaway fire propagation and informs required spacing, ventilation, and fire protection; battery units should be UL 1973-listed and inverters UL 1741-certified. Installations should follow NFPA 855 (Installation of Stationary Energy Storage Systems) and NFPA 70 (Article 706). For further continuity:
Material-handling equipment (forklifts and pallet jacks)
Electric material-handling fleets increasingly use Li-ion packs with decentralized “opportunity charging” throughout the operation. System best practices for this equipment include:
Electric vehicles and micro-mobility
E-bikes, e-scooters, and hoverboards are a frequent source of facility fires, and many jurisdictions now regulate them; in New York City, for example, e-bikes must be certified to UL 2849. As such, it is recommended that a policy be adopted that outlines the following:
Emergency Response and Incident Readiness
Even well-run facilities should plan for failure. Build a written emergency response plan around the principle that early action and fast evacuation save lives and property. It is heavily recommended that the local fire department be contacted and made aware of the type, configuration, and location of battery systems within your facility. Having their insight and input into the development of your emergency response plan is vital.
Detection and isolation. Train staff to recognize the early signs (unusual odor, discoloration, swelling, excessive heat, hissing, or smoke) and, only if it is safe to do so, to move a suspect battery away from combustibles into a fire-rated isolation container. Keep a pail of sand nearby as a smothering agent.
Small, incipient fires. Because battery fires emit toxic fumes, all untrained personnel should evacuate immediately. Only personnel specifically trained to fight small battery fires should attempt to do so, positioned between the fire and the nearest exit; if the extinguisher is ineffective, smoke becomes heavy, or the responder is at all uncomfortable, they should evacuate. If flames are subdued, submerge the battery in sand or douse with water as directed by the SDS; sand is the safer choice where lithium metal may be present.
Thermal runaway and large fires. No one should attempt to fight a thermal-runaway or large-scale fire. Activate the alarm, evacuate the building, and call emergency services, providing the battery type and size, the location, and any hazardous materials present, and hand the relevant SDS to responders when possible.
First aid. For eye or skin exposure, flush with water for at least 15 minutes and seek medical attention; move anyone exposed to fumes or smoke into fresh air and administer first aid or CPR as needed. Because effects can be delayed, exposed individuals should be evaluated by a medical professional.
Disposal and cleanup. Never place Li-ion batteries in general waste; route them to a certified recycler, and store damaged units awaiting pickup in a non-combustible container located about 25 ft (8 m) from occupied buildings. Provide containment or retention basins to capture contaminated firefighting water, consistent with the environmental exposures described earlier.
2026 Personal Insurance and Risk Management Trends in Private Client Services
A Comprehensive Analysis of Emerging Risks, Market Dynamics, and Strategic Solutions for High-Net-Worth Individuals The private client insurance landscape is experiencing unprecedented transformation driven by converging forces: escalating climate-related catastrophes, explosive cyber threats, nuclear verdict litigation trends, and the largest intergenerational wealth transfer in history.
A Comprehensive Analysis of Emerging Risks, Market Dynamics, and Strategic Solutions for High-Net-Worth Individuals
The private client insurance landscape is experiencing unprecedented transformation driven by converging forces: escalating climate-related catastrophes, explosive cyber threats, nuclear verdict litigation trends, and the largest intergenerational wealth transfer in history. As we enter 2026, high-net-worth (HNW) individuals and families face a fundamentally different risk environment than existed even five years ago.
Key findings include:
- Climate-driven property insurance costs rose 10.4% nationally in 2024, with catastrophe losses reaching $176 billion
- Personal cyber risk exposure exploded 3,000% for deepfake fraud, with average U.S. breach costs exceeding $10.22 million
- Nuclear verdicts ($10M+) median awards reached $23.8M in 2023, creating liability insurance crises
- Baby boomers control $19.7 trillion in real estate (41% of U.S. total), creating complex transfer challenges
- Protection gaps widened significantly, with only 47% of catastrophe losses insured in 2024
For private clients, their advisors, and family offices, 2026 demands proactive risk management strategies addressing these interconnected exposures while navigating an increasingly complex insurance marketplace.
The Evolving High-Net-Worth Risk Landscape
Baby boomers control $19.7 trillion in U.S. real estate—41% of total value despite representing only 20% of the population[1]. This concentration, combined with aging properties and intensifying climate risks, creates unprecedented insurance challenges.
High-net-worth individuals face converging exposures: multiple properties across catastrophe-prone regions, valuable collections requiring specialized coverage, elevated liability risks from social inflation, complex estate structures demanding policy coordination, and growing cyber vulnerability as digital wealth management expands.
The insurance protection gap has widened dramatically. In 2024, U.S. catastrophe economic losses reached $176 billion while insured losses totaled only $99 billion—a $77 billion protection gap[2]. For private clients, this reflects underinsurance from rapid property appreciation, coverage exclusions for flood and earth movement, policy sub-limits, increasing carrier restrictions in high-risk areas, and, in some cases, the choice to self-insure.
1. Climate Change and Property Insurance Crisis
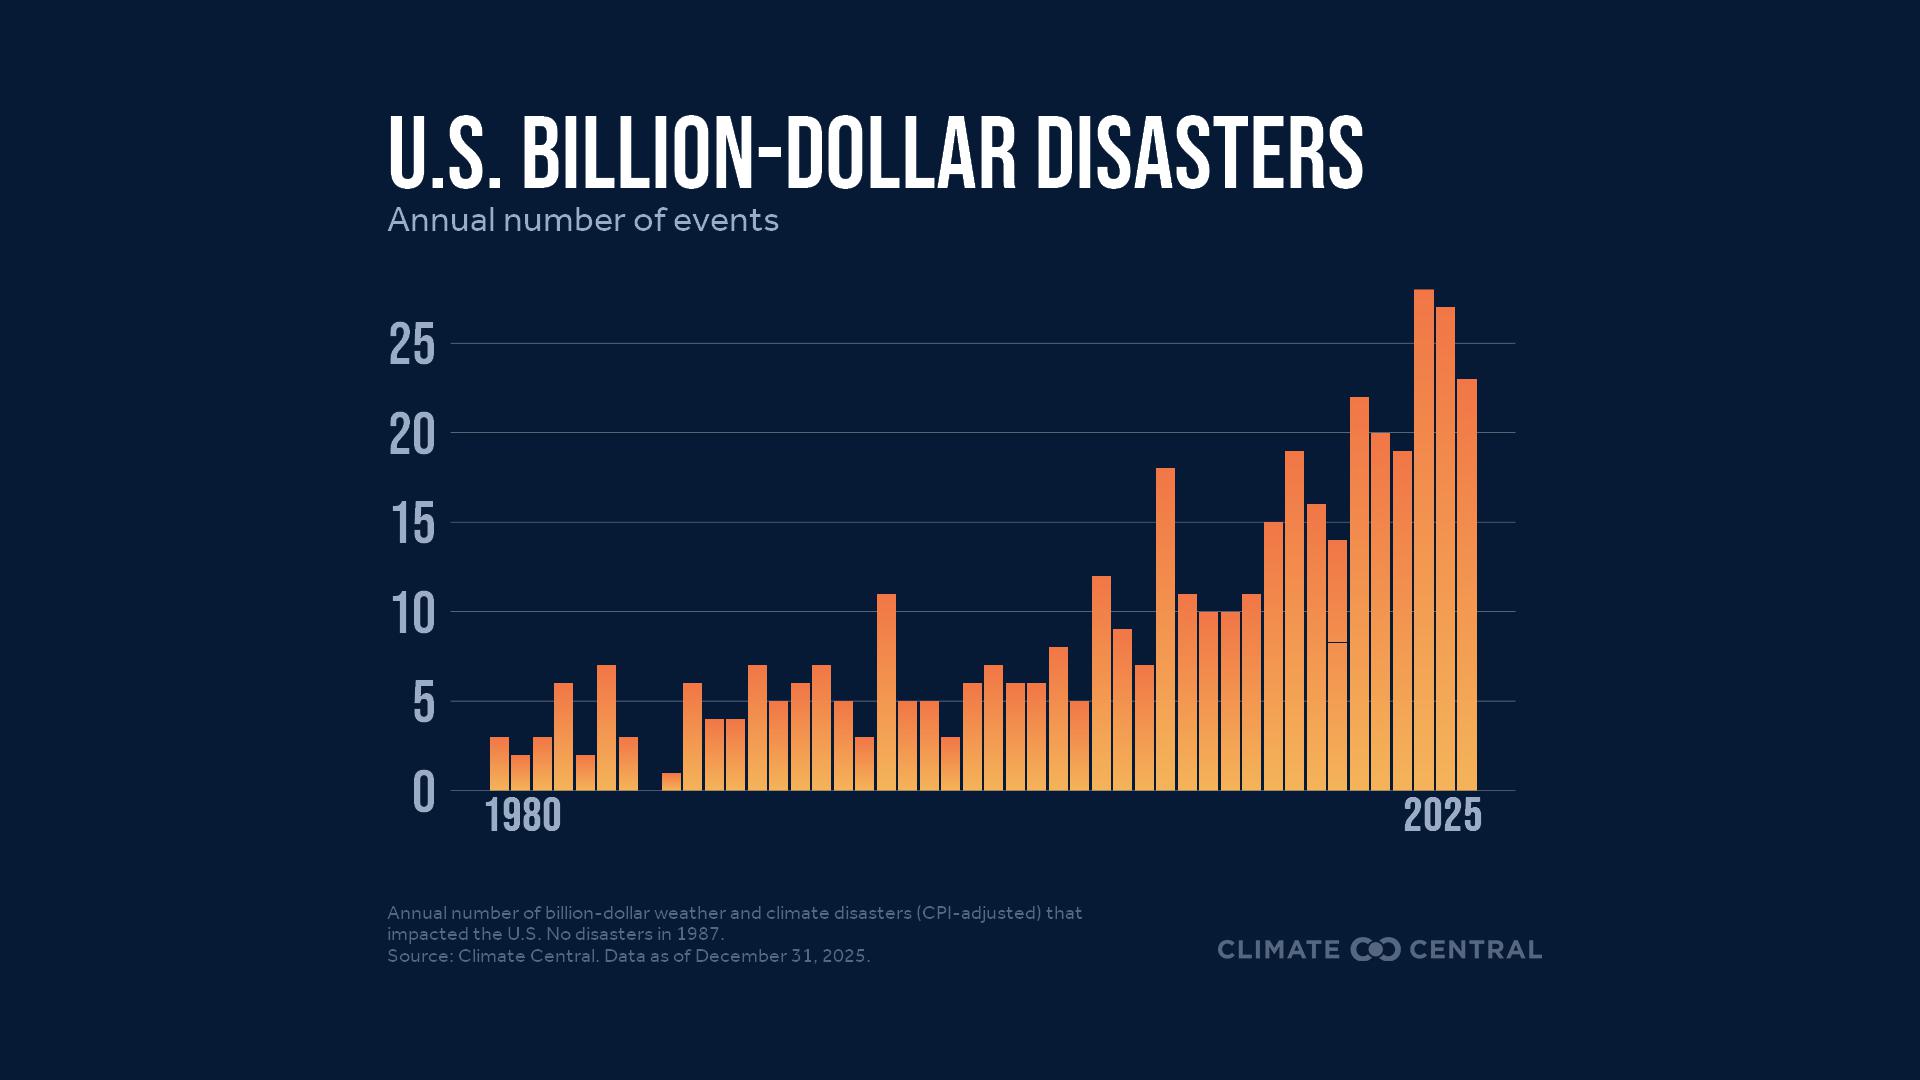
The year 2025 marked the fourth-warmest on record for the United States, with 27 weather disasters exceeding $1 billion in losses each[3]. Notable events included the Eaton and Palisades Fires destroying 18,000+ structures in Southern California, Texas Hill Country’s 1-in-1,000 year flood killing 135 people, and 1,559 tornado reports—fifth-highest on record[3].
Sea level rise has doubled from .06 inches to .14 inches annually, creating 3-9 times more frequent coastal flooding than 50 years ago[4]. Combined with accelerating drought (42.8% of U.S. affected per US Drought Monitor), these trends fundamentally reshape property insurability.[4]
Insurance Market Response:
Homeowners insurance rates increased 10.4% nationally in 2024, with six states exceeding 20%[5]. Major carriers withdrew from California, Florida, and Louisiana, forcing reliance on surplus lines (up 31.2% to $5 billion) and residual markets (up 6% to $10 billion)[5]. Carriers implemented percentage-based wind/hail deductibles, roof age restrictions, and tightened underwriting standards.
For HNW clients with multiple high-value properties, this creates acute challenges: limited carrier options, higher premiums, broader exclusions, and potential uninsurability in catastrophe-prone coastal and wildfire zones where many retirement properties are concentrated.
How to address:
Home Resiliency
- Prioritize loss‑prevention tools as these steps can improve insurance options and potentially reduce premiums:
- Water leak detection and automatic shutoff systems
Whole home backup generators
Annual or seasonal maintenance checklists to address minor issues before they become major
Coverage Options
Review your policy for exposures such as flood, earthquake, and sinkhole to determine whether adding these coverages makes sense based on where your home is located.
Acquisitions
- Consult your advisor before making an offer—especially for out of town or out of state home purchases. This helps you ask your realtor the right questions, improve insurability, manage long term costs and make educated buying decisions.
- Consolidating coverage with one carrier can enhance program efficiency, improve eligibility for better coverage, and ensure consistency across policies to prevent gaps or overlaps in coverage.
2. The Cyber Threat to Personal Wealth
Escalating Personal Cyber Threats
Ransomware Evolution
Ransomware was involved in 44% of all data breaches in 2024, with attacks shifting to “double extortion”—stealing personal financial records, tax returns, estate documents, and smart home data before encrypting systems and threatening public release[7].
The Deepfake Epidemic
AI-generated deepfakes exploded 3,000% in 2025, enabling unprecedented fraud targeting wealthy individuals[9]:
- Voice cloning of family members requesting urgent wire transfers
- Video impersonations of financial advisors authorizing transactions
- Synthetic identity creation for account takeovers
- AI-enhanced phishing with 54% success rates—quadruple traditional methods[10]
Shadow AI Risks
Household staff and family members using unauthorized AI tools (ChatGPT, Claude) for convenience create data leakage risks as personal information may be retained and exposed.
Cyber Risk Management Best Practices
Private clients should implement layered cyber defenses:
Technical Controls
- Multi-Factor Authentication (MFA): Strongly recommended for all financial accounts, email, cloud storage.
- Endpoint Detection & Response (EDR): Advanced antivirus/anti-malware on all devices
- Network Segmentation: Separate IoT/smart home devices from financial/personal computing
- VPN Usage: Virtual private networks for all remote/travel internet connections
Interactive Best Practices
- Wire Transfer Protocols: Verbal confirmation of all wire instructions via known phone numbers
- Email Authentication: Training to identify phishing, suspicious links, urgency-based manipulation
- Social Media Privacy: Limit disclosure of travel, property locations, purchases, family information
Coverage Coordination
- Review homeowners for any cyber coverage endorsements and what limits are available.
- Coordinate with any business cyber policies if working from home.
- Understand what is and isn’t covered.
3. Nuclear Verdicts and Liability Crisis
Nuclear verdicts—jury awards exceeding $10 million—have escalated dramatically. Analysis of 1,288 verdicts from 2013-2022 reveals median awards reaching $23.8 million in 2023 (up from $21.1 million), with mega verdicts ($100M+) increasing 400% since 2013[14].
Florida leads with 0.939 verdicts per 100,000 people—50% higher than New York. California, Florida, New York, and Texas produce half of all national nuclear verdicts[15]. State courts host 90% of verdicts versus only 10% in federal courts.
Critically, noneconomic damages (pain and suffering) drive verdict severity. In seven of ten years, noneconomic damages exceeded punitive damages, demonstrating susceptibility to psychological manipulation including “reptile theory” tactics, anchoring (suggesting arbitrary amounts that double to quadruple awards), and $1 billion in annual lawsuit advertising normalizing extreme awards[16][17][18].
Impacts on Private Clients
A 2025 Georgia jury awarded $4.2 million for a dog attack—far exceeding typical homeowners policy sub-limits of $100,000-500,000[19].
Making sure you have an appropriate umbrella limit is paramount. This limit of coverage is meant to be a moving target that is adjusted as your lifestyle evolves. Have a conversation with your advisor to discuss any significant changes in your net worth and/or public profile. Higher limits are available and we’re here to help.
4. Intergenerational Wealth Transfer Challenges
Baby boomers control $19.7 trillion in real estate, with the boomer population projected to decline 23% by 2035 and another 47% by 2045—transferring enormous holdings to millennial and Gen X heirs[21][22]. However, nearly 40% have lived in current homes 20+ years, with 68% in homes at least 30 years old[23]. Deferred maintenance—aging roofs, HVAC systems, electrical, and plumbing—often requires $50,000-$200,000+ in immediate upgrades inheritors lack funds to complete.
Insurance Complications
When aging parents move to assisted living, standard homeowners policies limit vacant property coverage to 30-60 days, requiring vacant home endorsements (30-50% higher premiums), regular inspections, winterization, and security monitoring. Failure to maintain proper coverage results in claim denials for theft, vandalism, or weather damage.
Post-inheritance, carriers increasingly restrict coverage on older homes through roof age limitations (declining roofs over 15-20 years), four-point inspections, wind mitigation requirements, and wiring restrictions. Inheritors may discover properties uninsurable without significant investment.
Multiple heirs create additional complications: disagreement on disposition, unequal contribution ability, mortgage difficulties, and liability exposure when one heir is judgment-proof while another has assets.
Many boomers retired to Sunbelt locations—Florida, California, Texas, Louisiana, Arizona—now facing acute climate risks. Millennial inheritors discover properties in locations they don’t want with deteriorating insurance availability. [26].
Avoiding Underinsurance (and Overinsurance)
- Choose carriers that use in home appraisals, apply annual inflation guards, and offer guaranteed or extended replacement cost. These protections help maintain proper insurance to value.
- If you haven’t appraised your fine art, jewelry, or collectibles in 3–5 years, schedule an updated review. Rising precious metal values mean some items may now be underinsured, while others may not require as much coverage and should be reduced which would provide a premium savings.
Asset Transfer Guidance
- Speak with your advisor before transferring assets to ensure proper risk management and insurance planning.
- Advisors can help prepare the next generation with education, loss prevention strategies, and insurance guidance.
- Homes: Discuss improvements that enhance home resiliency and insurability.
- Jewelry, fine art, wine/spirits: Review loss likelihood and proper insurance and risk management approaches.
- Middle market carriers often won’t insure high value items, or, in some cases, charge more for inadequate coverage.
- Asset transfers often indicate that the next generation needs a more sophisticated, high net worth insurance program.
- Working with a private client insurance advisor ensures proper coverage, carrier selection, and expert guidance.
2026 Market Outlook
The private client insurance landscape of 2026 is characterized by converging mega-trends which interact and compound and the need to adjust accordingly is evident.
Property insurance faces continued volatility with national average increases projected 8-12% for homeowners, and 15-25% on average in catastrophe-prone states (FL, CA, TX, LA).
Percentage-based wind/hail deductibles expand beyond coastal zones, roof age limitations tighten to 15-year maximums, and carriers reduce willingness to write vacant or secondary homes. However, reinsurance rates declined 6.6% at January 2025 renewals, bringing modest relief.
Personal cyber policies are becoming a standard need for all clients, with limits increasing in response to the increasing risk.
Umbrella/excess liability premium increases moderate to 5-10% in 2026 after prior 15-30% spikes. There is additional underwriting scrutiny on driver records, property maintenance, dog breeds, and water features.
Conclusion
As the private client insurance environment undergoes rapid and profound change, high net worth individuals face a level of complexity and exposure unlike any previous era.
Climate driven property volatility, surging cyber threats, escalating liability awards, and the massive transfer of aging assets across generations are reshaping both risk and insurability.
In this landscape, protection gaps widen quickly, traditional carriers offer fewer solutions, and the costs of inaction grow exponentially. The path forward requires proactive planning—strengthening property resiliency, modernizing cyber defenses, securing adequate liability protection, and preparing heirs with the right education and insurance structures.
By partnering with skilled private client advisors and adopting a coordinated risk management strategy, families can safeguard wealth, maintain insurability, and navigate the evolving challenges of 2026 and beyond with confidence.
We invite you to reach out with any questions as we’re here to provide recommendations, information and guidance.
Interested in learning more? Check out our Insights page for other relevant education topics.
References
[1] Redfin analysis (2025). Baby boomer real estate holdings. Business Insider.
[2] National Association of Insurance Commissioners. (2025). Natural Catastrophe Risk Dashboard Report, December 31, 2024.
[3] National Centers for Environmental Information (NCEI). (2025). Assessing the U.S. Temperature and Precipitation Analysis in 2025. NOAA.
[4] NOAA Climate.gov. (2025). Sea level change data. National Oceanic and Atmospheric Administration.
Climate Change: Global Sea Level | NOAA Climate.gov
Monthly Climate Reports | Drought Report | December 2025 | National Centers for Environmental Information (NCEI)
[5] National Association of Insurance Commissioners. (2025). Homeowners loss ratio and P&C combined ratio data. Natural Catastrophe Risk Dashboard Report. Natural Catastrophe Risk Dashboard Report.pdf
[6] Khalil, M. (2025, December 3). Cyber Insurance Statistics 2025: Key Trends & Data. DeepStrike. https://deepstrike.io/blog/cyber-insurance-statistics-2025
[7] Khalil, M. (2025). Ransomware involvement in data breaches. Cyber Insurance Statistics 2025. DeepStrike.
[8] Khalil, M. (2025). Ransom demand and payment dynamics. Cyber Insurance Statistics 2025. DeepStrike.
[9] Khalil, M. (2025). Deepfake fraud statistics. Cyber Insurance Statistics 2025. DeepStrike.
[10] Khalil, M. (2025). AI-enhanced phishing success rates. Cyber Insurance Statistics 2025. DeepStrike.
[11] Khalil, M. (2025). Business email compromise claim statistics. Cyber Insurance Statistics 2025. DeepStrike.
[12] IBM Security. (2025). Cost of a Data Breach Report 2025. Cited in DeepStrike Cyber Insurance Statistics 2025.
[13] IBM Security. (2025). AI and automation impact on breach costs. Cost of a Data Breach Report 2025.
[14] Silverman, C., & Appel, C. E. (2024, May). Nuclear Verdicts: An Update on Trends, Causes, and Solutions. U.S. Chamber of Commerce Institute for Legal Reform.
[15] Silverman, C., & Appel, C. E. (2024). Top states for nuclear verdicts analysis. Nuclear Verdicts Report. Institute for Legal Reform.
[16] Silverman, C., & Appel, C. E. (2024). Economic vs. noneconomic damage composition. Nuclear Verdicts Report. Institute for Legal Reform.
[17] Silverman, C., & Appel, C. E. (2024). Anchoring tactics driving nuclear verdicts. Nuclear Verdicts Report. Institute for Legal Reform.
[18] Silverman, C., & Appel, C. E. (2024). Lawsuit advertising impact on verdicts. Nuclear Verdicts Report. Institute for Legal Reform.
[19] PropertyCasualty360. (2025, April 16). Georgia jury awards elderly woman $4.2M for dog attack. https://www.propertycasualty360.com/2025/04/16/georgia-jury-awards-elderly-woman-42m-for-dog-attack/
[20] TransRe. (2024). Medical malpractice verdict analysis. Cited in Institute for Legal Reform Nuclear Verdicts Report.
[21] National Association of Realtors. (2024). Baby boomer real estate ownership analysis. Business Insider.
[22] Harvard Joint Center for Housing Studies. (2024). Baby boomer population decline projections 2025-2045. Business Insider.
[23] Leaf Home & Morning Consult. (2024). Survey of 1,000 baby boomers on home age and maintenance. Business Insider.
[24] Metz, J. (2025). California property tax implications of inheritance. Senior Homeowner Solutions. Business Insider.
[25] Yahoo Finance. (2025). State Farm refused to cover Florida man’s repairs on his Porsche—why the courts are now involved. https://finance.yahoo.com/news/state-farm-refused-cover-florida-095800478.html
[26] Fairweather, D. (2025). Chief Economist commentary on inherited property challenges. Redfin. Business Insider. Boomers are leaving their millennial Children with a huge headache — James Morris Homes
[27] S&P Global Ratings. (2024). Cyber insurance market outlook: Premiums projected to reach US$23 billion by 2026 amid stable industry conditions. Industrial Cyber.
Filter and Browse
Find What's Relevant to You
Everything the firm publishes lives here. Start with Insights for advisor guidance on risk and coverage, or News for what our team has been doing across Western PA, then browse by what matters to you.
A Heartwarming Day at Simpson | McCrady: Bring Your Child to Work Day
The annual Bring Your Child to Work Day at Simpson | McCrady was on Thursday, June 5 and it was a heartwarming and lively occasion—one that fills the office with cheerful chatter, toys, games, and even a plastic golf club and ball or two.
The annual Bring Your Child to Work Day at Simpson | McCrady was on Thursday, June 5 and it was heartwarming and lively occasion—one that fills the office with cheerful chatter, toys, games, and even a plastic golf club and ball or two. Our young guests arrived with wide eyes and big smiles, eager to see where their parents spend their days.
The day kicked off with a sweet start—donuts! Each child received their own employee badge and completed fun “new hire” paperwork, which included questions like “What do you want to be when you grow up?” One awe inspiring answer: Belle from Beauty and the Beast.
A tour of the office followed, giving children—ranging in age from almost 2 to 17—a chance to meet every team member. The break area, with the special coffee and hot cocoa maker was a highlight (we may have run out of hot cocoa), and the excitement continued with a delicious Chick-fil-A lunch that everyone enjoyed together.
Throughout the day, the children got a firsthand glimpse into the world of insurance. For many, it was a day of “firsts”—first time in an office, first paycheck (yes, every child received one!), the first introduction to the insurance industry, and even their first time painting a rock. We even played bingo.
More than anything, the day was about spending time together, for children to see their parents in action, and for all of us to share a little bit of what makes Simpson & McCrady such a special place. From engaging activities and creative crafts to lots of laughter and running around, it was a blend of learning, fun, and togetherness so thank you for bringing in your children for they are awe inspiring.
And thank you to everyone who helped make this tradition such a wonderful success. A special shout out to Kathy Lafon, Lauren Newlin, and Samantha Palumbo and to the Company for making this a special day. We’re already looking forward to and planning another unforgettable Bring Your Child to Work Day next year!
Protecting High-Net-Worth Assets in an Evolving Risk Landscape: 2025 Trends
The risk and insurance landscape for high-net-worth individuals (HNWIs) is rapidly evolving due to legal, economic, and environmental changes. From the rise of nuclear verdicts driving liability exposures to increasing material costs affecting home valuations, strategic insurance planning has never been more critical to protecting high-net-worth assets.
The risk and insurance landscape for high-net-worth individuals (HNWIs) is rapidly evolving due to legal, economic, and environmental changes. From the rise of nuclear verdicts driving liability exposures to increasing material costs affecting home valuations, strategic insurance planning has never been more critical to protecting high-net-worth assets. Additionally, catastrophic weather events, shifting real estate dynamics, and the ripple effects of disasters like last year’s hurricanes and the Palisade and Eaton wildfires demand a reassessment of coverage strategies.
This overview outlines key areas of concern and solutions to ensure that HNWIs maintain robust financial protection against emerging risks:
- The Growing Need for Umbrella Liability Coverage Amid Nuclear Verdicts
- Adjusting Home Valuations to Address Underinsurance Risks and Insuring High End Vehicles with Appropriate Replacement Cost Coverage
- Investing in Home Resiliency to Mitigate Catastrophic Weather Risks
- Flood Insurance Trends & Rising Exposure Risks
- Shifts in the Real Estate Market & Their Insurance Implications
- Insurance Market Adjustments Post-Palisades and Eaton Wildfires
Deep Dive: The Risks in Detail and Solutions
1. The Growing Need for Umbrella Liability Coverage Amid Nuclear Verdicts 
Understanding the Risk
Nuclear verdicts—jury awards exceeding $10 million—are on the rise, particularly in cases involving personal liability, auto accidents, and premises liability. Plaintiffs’ attorneys increasingly target individuals with substantial assets, leveraging social inflation and jury sympathy to secure massive settlements.
Why Standard Liability Coverage Is Insufficient for Protecting High-Net-Worth Assets
Most primary home and auto insurance policies offer liability limits between $300,000 and $500,000, an amount that is often inadequate in the face of today’s legal climate. One severe accident or lawsuit could result in financial devastation if assets are not properly protected.
Solution: High-Limit Umbrella Policies
An umbrella liability policy provides excess coverage beyond home and auto policies, ensuring financial security against high-stakes litigation that can threaten high-net-worth assets. For HNWIs, policies with limits of $5 million to $100 million are available, depending on asset exposure and risk profile. If limits have not been reviewed in the last few years, now is the time.
2. Adjusting Home Valuations to Address Underinsurance Risks and Insuring High End Vehicles with Appropriate Replacement Cost Coverage
Homes:
The Rising Cost of Rebuilding
Within the last five years, we have seen a surge in construction costs post pandemic and, most recently, with tariff uncertainty causing overall construction costs to increase roughly 40%. Many factors driving this include:
- Supply chain disruptions impacting building material delivery timelines and costs.
- Labor shortages inflating contractor expenses.
- Increased demand following natural disasters driving up rebuilding costs.
The Underinsurance Problem
Many HNWIs fail to regularly adjust their home insurance coverage to reflect these market shifts, especially after renovations and additions, leaving properties significantly underinsured. This discrepancy becomes painfully clear when claims settlements fall short of actual reconstruction costs.
Solution: Appraisals & Guaranteed Replacement Cost Coverage
- Appraisals post issuance for new policies and updating your insurance advisor of home improvements ensure that insured values reflect current rebuilding expenses. It is important to note that replacement costs are calculated differently than market value costs.
Guaranteed replacement cost policies cover full reconstruction costs, even if they exceed policy limits.
Cars:

New Technology Impacts
Newer, high-end vehicles have similarly seen pain points on the insurance front making it important to insure appropriately. The conveniences of high-tech smart car features and the evolution of electric vehicle technology has significantly impacted the repair costs and components that go into your new vehicles – and how insurance companies need to respond.
Solution: Premium Insurance Coverage and Flexibility to Choose the Right Body Shop
- Choose an insurance carrier that matches the sophistication of your car. Policies that offer Agreed value and robust temporary rental vehicle limits for your vehicles and collector cars help you avoid out of pocket expenses when a claim happens.
- Having the flexibility to use an auto body shop that has the appropriate equipment, licensed staff, and original equipment manufacturer parts for the repairs are important not only for the vehicle safety features but also, so you don’t void out any vehicle warranties.
3. Investing in Home Resiliency to Mitigate Catastrophic Weather Risks
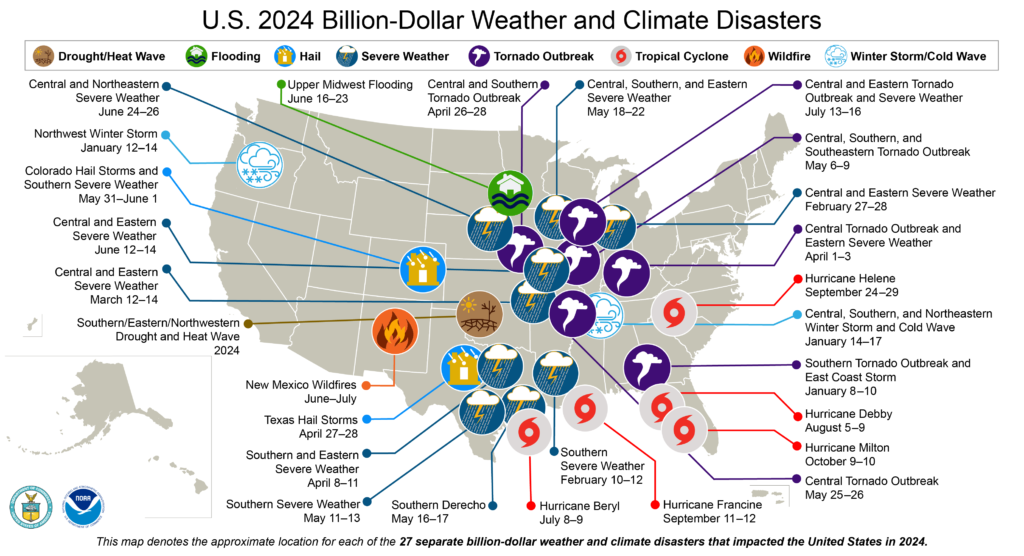
The Growing Threat of Extreme Weather
Hurricanes, wildfires, and other climate-driven disasters are occurring with greater frequency and severity. HNWIs must proactively fortify their properties to reduce risk exposure and secure better insurance terms.
Home Resiliency Investments That Matter
- Fire-resistant materials & ember-resistant vents (critical in wildfire-prone regions).
- Hurricane-rated windows, reinforced roofs, and flood engineering considerations (for coastal and storm-exposed properties).
- Backup power solutions (such as whole-home generators) to maintain security and prevent losses.
Insurance Benefits of Proactive Resiliency
Carriers are increasingly offering premium discounts and favorable terms for policyholders who invest in risk mitigation strategies, making these upgrades financially strategic.
4. Flood Insurance Trends & Rising Exposure Risks Related to Protecting Your High-Net-Worth Assets
Expanding Flood Risk Beyond FEMA Flood Zones
It’s important to remember that low risk does not mean no risk. Climate change is driving unexpected flooding in areas previously considered low-risk which is driving this as a needed component of a family’s insurance portfolio. According to recent studies, over 25% of flood insurance claims now come from properties outside FEMA’s designated high-risk zones.
Challenges with National Flood Insurance Program (NFIP) Coverage
- NFIP policies cap coverage at $250,000 for dwellings and $100,000 for contents, which is far below the needs of HNWI’s homes.
- FEMA’s Risk Rating 2.0 has led to significant premium increases, making private flood insurance a more attractive option.
Solution: Private Flood Insurance & Excess Flood Coverage
- Private flood carriers offer higher limits and more flexible terms.
Excess flood policies provide coverage beyond NFIP caps, ensuring full protection.
5. Shifts in the Real Estate Market & Their Insurance Implications

Market Trends Affecting HNWIs
- HNWIs continue to purchase homes in high-risk areas.
- Coastal and wildfire-prone areas face increasing insurance challenges, leading some homeowners to relocate.
- Carriers are reevaluating underwriting criteria, with some withdrawing from high-risk regions altogether.
Impact on Insurance Strategies
Properties in high-risk zones may require specialty insurance markets.
Multi-property owners should consolidate policies with high-net-worth specialty agents and insurers to optimize coverage and costs. By leveraging the entire insurance program, terms become more favorable and create consistency with holistic coverage and risk management philosophies.
The earlier you can discuss a potential new property purchase with your insurance agent, the better so they can provide important home risk characteristics to consider and contemplate the best possible insurance and risk management options available.
6. Insurance Market Adjustments Post-Palisades and Eaton Wildfires

The Fallout of the Wildfires
The Palisades and Eaton wildfires were a stark reminder of the increasing wildfire risk for affluent homeowners, particularly in California and other fire-prone states. In the aftermath:
- Insurers tightened underwriting standards, with some carriers ceasing to write new policies in high-risk zones.
- Premiums are increasing for existing policyholders.
- Non-renewals increased, forcing homeowners to seek coverage through surplus lines carriers.
Solutions for HNWIs in High-Risk Fire Zones
- Work with specialized high-net-worth insurance carriers that understand the unique needs of affluent homeowners.
- Implement fire mitigation strategies (e.g., defensible space, home hardening) to maintain insurability.
Conclusion: A Proactive Approach to Insurance for Protecting High-Net-Worth Assets
As risks evolve, high-net-worth individuals must take a proactive approach to insurance planning to protect their wealth, properties, tangible assets, and personal liability exposures. Key takeaways include:
- Umbrella liability coverage is essential to shield against nuclear verdicts.
- Insuring your home to value and reassessing when renovating are necessary to prevent underinsurance.
- Investing in home resiliency mitigates catastrophic weather risks.
- Flood insurance must be evaluated beyond FEMA guidelines.
- Shifts in real estate markets require tailored insurance solutions.
- Post-wildfire insurance challenges necessitate specialized underwriting and risk mitigation strategies.
By partnering with an experienced high-net-worth insurance advisor, clients can secure comprehensive, customized coverage that adapts to an increasingly complex risk environment.
Would you like further insights into any of these topics or assistance in reviewing your current coverage? Reach out to our office to discuss!
Interested in learning more? Check out our Insights page for other relevant education topics.
Simpson | McCrady Employees Volunteer at Junior Achievement (JA) BizTown
This past Friday, a group of Simpson | McCrady employees volunteered at Junior Achievement (JA) BizTown, an innovative educational program designed to immerse middle school students in a hands-on experience of how a community functions. BizTown gives students the chance to step into real-world roles, offering them a glimpse into professions like accounting, teamwork, entrepreneurship, and more.
This past Friday, a group of Simpson | McCrady employees volunteered at Junior Achievement (JA) BizTown, an innovative educational program designed to immerse middle school students in a hands-on experience of how a community functions. BizTown gives students the chance to step into real-world roles, offering them a glimpse into professions like accounting, teamwork, entrepreneurship, and more.
At BizTown, the students take on various roles within a simulated town, complete with a bank, grocery store, town hall, doctor’s office, and many other businesses—each one managed and operated by the students themselves. The program helps them understand not only the roles of employees but also how a town’s economy operates. Students are given two paychecks and a business loan and are tasked with making important financial decisions that impact both their personal lives and the success of their businesses.
Throughout their time, students must decide how to spend their paychecks within the community, making choices between essentials like food (including candy!), household expenses, and even charitable donations. This experience taught them valuable lessons in budgeting, saving, and the consequences of financial decisions.
The event was not only an incredible learning experience for the students but also for the Simpson | McCrady volunteers. It was a fulfilling day for all involved and we thank Junior Achievement for running such a fantastic program.
Volunteers at the Humane Animal Rescue
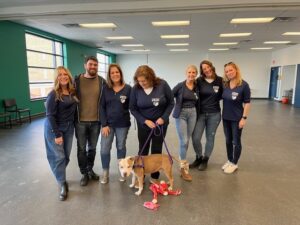
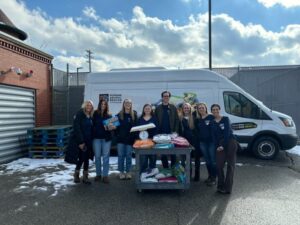
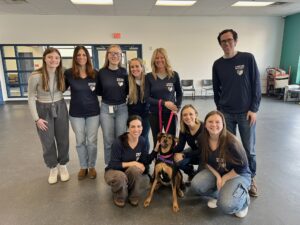
On January 17th and 24th, the Simpson McCrady employees volunteered at the Humane Animal Rescue shelter on the North Side.
On January 17th and 24th, the Simpson McCrady employees volunteered at the Humane Animal Rescue shelter on the North Side. We prepared peanut butter-filled Kongs for the dogs, a nice doggy treat that also, keeps them mentally stimulated, packed cat food into bags for those in need, and organized the supply room to ensure everything is ready for the animals in their care. We also toured the impressive facility and we’re incredibly grateful to the shelter staff and volunteers, for they have such a meaningful impact to these awesome animals! It was a rewarding volunteer experience.
Hurricane Season In Full Swing: How To Prepare
With Hurricane Milton on its way and set to be the second major storm to strike the region in two weeks, we want to let you know that we’re monitoring the path.
With Hurricane Milton on its way and set to be the second major storm to strike the region in two weeks, we want to let you know that we’re monitoring the path. Here are helpful tips to help prepare before it makes landfall:
We encourage you to track the storm’s latest location and keep up to date by following The Weather Channel.
In addition, below is a reminder of some basic precautionary measures you and your family can take:
- Make sure your mobile devices (phone, iPad, hot spot, etc.) and backup battery packs are fully charged. Make sure that you grab the charging cables as well if you are evacuating in preparation.
- Know your evacuation route. Cities at risk of a hurricane have emergency evacuation plans that take members of the community to the safest inland town. Ensure you and your family members know how to get to the appropriate route and take note of alternate routes that may be available if storm debris prevents you from getting to the evacuation highway safely.
- Protect your home from wind and debris. Move all plants, outdoor furniture, and any other free-standing items indoors to a garage or basement.
- Move vehicles to higher ground. If you need to evacuate, move left-behind vehicles to higher ground or a parking garage if you have access, not under trees or power lines.
- Gather important documents in one place. Store important documents, such as legal papers, birth certificates, marriage licenses, financial papers, and insurance policy information, in a waterproof, portable safe that is easy to transport in an evacuation.
- Refill your prescriptions. You can refill prescription medications in advance for at least a 30-day supply if you live in a county under a hurricane warning by the NWS, under a State of Emergency issued by the Governor, or one with an activated emergency operations center.
- Don’t forget tornadoes. Tornadoes can be a hurricane threat, especially if you live inland. Read over what to do in a tornado to prepare for the fast-forming and unpredictable storms.
We hope this overview proves helpful–and that you and your family remain safe and sound amid the storm. But if you do you need help with a claim or have any questions after the storm hits, do not hesitate to reach out. We’re here to help.
Gardening with Michelle
Simpson | McCrady is grateful for all the volunteers who helped make our second annual Gardening with Michelle at Phipps a beautiful day. Michelle will always be a part of our Simpson | McCrady family.
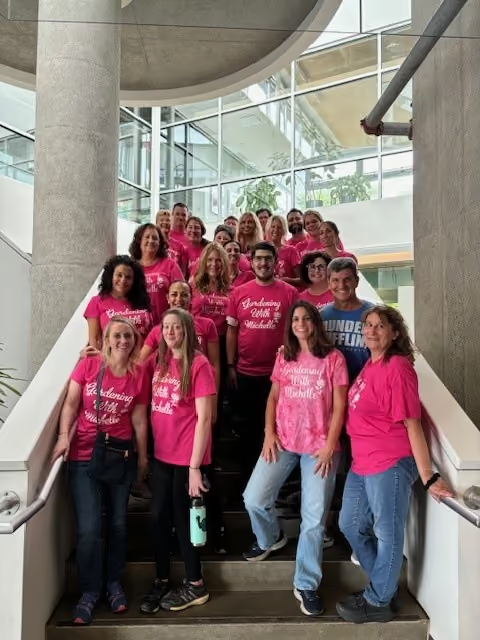
Simpson | McCrady is grateful for all the volunteers who helped make our second annual Gardening with Michelle at Phipps a beautiful day. Michelle will always be a part of our Simpson | McCrady family. Her birthday is right around this time, so we pay tribute to her wearing her favorite color, pink, while gardening, which was one of her favorite activities. We walked into Phipps under somber skies, and as we gardened, the clouds parted, and the sun came out with warm memories of Michelle.
Thank you again for your effort in lending a hand and making it a great day.
Browse by Audience
Find the Insights Built for You
Private Client Insights
Complex personal insurance deserves clear, specific guidance, not a generic overview. Our private client resources cover fine art, jewelry, multiple properties, recreational vehicles, cyber liability, and the full range of coverage considerations for high-net-worth families and family offices. Written by advisors who work in this space daily, with the depth our clients tell us they don't find anywhere else.
Commercial Insights
Risk and benefits intelligence written for business owners and decision-makers, not for a general audience. From technology and manufacturing to professional services and non-profits, our commercial resources address the insurance and risk challenges facing middle-market companies across Western PA and the Mid-Atlantic region, grounded in the industries we actually serve.
Explore More Resources
Ready to Go Deeper?
An article is where understanding starts. Our case studies show how we've protected real clients (families and businesses who faced specific, consequential risks), and our advisor profiles put a name, background, and specialty behind every perspective you've read here. When you're ready to talk through your own situation, the path forward is direct.
The People
Meet the Advisors Behind the Guidance
Named advisors, not call centers. See who wrote the perspectives in this library and what each of them specializes in.
The Proof
Read Our Client Case Studies
Real families and businesses, specific consequential risks, and the outcomes our advocacy produced.
The Services
Explore the Practices Behind the Perspectives
Two practices, one standard of counsel, for your family's assets or your company's operations.