
Insights & News
Perspectives on Risk, Wealth & What Matters Most
Advisor guidance for private clients and business owners, alongside news from the firm.
Everything we publish now lives in one library: articles, market commentaries, firm news, and community stories. Filter by Insights or News, then browse what matters to you.
Featured Content Spotlight
Selected by Our Advisors
Every piece in this row was hand-picked, not auto-populated, because it addresses something our advisors are actively discussing with clients right now. Whether that's a timely market commentary, a new case study, or a deep-dive into a risk category affecting your family or your business, these are the perspectives worth your attention today.
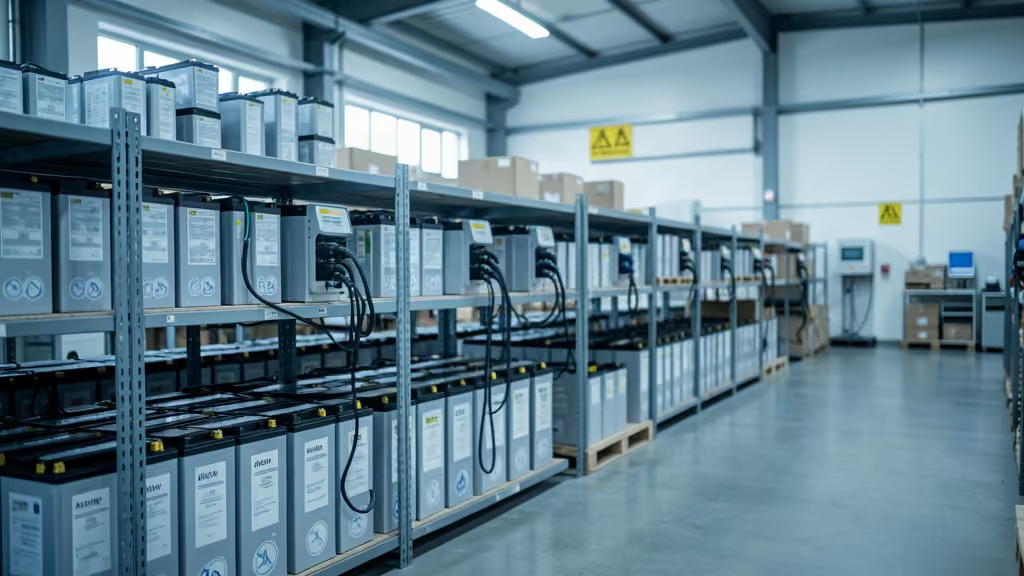
Lithium-Ion Battery Handling & Storage
A best-practice guideline for preparing your facility or home for the safe use and storage of lithium-ion batteries and energy storage systems: how and why cells fail, the fast-shifting regulatory and liability landscape, and configuration-specific controls from a charging bench to a container-scale system.
A best-practice guideline for preparing your facility or home for the safe use and storage of batteries and energy storage systems.
The Growing Risk
Lithium-ion (Li-ion) and lithium-polymer (Li-Po) batteries now power nearly every corner of modern operations: cordless tools and equipment, material-handling fleets, electric vehicles, micro-mobility devices, and the large stationary energy storage systems (ESS) that stabilize power supply and support renewable generation. Their high energy density, long service life, and fast recharging have made them the default choice. Those same qualities, however, concentrate a great deal of energy into a small, chemically reactive package. When a Li-ion battery is defective, damaged, poorly stored, or improperly charged, it can fail violently, releasing intense heat, toxic gas, and a self-sustaining fire that conventional extinguishers struggle to control.
The scale of the exposure is growing with adoption. Since the start of 2025 alone, the U.S. Consumer Product Safety Commission has issued 46 recalls and safety warnings for consumer products powered by lithium-ion batteries, and several high-profile facility fires have reshaped how regulators, fire officials, and insurers view the hazard. For any organization that uses, charges, or stores these batteries in more than trivial quantities, the question is no longer whether to manage the risk, but how thoroughly.
This guideline is a practical roadmap for our clients. It explains how and why these batteries fail, summarizes the emerging legal and regulatory landscape, and lays out configuration-specific best practices for preparing your facility, from a handful of tool batteries on a charging bench to a container-scale energy storage system.
Understanding the Risk
How lithium-ion batteries fail: thermal runaway
Nearly every serious Li-ion incident traces back to a single phenomenon: thermal runaway. It begins when one cell generates more heat than it can dissipate, often because of an internal short from a manufacturing defect, physical damage such as a puncture or crush, overcharging, deep discharge, or exposure to excessive heat. As the cell heats, it ignites its own flammable electrolyte; that heat spreads to adjacent cells, which fail in turn, producing a self-reinforcing chain reaction. Because the reaction generates its own oxygen, these fires are difficult to extinguish, can reignite hours later, and react violently with water where lithium metal is present.
Critically, failure does not happen all at once. It escalates through recognizable stages, and the earlier the failure is detected, the more options remain to intervene.

Beyond fire: toxic and environmental exposure
Li-ion fires are not only a combustion hazard. Burning cells release highly toxic gases, including hydrogen fluoride (HF) and per- and polyfluoroalkyl substances (PFAS, the persistent “forever chemicals”), that can injure the eyes, skin, and respiratory system and require evacuation. Water used to fight a battery fire can become contaminated with heavy metals such as cobalt, nickel, copper, and manganese, creating a risk of soil and groundwater pollution if it is not contained. After the January 2025 Moss Landing energy storage fire in California, which destroyed roughly 55,000 battery modules, EPA soil sampling detected several of these heavy metals at levels exceeding screening standards in the surrounding area.
The emerging legal and regulatory landscape
The regulatory picture is shifting quickly, and it increasingly reaches organizations that merely handle batteries rather than manufacture them. In May 2023, the EPA advised that most lithium-ion batteries on the market today are likely to qualify as hazardous waste under the Resource Conservation and Recovery Act (RCRA) based on their ignitability and reactivity. The agency is now developing a dedicated “universal waste” category for lithium batteries, with a proposed rule anticipated in 2026 and a final rule expected in 2027. At the state level, Extended Producer Responsibility (EPR) programs are expanding. Illinois requirements took effect January 1, 2026, and California has enacted both stewardship-plan obligations (AB 2440) and a point-of-sale recycling fee (SB 1215). Meanwhile, some states impose stricter hazardous-waste thresholds than the federal baseline.
The liability exposure is equally significant. Under the federal Superfund statute (CERCLA), cleanup liability is strict, joint-and-several, and retroactive: facility owners and operators, parties that arrange for disposal or recycling, and transporters can all be named, and even sending a small volume of defective cells to a contaminated site can expose a company to a share of the full cleanup cost. Following Moss Landing, the operator entered a CERCLA settlement in July 2025 to fund a cleanup expected to take two or more years. Organizations once considered removed from battery operations, such as auto dealerships handling EV batteries or retailers managing consumer returns, can now trigger hazardous-waste obligations, and California penalties can reach tens of thousands of dollars per day, with criminal exposure for knowing violations.

Foundations: Selection, Inspection, and Built-In Safeguards
Buy quality; avoid counterfeits
The single most effective way to reduce battery risk is to keep defective cells out of your facility in the first place. Purchase tools, equipment, and batteries from reputable manufacturers whose products are certified to the applicable Underwriters Laboratories (UL) standards, and buy replacement batteries and chargers only from the original equipment manufacturer (OEM) or its authorized vendors. Counterfeit and aftermarket batteries frequently omit the internal safeguards that protect genuine cells and are a leading contributor to failures. Where your application allows, consider lithium iron phosphate (LFP / LiFePO₄) cells, a Li-ion chemistry known for greater thermal stability and lower susceptibility to thermal runaway.
Inspect on arrival and before every use
Establish a quality-control step so a designated employee inspects new batteries on delivery, and personnel check batteries before each use. Remove from service, and dispose of properly, any battery showing bulging or swelling; cracked, broken, or discolored casings; excessive heat during charging or use; hissing; leaking; or smoke or unusual odors. Multimeters and digital or infrared thermometers support periodic, documented health checks. Keep a Safety Data Sheet (SDS) on file for every battery on site; these drive correct storage, handling, and emergency response.
Rely on built-in protections, but not on them alone
Quality Li-ion batteries include layered safeguards: a separator that shuts down ion flow as temperature rises, a pressure-relief vent, thermal interrupts and fuses, overcharge and short-circuit protection, temperature sensors, cell balancing, and a Battery Management System (BMS) that monitors state of charge, temperature, and cell health and can disconnect the pack when it detects an anomaly. These features reduce risk but do not eliminate it; facility controls remain essential.
Preparing Your Facility by Configuration
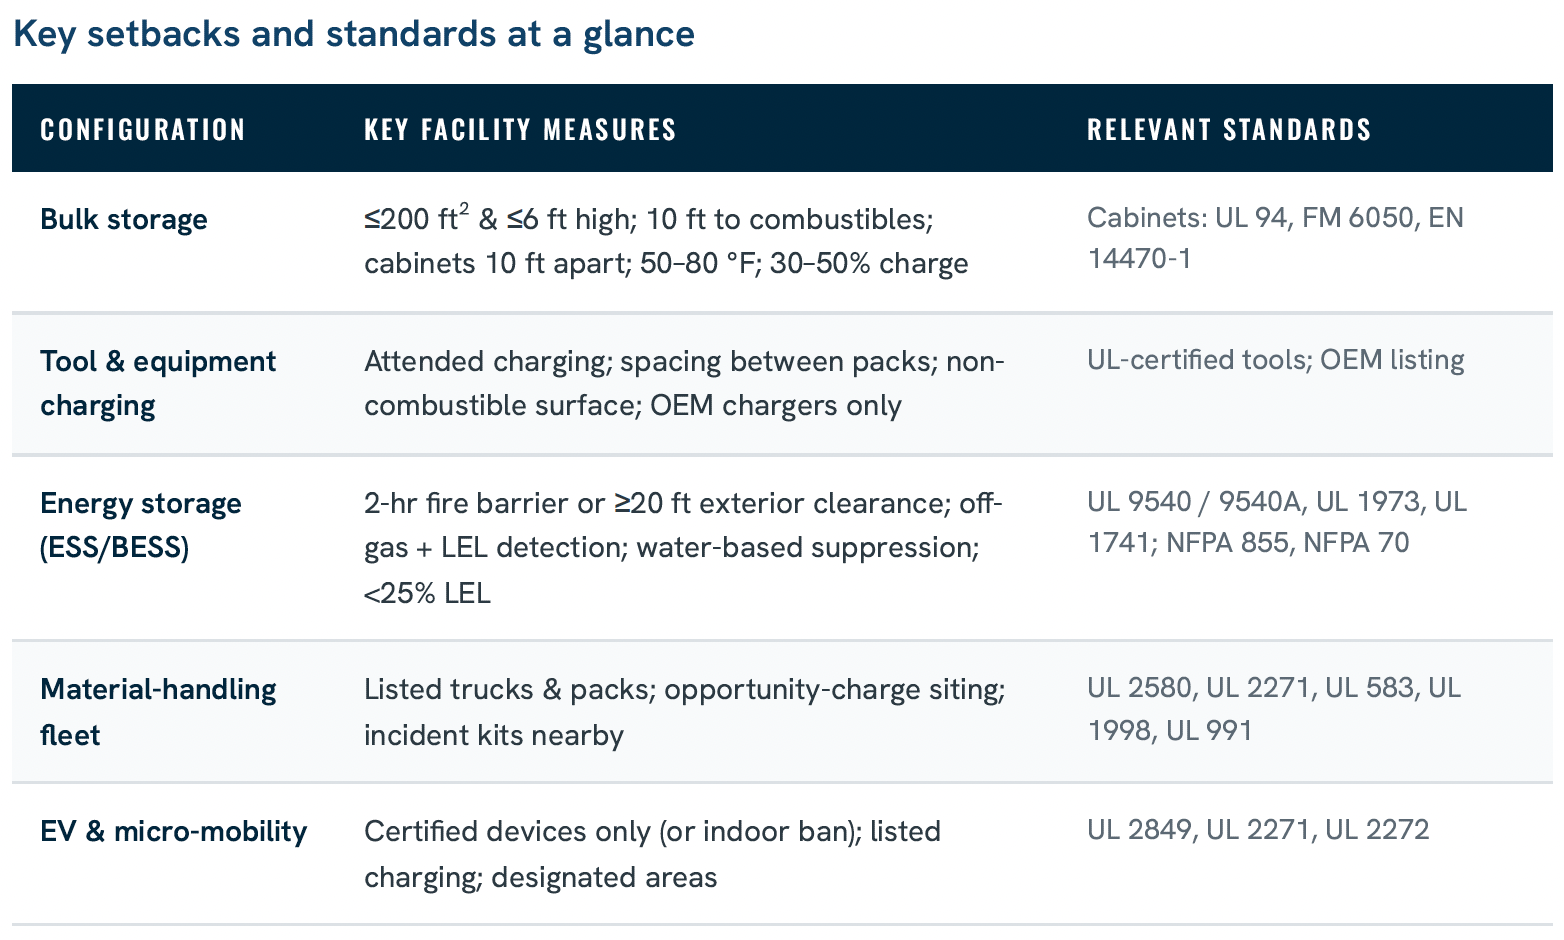
The right controls depend on how batteries are used and stored. The practices below address the configurations our clients most commonly operate; a summary of key setbacks and standards appears in the table at the end of this section.
General and bulk storage
- Designate a single, controlled storage location for all Li-ion and Li-Po batteries: well-ventilated, dry, free of combustible materials, out of direct sunlight, and held at a manufacturer-appropriate temperature, generally about 50–80 °F (10–27 °C).
- For longer-term storage, keep cells at roughly a 30–50% state of charge rather than fully charged, and store only the minimum quantity needed; batteries packed closely together raise the risk that one failing cell will cascade to its neighbors.
- For larger volumes, keep quantities in high-hazard sprinklered areas incidental, limiting the battery footprint to about 200 ft² (20 m²) and 6 ft (1.8 m) in height, with roughly 10 ft (3 m) of open space to other stock and combustibles. Even a single pallet of Li-ion batteries can spread fire quickly, so consider relocating bulk quantities outdoors, to a temperature-controlled container, or to a dedicated fire-rated cabinet.
- Purpose-built Li-ion cabinets should be non-combustible (steel), fire-rated (commonly 90–120 minutes, to standards such as UL 94, FM 6050, or EN 14470-1), ventilated, fitted with pressure-relief/explosion venting and spill containment, lockable, and clearly labeled (for example, “Lithium-Ion Battery Storage: Fire Risk”); space multiple cabinets about 10 ft (3 m) apart.
- Bulk warehouse storage warrants a fire-protection engineering review, as it often requires segregated areas, in-rack sprinklers, higher ceiling sprinkler densities, and a strong water supply. Keep an ABC or Class D extinguisher (per the SDS) in the storage area.
Charging stations for tools and equipment
Most tool-battery incidents occur during charging. To avoid this:
- Charge only with the manufacturer-specified charger for that battery; never mix chargers and batteries across brands or use aftermarket chargers, which can defeat built-in protections. Locate charging on a non-combustible surface, away from egress routes and combustible storage, with space maintained between charging batteries.
- Charge only while personnel are present; do not charge unattended or overnight. Remove batteries from the charger once charged, allow hot batteries to cool before charging, and use charging bags or fire-rated charging cabinets where practical.
- Post charging and storage instructions at the station.
Energy storage systems (ESS / BESS)
Stationary energy storage introduces the largest concentration of stored energy on many sites and warrants a design-led approach. New systems should be certified to UL 9540 (Energy Storage Systems and Equipment) and evaluated using the UL 9540A test method, which characterizes thermal-runaway fire propagation and informs required spacing, ventilation, and fire protection; battery units should be UL 1973-listed and inverters UL 1741-certified. Installations should follow NFPA 855 (Installation of Stationary Energy Storage Systems) and NFPA 70 (Article 706). For further continuity:
- Detection is the linchpin. Off-gas monitoring detects electrolyte vapor at the earliest stage and can initiate an automatic shutdown and alarm before smoke or fire, while lower-explosive-limit (LEL) gas detection should be interlocked with ventilation to keep any flammable atmosphere below 25% LEL.
- For suppression, note that clean-agent gas systems generally will not stop a thermal-runaway fire; water-based protection is preferred (a wet-pipe sprinkler system, or an open-head deluge with a fire-department connection for container installations), with sprinkler density designed to at least Extra Hazard Group 1.
- Site ESS in a non-combustible, locked enclosure separated from the rest of the building by a two-hour fire barrier, or outdoors; keep exterior containers at least 20 ft from buildings unless rated thermal barriers are provided, and ensure the room is externally accessible for manual firefighting.
- Round out the design with supervised smoke detection, temperature monitoring with high-temperature alarms, coolant-leak detection, seismic bracing where required, emergency power disconnects, and clear signage. Because ESS are network-connected, incorporate cybersecurity into the BMS and firmware, and commission larger or custom systems with a qualified agent under a formal operations-and-maintenance program with online condition monitoring.
Material-handling equipment (forklifts and pallet jacks)
Electric material-handling fleets increasingly use Li-ion packs with decentralized “opportunity charging” throughout the operation. System best practices for this equipment include:
- Specify batteries and trucks listed to the relevant standards: UL 2580 for Class 1 and 2 forklifts, UL 2271 or UL 2580 for Class 3 pallet jacks, with UL 583 for the trucks and UL 1998 / UL 991 covering safety software and controls.
- Site opportunity-charging points on non-combustible surfaces, away from combustible storage.
- Report any physical damage to a battery or its enclosure immediately, and keep incident-response kits (fire blankets, gloves, non-combustible containment drums, and appropriate suppression media) near the equipment.
Electric vehicles and micro-mobility
E-bikes, e-scooters, and hoverboards are a frequent source of facility fires, and many jurisdictions now regulate them; in New York City, for example, e-bikes must be certified to UL 2849. As such, it is recommended that a policy be adopted that outlines the following:
- Either ban personal devices indoors, or allow only certified ones (UL 2849 / 2271 / 2272).
- Charge EVs with listed equipment installed by a qualified electrician, away from exits.
Emergency Response and Incident Readiness
Even well-run facilities should plan for failure. Build a written emergency response plan around the principle that early action and fast evacuation save lives and property. It is heavily recommended that the local fire department be contacted and made aware of the type, configuration, and location of battery systems within your facility. Having their insight and input into the development of your emergency response plan is vital.
Detection and isolation. Train staff to recognize the early signs (unusual odor, discoloration, swelling, excessive heat, hissing, or smoke) and, only if it is safe to do so, to move a suspect battery away from combustibles into a fire-rated isolation container. Keep a pail of sand nearby as a smothering agent.
Small, incipient fires. Because battery fires emit toxic fumes, all untrained personnel should evacuate immediately. Only personnel specifically trained to fight small battery fires should attempt to do so, positioned between the fire and the nearest exit; if the extinguisher is ineffective, smoke becomes heavy, or the responder is at all uncomfortable, they should evacuate. If flames are subdued, submerge the battery in sand or douse with water as directed by the SDS; sand is the safer choice where lithium metal may be present.
Thermal runaway and large fires. No one should attempt to fight a thermal-runaway or large-scale fire. Activate the alarm, evacuate the building, and call emergency services, providing the battery type and size, the location, and any hazardous materials present, and hand the relevant SDS to responders when possible.
First aid. For eye or skin exposure, flush with water for at least 15 minutes and seek medical attention; move anyone exposed to fumes or smoke into fresh air and administer first aid or CPR as needed. Because effects can be delayed, exposed individuals should be evaluated by a medical professional.
Disposal and cleanup. Never place Li-ion batteries in general waste; route them to a certified recycler, and store damaged units awaiting pickup in a non-combustible container located about 25 ft (8 m) from occupied buildings. Provide containment or retention basins to capture contaminated firefighting water, consistent with the environmental exposures described earlier.
2026 Personal Insurance and Risk Management Trends in Private Client Services
A Comprehensive Analysis of Emerging Risks, Market Dynamics, and Strategic Solutions for High-Net-Worth Individuals The private client insurance landscape is experiencing unprecedented transformation driven by converging forces: escalating climate-related catastrophes, explosive cyber threats, nuclear verdict litigation trends, and the largest intergenerational wealth transfer in history.
A Comprehensive Analysis of Emerging Risks, Market Dynamics, and Strategic Solutions for High-Net-Worth Individuals
The private client insurance landscape is experiencing unprecedented transformation driven by converging forces: escalating climate-related catastrophes, explosive cyber threats, nuclear verdict litigation trends, and the largest intergenerational wealth transfer in history. As we enter 2026, high-net-worth (HNW) individuals and families face a fundamentally different risk environment than existed even five years ago.
Key findings include:
- Climate-driven property insurance costs rose 10.4% nationally in 2024, with catastrophe losses reaching $176 billion
- Personal cyber risk exposure exploded 3,000% for deepfake fraud, with average U.S. breach costs exceeding $10.22 million
- Nuclear verdicts ($10M+) median awards reached $23.8M in 2023, creating liability insurance crises
- Baby boomers control $19.7 trillion in real estate (41% of U.S. total), creating complex transfer challenges
- Protection gaps widened significantly, with only 47% of catastrophe losses insured in 2024
For private clients, their advisors, and family offices, 2026 demands proactive risk management strategies addressing these interconnected exposures while navigating an increasingly complex insurance marketplace.
The Evolving High-Net-Worth Risk Landscape
Baby boomers control $19.7 trillion in U.S. real estate—41% of total value despite representing only 20% of the population[1]. This concentration, combined with aging properties and intensifying climate risks, creates unprecedented insurance challenges.
High-net-worth individuals face converging exposures: multiple properties across catastrophe-prone regions, valuable collections requiring specialized coverage, elevated liability risks from social inflation, complex estate structures demanding policy coordination, and growing cyber vulnerability as digital wealth management expands.
The insurance protection gap has widened dramatically. In 2024, U.S. catastrophe economic losses reached $176 billion while insured losses totaled only $99 billion—a $77 billion protection gap[2]. For private clients, this reflects underinsurance from rapid property appreciation, coverage exclusions for flood and earth movement, policy sub-limits, increasing carrier restrictions in high-risk areas, and, in some cases, the choice to self-insure.
1. Climate Change and Property Insurance Crisis
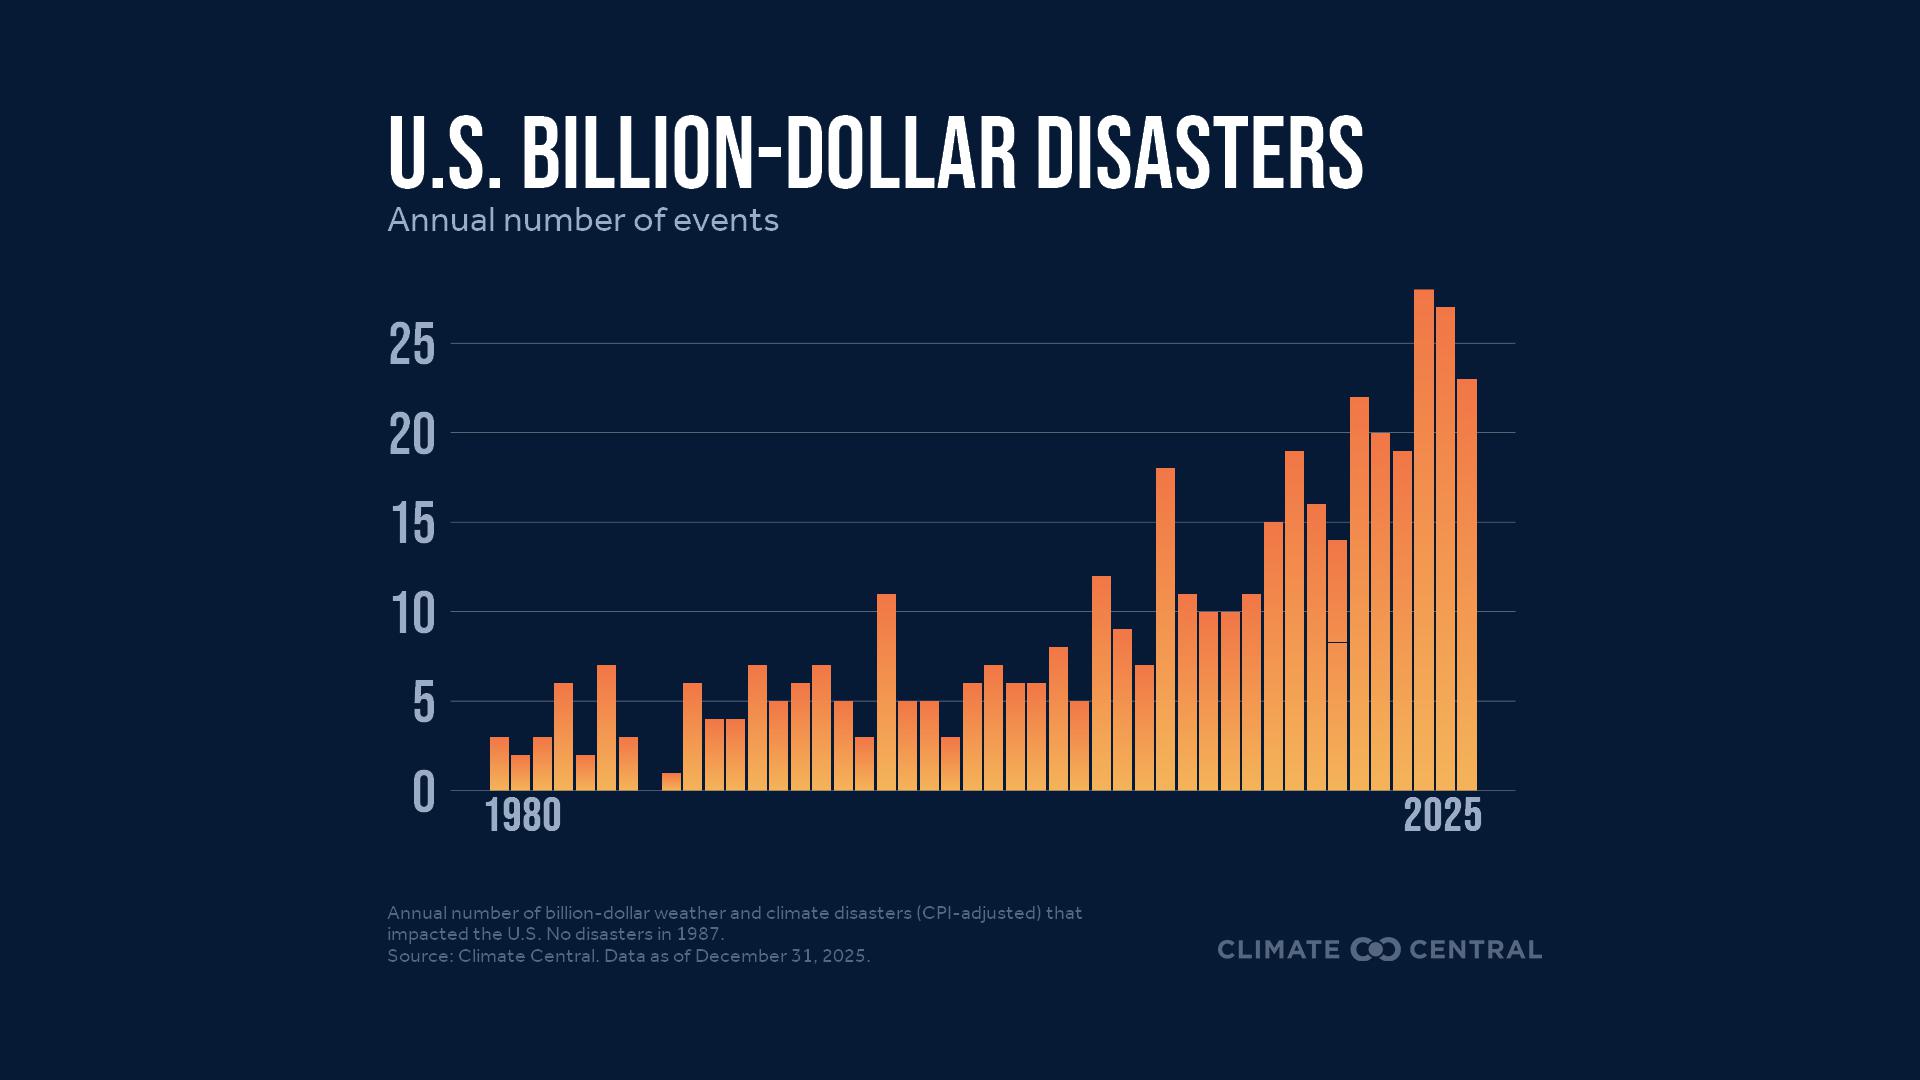
The year 2025 marked the fourth-warmest on record for the United States, with 27 weather disasters exceeding $1 billion in losses each[3]. Notable events included the Eaton and Palisades Fires destroying 18,000+ structures in Southern California, Texas Hill Country’s 1-in-1,000 year flood killing 135 people, and 1,559 tornado reports—fifth-highest on record[3].
Sea level rise has doubled from .06 inches to .14 inches annually, creating 3-9 times more frequent coastal flooding than 50 years ago[4]. Combined with accelerating drought (42.8% of U.S. affected per US Drought Monitor), these trends fundamentally reshape property insurability.[4]
Insurance Market Response:
Homeowners insurance rates increased 10.4% nationally in 2024, with six states exceeding 20%[5]. Major carriers withdrew from California, Florida, and Louisiana, forcing reliance on surplus lines (up 31.2% to $5 billion) and residual markets (up 6% to $10 billion)[5]. Carriers implemented percentage-based wind/hail deductibles, roof age restrictions, and tightened underwriting standards.
For HNW clients with multiple high-value properties, this creates acute challenges: limited carrier options, higher premiums, broader exclusions, and potential uninsurability in catastrophe-prone coastal and wildfire zones where many retirement properties are concentrated.
How to address:
Home Resiliency
- Prioritize loss‑prevention tools as these steps can improve insurance options and potentially reduce premiums:
- Water leak detection and automatic shutoff systems
Whole home backup generators
Annual or seasonal maintenance checklists to address minor issues before they become major
Coverage Options
Review your policy for exposures such as flood, earthquake, and sinkhole to determine whether adding these coverages makes sense based on where your home is located.
Acquisitions
- Consult your advisor before making an offer—especially for out of town or out of state home purchases. This helps you ask your realtor the right questions, improve insurability, manage long term costs and make educated buying decisions.
- Consolidating coverage with one carrier can enhance program efficiency, improve eligibility for better coverage, and ensure consistency across policies to prevent gaps or overlaps in coverage.
2. The Cyber Threat to Personal Wealth
Escalating Personal Cyber Threats
Ransomware Evolution
Ransomware was involved in 44% of all data breaches in 2024, with attacks shifting to “double extortion”—stealing personal financial records, tax returns, estate documents, and smart home data before encrypting systems and threatening public release[7].
The Deepfake Epidemic
AI-generated deepfakes exploded 3,000% in 2025, enabling unprecedented fraud targeting wealthy individuals[9]:
- Voice cloning of family members requesting urgent wire transfers
- Video impersonations of financial advisors authorizing transactions
- Synthetic identity creation for account takeovers
- AI-enhanced phishing with 54% success rates—quadruple traditional methods[10]
Shadow AI Risks
Household staff and family members using unauthorized AI tools (ChatGPT, Claude) for convenience create data leakage risks as personal information may be retained and exposed.
Cyber Risk Management Best Practices
Private clients should implement layered cyber defenses:
Technical Controls
- Multi-Factor Authentication (MFA): Strongly recommended for all financial accounts, email, cloud storage.
- Endpoint Detection & Response (EDR): Advanced antivirus/anti-malware on all devices
- Network Segmentation: Separate IoT/smart home devices from financial/personal computing
- VPN Usage: Virtual private networks for all remote/travel internet connections
Interactive Best Practices
- Wire Transfer Protocols: Verbal confirmation of all wire instructions via known phone numbers
- Email Authentication: Training to identify phishing, suspicious links, urgency-based manipulation
- Social Media Privacy: Limit disclosure of travel, property locations, purchases, family information
Coverage Coordination
- Review homeowners for any cyber coverage endorsements and what limits are available.
- Coordinate with any business cyber policies if working from home.
- Understand what is and isn’t covered.
3. Nuclear Verdicts and Liability Crisis
Nuclear verdicts—jury awards exceeding $10 million—have escalated dramatically. Analysis of 1,288 verdicts from 2013-2022 reveals median awards reaching $23.8 million in 2023 (up from $21.1 million), with mega verdicts ($100M+) increasing 400% since 2013[14].
Florida leads with 0.939 verdicts per 100,000 people—50% higher than New York. California, Florida, New York, and Texas produce half of all national nuclear verdicts[15]. State courts host 90% of verdicts versus only 10% in federal courts.
Critically, noneconomic damages (pain and suffering) drive verdict severity. In seven of ten years, noneconomic damages exceeded punitive damages, demonstrating susceptibility to psychological manipulation including “reptile theory” tactics, anchoring (suggesting arbitrary amounts that double to quadruple awards), and $1 billion in annual lawsuit advertising normalizing extreme awards[16][17][18].
Impacts on Private Clients
A 2025 Georgia jury awarded $4.2 million for a dog attack—far exceeding typical homeowners policy sub-limits of $100,000-500,000[19].
Making sure you have an appropriate umbrella limit is paramount. This limit of coverage is meant to be a moving target that is adjusted as your lifestyle evolves. Have a conversation with your advisor to discuss any significant changes in your net worth and/or public profile. Higher limits are available and we’re here to help.
4. Intergenerational Wealth Transfer Challenges
Baby boomers control $19.7 trillion in real estate, with the boomer population projected to decline 23% by 2035 and another 47% by 2045—transferring enormous holdings to millennial and Gen X heirs[21][22]. However, nearly 40% have lived in current homes 20+ years, with 68% in homes at least 30 years old[23]. Deferred maintenance—aging roofs, HVAC systems, electrical, and plumbing—often requires $50,000-$200,000+ in immediate upgrades inheritors lack funds to complete.
Insurance Complications
When aging parents move to assisted living, standard homeowners policies limit vacant property coverage to 30-60 days, requiring vacant home endorsements (30-50% higher premiums), regular inspections, winterization, and security monitoring. Failure to maintain proper coverage results in claim denials for theft, vandalism, or weather damage.
Post-inheritance, carriers increasingly restrict coverage on older homes through roof age limitations (declining roofs over 15-20 years), four-point inspections, wind mitigation requirements, and wiring restrictions. Inheritors may discover properties uninsurable without significant investment.
Multiple heirs create additional complications: disagreement on disposition, unequal contribution ability, mortgage difficulties, and liability exposure when one heir is judgment-proof while another has assets.
Many boomers retired to Sunbelt locations—Florida, California, Texas, Louisiana, Arizona—now facing acute climate risks. Millennial inheritors discover properties in locations they don’t want with deteriorating insurance availability. [26].
Avoiding Underinsurance (and Overinsurance)
- Choose carriers that use in home appraisals, apply annual inflation guards, and offer guaranteed or extended replacement cost. These protections help maintain proper insurance to value.
- If you haven’t appraised your fine art, jewelry, or collectibles in 3–5 years, schedule an updated review. Rising precious metal values mean some items may now be underinsured, while others may not require as much coverage and should be reduced which would provide a premium savings.
Asset Transfer Guidance
- Speak with your advisor before transferring assets to ensure proper risk management and insurance planning.
- Advisors can help prepare the next generation with education, loss prevention strategies, and insurance guidance.
- Homes: Discuss improvements that enhance home resiliency and insurability.
- Jewelry, fine art, wine/spirits: Review loss likelihood and proper insurance and risk management approaches.
- Middle market carriers often won’t insure high value items, or, in some cases, charge more for inadequate coverage.
- Asset transfers often indicate that the next generation needs a more sophisticated, high net worth insurance program.
- Working with a private client insurance advisor ensures proper coverage, carrier selection, and expert guidance.
2026 Market Outlook
The private client insurance landscape of 2026 is characterized by converging mega-trends which interact and compound and the need to adjust accordingly is evident.
Property insurance faces continued volatility with national average increases projected 8-12% for homeowners, and 15-25% on average in catastrophe-prone states (FL, CA, TX, LA).
Percentage-based wind/hail deductibles expand beyond coastal zones, roof age limitations tighten to 15-year maximums, and carriers reduce willingness to write vacant or secondary homes. However, reinsurance rates declined 6.6% at January 2025 renewals, bringing modest relief.
Personal cyber policies are becoming a standard need for all clients, with limits increasing in response to the increasing risk.
Umbrella/excess liability premium increases moderate to 5-10% in 2026 after prior 15-30% spikes. There is additional underwriting scrutiny on driver records, property maintenance, dog breeds, and water features.
Conclusion
As the private client insurance environment undergoes rapid and profound change, high net worth individuals face a level of complexity and exposure unlike any previous era.
Climate driven property volatility, surging cyber threats, escalating liability awards, and the massive transfer of aging assets across generations are reshaping both risk and insurability.
In this landscape, protection gaps widen quickly, traditional carriers offer fewer solutions, and the costs of inaction grow exponentially. The path forward requires proactive planning—strengthening property resiliency, modernizing cyber defenses, securing adequate liability protection, and preparing heirs with the right education and insurance structures.
By partnering with skilled private client advisors and adopting a coordinated risk management strategy, families can safeguard wealth, maintain insurability, and navigate the evolving challenges of 2026 and beyond with confidence.
We invite you to reach out with any questions as we’re here to provide recommendations, information and guidance.
Interested in learning more? Check out our Insights page for other relevant education topics.
References
[1] Redfin analysis (2025). Baby boomer real estate holdings. Business Insider.
[2] National Association of Insurance Commissioners. (2025). Natural Catastrophe Risk Dashboard Report, December 31, 2024.
[3] National Centers for Environmental Information (NCEI). (2025). Assessing the U.S. Temperature and Precipitation Analysis in 2025. NOAA.
[4] NOAA Climate.gov. (2025). Sea level change data. National Oceanic and Atmospheric Administration.
Climate Change: Global Sea Level | NOAA Climate.gov
Monthly Climate Reports | Drought Report | December 2025 | National Centers for Environmental Information (NCEI)
[5] National Association of Insurance Commissioners. (2025). Homeowners loss ratio and P&C combined ratio data. Natural Catastrophe Risk Dashboard Report. Natural Catastrophe Risk Dashboard Report.pdf
[6] Khalil, M. (2025, December 3). Cyber Insurance Statistics 2025: Key Trends & Data. DeepStrike. https://deepstrike.io/blog/cyber-insurance-statistics-2025
[7] Khalil, M. (2025). Ransomware involvement in data breaches. Cyber Insurance Statistics 2025. DeepStrike.
[8] Khalil, M. (2025). Ransom demand and payment dynamics. Cyber Insurance Statistics 2025. DeepStrike.
[9] Khalil, M. (2025). Deepfake fraud statistics. Cyber Insurance Statistics 2025. DeepStrike.
[10] Khalil, M. (2025). AI-enhanced phishing success rates. Cyber Insurance Statistics 2025. DeepStrike.
[11] Khalil, M. (2025). Business email compromise claim statistics. Cyber Insurance Statistics 2025. DeepStrike.
[12] IBM Security. (2025). Cost of a Data Breach Report 2025. Cited in DeepStrike Cyber Insurance Statistics 2025.
[13] IBM Security. (2025). AI and automation impact on breach costs. Cost of a Data Breach Report 2025.
[14] Silverman, C., & Appel, C. E. (2024, May). Nuclear Verdicts: An Update on Trends, Causes, and Solutions. U.S. Chamber of Commerce Institute for Legal Reform.
[15] Silverman, C., & Appel, C. E. (2024). Top states for nuclear verdicts analysis. Nuclear Verdicts Report. Institute for Legal Reform.
[16] Silverman, C., & Appel, C. E. (2024). Economic vs. noneconomic damage composition. Nuclear Verdicts Report. Institute for Legal Reform.
[17] Silverman, C., & Appel, C. E. (2024). Anchoring tactics driving nuclear verdicts. Nuclear Verdicts Report. Institute for Legal Reform.
[18] Silverman, C., & Appel, C. E. (2024). Lawsuit advertising impact on verdicts. Nuclear Verdicts Report. Institute for Legal Reform.
[19] PropertyCasualty360. (2025, April 16). Georgia jury awards elderly woman $4.2M for dog attack. https://www.propertycasualty360.com/2025/04/16/georgia-jury-awards-elderly-woman-42m-for-dog-attack/
[20] TransRe. (2024). Medical malpractice verdict analysis. Cited in Institute for Legal Reform Nuclear Verdicts Report.
[21] National Association of Realtors. (2024). Baby boomer real estate ownership analysis. Business Insider.
[22] Harvard Joint Center for Housing Studies. (2024). Baby boomer population decline projections 2025-2045. Business Insider.
[23] Leaf Home & Morning Consult. (2024). Survey of 1,000 baby boomers on home age and maintenance. Business Insider.
[24] Metz, J. (2025). California property tax implications of inheritance. Senior Homeowner Solutions. Business Insider.
[25] Yahoo Finance. (2025). State Farm refused to cover Florida man’s repairs on his Porsche—why the courts are now involved. https://finance.yahoo.com/news/state-farm-refused-cover-florida-095800478.html
[26] Fairweather, D. (2025). Chief Economist commentary on inherited property challenges. Redfin. Business Insider. Boomers are leaving their millennial Children with a huge headache — James Morris Homes
[27] S&P Global Ratings. (2024). Cyber insurance market outlook: Premiums projected to reach US$23 billion by 2026 amid stable industry conditions. Industrial Cyber.
Why you deserve more than a 1-800 number
Why successful and high net worth individuals and families deserve more than a 1-800 number. You’re busy. You juggle multiple calendars. You run a business (or two). You travel (a lot). You have a booked schedule with patients in your waiting room.
Why successful and high net worth individuals and families deserve more than a 1-800 number.
You’re busy. You juggle multiple calendars. You run a business (or two). You travel (a lot). You have a booked schedule with patients in your waiting room.
You have your wealth manager, estate planning attorney, and/or your accountant all in your contact list and know them on a first name basis so you can get quick and to-the-point answers. Shouldn’t your risk management and insurance team be the same?
You deserve an insurance advisor you can actually call.
Request a confidential consultation with a Simpson | McCrady advisor to discuss your current coverage and risk exposures.
Click Here and Request a Consultation
In an evolving agent and advisory landscape, it is becoming more frequent that we have someone come to us describing their previous agency experience with a degradation of service over the years or, in some cases, a complete lack thereof. They’re given a 1-800 number to make policy changes or to call when something goes wrong and they need to file a claim. The agent can’t provide the increased liability limits that they need to protect their net worth or identity and cyber options to protect against an attack. They can’t help with the new secondary home out of state, high end vehicles, growing fine art collection, or provide proper guidance on the increased risks of an in ground pool, in home domestic staff, snow mobiles, ATVs or high performance watercrafts. They lack the sophistication to handle complex risks.
“I don’t even know who my agent is.” This is a phrase we hear more often than not when we speak to someone looking for a change and looking for a better experience.
If your current insurance experience feels impersonal or transactional, it may be time for a different approach.
Schedule a Private a Consultation
We are a boutique firm that specializes in helping successful families and individuals prepare for the “what if’s” in life. We help during stressful times when something goes wrong and guidance or a helping hand is needed. We are a fiercely independent agency that benefits from being small and nimble to pivot and adapt to our client’s needs as they evolve. There is no 1-800 number with us.
At Simpson | McCrady, every client works directly with a dedicated advisory team — not a call center.
Speak with a Trusted Advisor
We represent multiple high net worth and affluent insurance companies so our clients know that they’re getting what’s best for their unique situation and a risk management plan to buffer them from what can be avoided or mitigated up front.
Every client that we serve has a dedicated team in house. We assist with the day to day things like purchasing or selling a vehicle, a new piece of jewelry or piece of artwork. We also assist with more complex discussions like a significant fire loss or automobile accident, artwork or collector vehicles in transit internationally, the purchase of a secondary home in a different state or a significant home renovation. We also address the different risk management discussions that should take place around these topics, the excitement (and anxiety) about a daughter or son getting their driver’s license or heading off to college and what the parents can do to protect them, the unfortunate event of a divorce, or a death in the family and assets that are being transferred to the next generation.
Complex lives require thoughtful risk planning.
Request a Risk & Coverage Review
Our team members are constantly seeking ways to better equip themselves for these evolving conversations with continuing education and earning additional specialty designations. We have numerous team members holding designations for CISR, CIC, CPRIA and CAPI, to name a few, and the list is still growing. Our office is also a proud member of the Private Risk Management Association (PRMA) which is recognized as the forum and voice of the high net-worth private risk and insurance management niche.
If your current insurance relationship feels impersonal — or you’re unsure whether your coverage truly reflects your lifestyle and assets — our advisors are here to help.
If you believe you need a step up from the norm, reach out to discuss our process and how we help clients protect tomorrow, today.
Request a Private Consultation,
call us directly at 412-261-2222, or email us at info@simpson-mccrady.com.
For more resources and information about Simpson | McCrady, check out our Facebook and LinkedIn pages.
Filter and Browse
Find What's Relevant to You
Everything the firm publishes lives here. Start with Insights for advisor guidance on risk and coverage, or News for what our team has been doing across Western PA, then browse by what matters to you.
#supportingeachother #protectingtomorrowtoday #rafflewinnings #givingback
News You Can Use: Trends 2021
We’ve seen quite a few things trending in 2021 from the pandemic and we’re here to help you through those transitions. Whether you’re moving, buying a secondary home, undergoing home renovations, have children moving across the country, or thinking of planning that family vacation (finally!), we’re here to help.
We’ve seen quite a few things trending in 2021 from the pandemic and we’re here to help you through those transitions. Whether you’re moving, buying a secondary home, undergoing home renovations, have children moving across the country, or thinking of planning that family vacation (finally!), we’re here to help.
Service Line Coverage
Service line coverage is available through some of our homeowner carriers and this is a valuable coverage to help in the event of utility line failure outside of the home’s foundation that leads to the street. If it’s not available on your homeowners policy, your service providers also offer this coverage at a nominal cost per month. If you have any questions, please reach out to discuss.
New purchases
Have there been any new jewelry, regular use vehicles, collector vehicles, fine art or other high valued collectibles purchased over the past year? It may be time to revisit your valuable articles coverage limits and/or auto and collector vehicle policies.
Making Moves
If you’re thinking about moving to or in the process of purchasing a coastal home, there are many things to consider. The risk variables significantly differ when comparing a home that is located on a more inland and/or northern state versus one that is further south and/or along the coast line.
Florida, for example, has its own set of challenges with increased insurance costs due to wind and hurricane exposures, an increased need for flood coverage, increased costs to protect your home against these risks and how investing in home upgrades can greatly benefit you in the long run. The more time that we have to help you prepare for a home closing, move or renovation, the better.
Flood Insurance
Whether you’re home or taking some much-needed time away with family, it’s important to protect what your home and belongings. Flooding can happen anywhere at any time. You do not need to live by a body of water to have this be a threat to your home. A microburst storm that causes rapid surface water accumulation can cause just as much damage as a coastal tidal surge. Flooding concerns are on the rise and now would be a good time to discuss. We can help to provide recommendations on things to consider to protect you home from flooding and hurricanes and to make sure that you have proper coverage if something does happen.

Cyber Protection
Cyber security issues continue to be a challenge. It’s hard to ignore the news headlines listing major cyber breaches and identity theft issues on a regular basis. Whether you’d like to discuss what coverage options are available or what you can do to prevent cyber security breaches from happening in the first place, we’re here to help.
Liability Limits
A lot of our clients are taking steps to update their homes and enhance their living space. Whether you’re thinking of enhancing your backyard patio for entertaining or installing a pool or hot tub, another important factor that you should be considering is your current excess liability limit. There are a lot of reasons to readdress your liability limits and we’re here to help you through that process.
Your Private Client Service team is here to help. If you have any questions, please don’t hesitate to reach out.
Pittsburgh Parks Volunteer Day
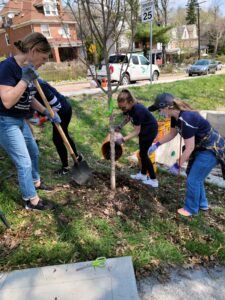
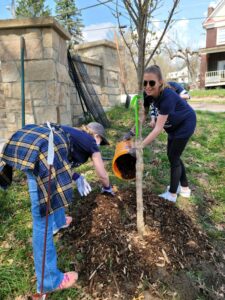
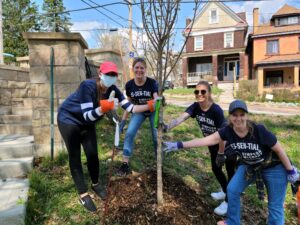
Last month, on April 7th, ten Simpson | McCrady employees joined with the Pittsburgh Parks planting trees and mulching along the entrance and walkways on McKinley Park. They spent a nice spring afternoon helping to beautify one of the many Pittsburgh Parks.
Last month, on April 7th, ten Simpson | McCrady employees joined with the Pittsburgh Parks planting trees and mulching along the entrance and walkways on McKinley Park. They spent a nice spring afternoon helping to beautify one of the many Pittsburgh Parks. We are grateful to have had the opportunity to make a little piece of our city more beautiful.
2021 Trends
It is difficult to pick up a newspaper and not see a headline story related to one disaster or another: from COVID-19 and pandemic related issues to weather related disasters like wildfires, flooding, severe hail storms, tornadoes, or hurricanes; from civil unrest and cyber-attacks to tectonic shifts in the workplace.
It is difficult to pick up a newspaper and not see a headline story related to one disaster or another: from COVID-19 and pandemic related issues to weather related disasters like wildfires, flooding, severe hail storms, tornadoes, or hurricanes; from civil unrest and cyber-attacks to tectonic shifts in the workplace. All of these factors have heavily impacted the insurance industry with an increase in claims frequency and severity.
A few key findings:
- From 2001 to 2018 the number of major weather-related events has increased by 85%[1].
- To highlight 2020 alone:
- It was the second warmest year on record with 2019 right behind it causing significant shifts in weather related issues[2].
- There were seven billion-dollar tropical cyclones which is the most in one year since NOAA started tracking in 1980. The combined cost of these systems was approximately $40.1 billion[3].
- 5 of the 6 largest wildfires in CA occurred[4].
- There were 22 weather and climate disasters. Each exceeded $1 billion in damages, for a grand total of $95 billion[5].
- Material costs have increased across the board in the past ten years and the pandemic has only worsened the situation with supply chain issues and shortages[6].
- Labor costs are up – and that is when you can find an available contractor[7].
- Technology has increased the cost of replacing household appliances and vehicle systems[8].
In Pennsylvania, we have seen a significant increase in the number of severe weather-related claims from hail, snow, wind, and rain storms and flooding.
There has also been a significant increase in claims related to older plumbing systems and/or more complex plumbing systems due to an increased number of conveniences such as multiple bathrooms on each floor, wet bars, kitchenettes, and laundry rooms on upper levels, among other things. This creates more room for errors, leaking pipes, and burst frozen pipes during the colder months. The average cost of a non-weather water loss in our niche market is over $60,000. When you include the actual cost of the damage to your home and belongings, bringing in hygienists, rebuilding to code, and time spent out of your home while repairs are made, these figures can add up very quickly.
There has also been a significant increase in demand for labor and materials. With the pandemic, disruptions in the supply chain have caused significant delays and driven up the cost of repairs and replacements, and pushed out project completion dates[9].
As a result of these trends and factors, carriers have pulled out altogether or reduced capacity in severely impacted states such as CA and FL[10]. Many carriers have been forced to take rate and/or restructure their credit system in order to avoid pulling out of certain market places altogether[11]. Many will reward clients who install risk mitigation features such as a water leak detection shutoff device and are taking proactive measures to keep their home systems up to date. Increasing your deductibles and paying in full can also provide advantages to you annually.
With delays in delivery of mail through the USPS[12], we urge clients to consider making payments electronically or setting up their accounts for automatic payment through EFT and to also take proactive measures to improve their cyber posture[13] to safeguard against the increase in cyber-attacks.
The pandemic has brought additional shifts in our daily lives as we have all been searching for our silver linings and what we want or need right now. Many clients have bought secondary homes or moved to their secondary home while leaving their main home empty or rented out. Some have moved out of more urban areas into more suburban or rural areas or to a different, more affordable urban area. Others that have remained in their primary home or condo have done renovations to enhance their living space. Many have refinanced their mortgages.
If any of these have happened or are on the horizon for you, please reach out so we can discuss. These are all points where we will want to provide risk management guidance, arm you with information you should consider in the decision-making process and recalibrate your program along the way.
We are here for you to help in protecting tomorrow, today.
Sources:
[1] https://www.chubb.com/content/dam/aem-chubb-global/amc/pdf/Market%20Trends%202021%20Key%20Facts.pdf
[2] https://www.noaa.gov/news/2020-was-earth-s-2nd-hottest-year-just-behind-2016
[3] https://www.noaa.gov/stories/record-number-of-billion-dollar-disasters-struck-us-in-2020
[4] https://www.noaa.gov/stories/record-number-of-billion-dollar-disasters-struck-us-in-2020
[5] https://www.noaa.gov/stories/record-number-of-billion-dollar-disasters-struck-us-in-2020
[6] https://www.chubb.com/content/dam/aem-chubb-global/amc/pdf/Market%20Trends%202021%20Key%20Facts.pdf
[7] Chubb.com
[8] https://www.chubb.com/content/dam/aem-chubb-global/amc/pdf/Market%20Trends%202021%20Key%20Facts.pdf
[9] https://www.inquirer.com/real-estate/housing/new-home-construction-single-family-builders-pennsylvania-20210224.html & https://www.inquirer.com/real-estate/housing/lumber-prices-home-construction-20210128.html
[10] https://www.marketplace.org/2020/08/31/insurance-increasingly-unaffordable-as-climate-change-brings-more-disasters/
[11] https://www.forbes.com/advisor/homeowners-insurance/home-insurance-outlook-2021/
[12] https://about.usps.com/newsroom/service-alerts/
[13] https://www.simpsonmccrady.com/article/what-to-know-about-cybersecurity
COVID-19 Business Interruption Coverage Alert
Simpson | McCrady, continues to monitor developments in various state and federal courts regarding claims by policy holders for business interruption coverage arising out of the disruption caused by the COVID-19 pandemic and how such decisions may potentially impact our clients.
Simpson | McCrady, continues to monitor developments in various state and federal courts regarding claims by policy holders for business interruption coverage arising out of the disruption caused by the COVID-19 pandemic and how such decisions may potentially impact our clients.
For those clients in Pennsylvania, and especially in Allegheny County, you should be aware that Judge Christine A. Ward of the Allegheny County Court of Common Pleas issued a decision on March 22, 2021, in the matter of Ungarean, et al. v. CNA and Valley Forge Insurance Company (GD No. 20-006544) that found in favor of a policy holder asserting it was entitled to business interruption coverage after its business was essentially closed due to the disruption of COVID-19 and the resulting “stay at home” orders that were issued by Pennsylvania Governor Wolf.
Judge Ward’s ruling departs substantially from other state and federal courts in Pennsylvania and/or other jurisdictions which have held that coverage did not apply in the absence of “direct physical loss or damage” to the business due to COVID-19. To the contrary, Judge Ward held that coverage under policies for a “loss” exists when a business has lost and/or been deprived of the use of its business property even in the absence of physical damage. This ruling potentially broadens the availability of business interruption coverage in a substantial manner in favor of policy holders who may assert such claims for coverage within Allegheny County.
A policy holder who previously decided to not pursue a claim and/or had a claim based upon a determination that they had not sustained “direct physical loss or damage” due to COVID-19 may now want to consult with an attorney regarding options for revived claims for coverage given the potential ramifications of Judge Ward’s decision, especially if located in Allegheny County.
While this is certainly potentially positive news for insureds, it is our understanding that an appeal of Judge Ward’s decision is likely. As this case, as well as several others across the United States, continue to progress – we will make every effort to keep you informed.
As always, please know that we are here to answer any specific questions you may have in regard to the ruling.
Cybersecurity: Ransomware
Cyber insurance policies have been in existence for about twenty years but have really developed over the past ten years. The primary purpose of these policies was initially to cover liability resulting from a data breach as well as reimbursement of notification costs tied to the breach.
Cyber insurance policies have been in existence for about twenty years but have really developed over the past ten years. The primary purpose of these policies was initially to cover liability resulting from a data breach as well as reimbursement of notification costs tied to the breach.
Although liability protection and data breach response costs are still major components of cyber insurance policies, recent years have led to broader policies that cover other types of claims such as extortion attacks, cyber related business interruption events, and funds transfer fraud resulting from social engineering attacks.
One emerging trend we have seen is a large rise in extortion or ransomware attacks. In a ransomware attack, a hacker sends a fake or fraudulent email to an unsuspecting employee within a company. Typically, the hacker will pretend to be a fellow employee (such as a CEO or CFO) or a client to disguise the attack. The email will include an attachment or file that looks legitimate and contains malware.
Once the employee clicks on the link, the hacker is able to gain access to the company’s network and will then encrypt sensitive systems or data. At this point, the company could have its day to day operations crippled.
For example, a manufacturer relying on IT systems to produce inventory may wake up to find its production equipment completely shut down and unable to manufacture product. A law firm may come into the office and realize they are unable to access case files or client information because these files have been encrypted.
At this point, the hacker will demand a ransom payment to unlock the systems or data. The ransom demand is usually made in Bitcoin or another form of cryptocurrency that is difficult to trace.
In a situation this fall, we had a client who was hit by one of these attacks and faced a Bitcoin ransom demand of over $1,000,000. With help from the insurance company and a third party negotiating firm, the ransom demand was negotiated down to a much lower amount and the company agreed to pay the ransom. When adding in the costs of using third party firms to deal with the incident, the overall cost to the company was sizeable.
A cyber insurance policy is key to responding to this type of attack as it offers a range of resources and protection to the business facing the attack.
The primary benefit of the company’s cyber policy is reimbursing the cost of the ransom payment and other ancillary expenses made in resolving the incident.
The secondary benefits are often just as important. These include the step by step guidance provided by the insurance company and its approved vendors for how to respond to the incident. A quick response can get the company back up and running quickly with as little impact to operations and ultimately the organization’s financials as possible.
As part of the policy, the insurance company and the negotiating firm are in place to handle the ransom negotiation and ultimately the payment. The third party negotiating firms used by the insurance companies face these types of negotiations on a daily basis and know the criminal organizations they are dealing with.
The policy also provides access to a panel of law firms specializing in cyber litigation. This is critical as it gives the company an outlet to determine if they face any legal liability or legal duty to notify affected customers or clients.
In addition, the policy can give the company access to a panel of vetted IT and forensics firms. These firms can be used to determine how the organization was breached and how systems and policies can be strengthened to avoid a similar attack in the future.
In the claim mentioned above, these resources and third party firms helped save the company hundreds of thousands of dollars and got the company back up and running quickly.
In summary, we have found all companies and organizations are vulnerable to these types of claims. In fact, smaller businesses and organizations are often more susceptible to these types of attacks as they typically do not spend the same level of resources on cybersecurity or training as large organizations.
If you have questions or would like to discuss cyber insurance in more detail, please reach out to a risk advisor at Simpson & McCrady to set up a time for a conversation.
To learn more, check out our previous summary on trends that we are seeing in the cyber insurance space. The article includes best practices and tips that you can utilize to strengthen your personal and/or corporate cybersecurity practices.
Disclaimer: This is a general overview of commercial cyber insurance. Coverage is determined based on the details surrounding a claim and are dependent on the limits, deductibles, terms, conditions, and exclusions of the policy.
Browse by Audience
Find the Insights Built for You
Private Client Insights
Complex personal insurance deserves clear, specific guidance, not a generic overview. Our private client resources cover fine art, jewelry, multiple properties, recreational vehicles, cyber liability, and the full range of coverage considerations for high-net-worth families and family offices. Written by advisors who work in this space daily, with the depth our clients tell us they don't find anywhere else.
Commercial Insights
Risk and benefits intelligence written for business owners and decision-makers, not for a general audience. From technology and manufacturing to professional services and non-profits, our commercial resources address the insurance and risk challenges facing middle-market companies across Western PA and the Mid-Atlantic region, grounded in the industries we actually serve.
Explore More Resources
Ready to Go Deeper?
An article is where understanding starts. Our case studies show how we've protected real clients (families and businesses who faced specific, consequential risks), and our advisor profiles put a name, background, and specialty behind every perspective you've read here. When you're ready to talk through your own situation, the path forward is direct.
The People
Meet the Advisors Behind the Guidance
Named advisors, not call centers. See who wrote the perspectives in this library and what each of them specializes in.
The Proof
Read Our Client Case Studies
Real families and businesses, specific consequential risks, and the outcomes our advocacy produced.
The Services
Explore the Practices Behind the Perspectives
Two practices, one standard of counsel, for your family's assets or your company's operations.